
First Financial Bankshares (FFIN) Posted Strong Q3 Results, Is The Recent Pullback A Valuation Opportunity?
First Financial Bankshares (FFIN) moved into focus after its Q3 2026 report, which paired higher profit figures and net interest income with a cautious market reaction and questions around the pace of balance sheet expansion.
The share price reaction has not been a one day story. First Financial Bankshares is trading at US$30.47 after falling 3.6% on the day of the Q3 release, with the share price down 7.1% over the past month and 12.4% over the last quarter. However, the 3 year total shareholder return of 38.8% indicates longer term holders have still seen meaningful gains, even as recent momentum has faded and investors reassess growth prospects and credit risk.
Compare how First Financial Bankshares stacks up against other regional lenders by scanning our hand picked list of solid balance sheet and fundamentals (25 results) for ideas with similar financial strength under fresh price pressure.
First Financial Bankshares just reported stronger earnings while the share price slipped, so the real tension now is simple: Is most of the easy upside already behind the stock, or does the recent pullback leave more on the table?
Most Popular Narrative: 17% Undervalued
On Simply Wall St's most followed narrative, First Financial Bankshares screens as undervalued, with a fair value of $36.57 against the recent $30.47 share price and a 7.24% discount rate framing that gap.
The shift of First Financial Bankshares into the tier of banks above US$10b in assets, combined with profitability metrics such as a 1.76% return on average assets and a 45.5% efficiency ratio compared with weaker peer averages, could support further operating leverage and help sustain earnings power if management continues to scale within its existing Texas footprint.
See why 2 investors see First Financial Bankshares as 17% undervalued.
Result: Fair Value of $36.57 (UNDERVALUED)
Still, the bullish case around First Financial Bankshares can be challenged if loan growth remains modest or if its premium P/E multiple compresses further.
Find out about the key risks to this First Financial Bankshares narrative.
Another View: What P/E Says About First Financial Bankshares
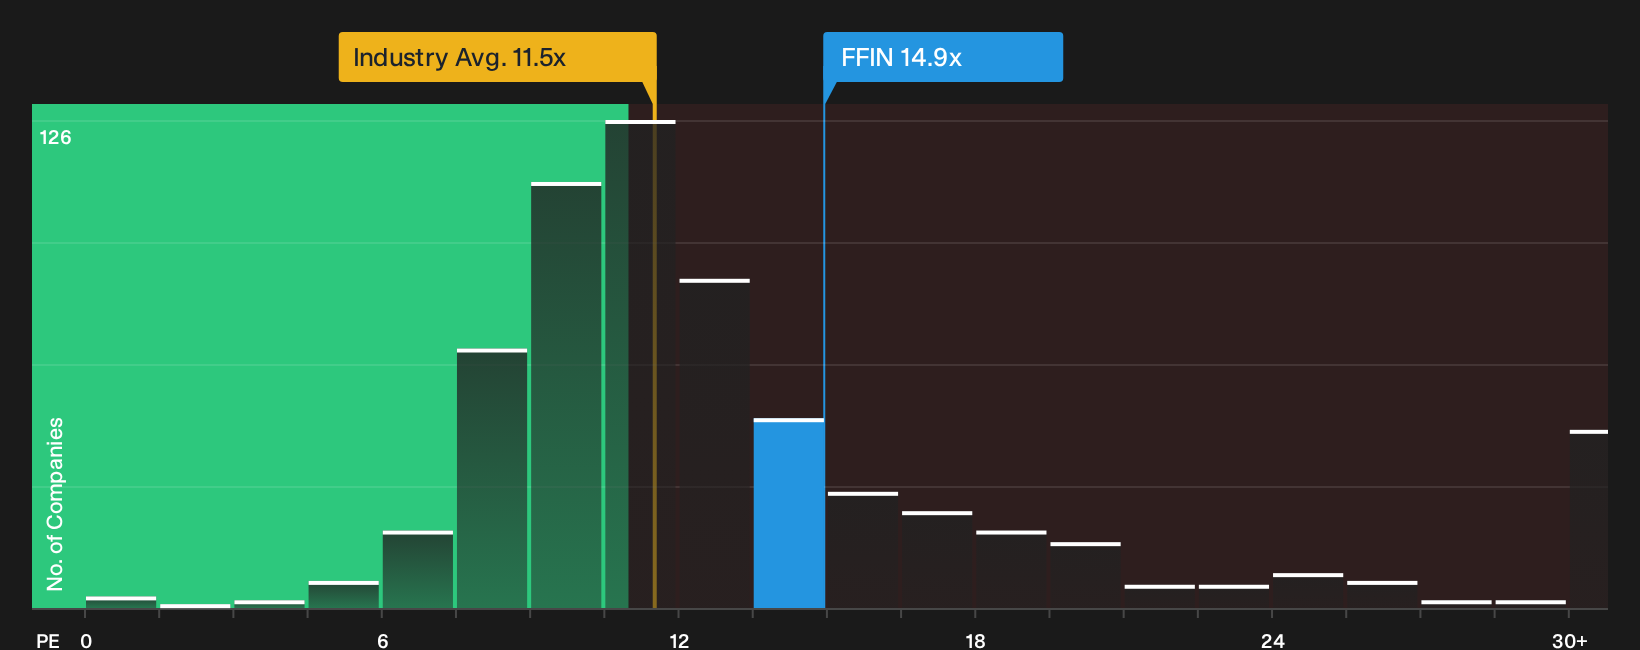
There is a catch. While the SWS model flags First Financial Bankshares as trading about 34.3% below its fair value, the plain P/E comparison sends a very different message.
On earnings, the stock changes hands at 14.9x. That is cheaper than the peer average of 23x, yet still richer than both the US Banks industry and its own fair ratio of 11.5x. For investors who worry more about overpaying on current profits than about long range cash flows, that gap can feel less like a margin of safety and more like valuation risk waiting to be repriced.
So which signal carries more weight for you right now: the discounted fair value estimate, or a P/E that still sits above where the market could move the ratio over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals from different valuation methods can be confusing, so it may help to act promptly and evaluate the complete picture yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond First Financial Bankshares?
If you stop with just First Financial Bankshares, you risk missing other opportunities that fit your goals, risk tolerance, and income needs in a more precise way.
- Target potential mispricing by scanning our 33 high quality undervalued stocks that filters for financially robust companies trading below their assessed worth.
- Lock in potential income streams by reviewing the 8 dividend fortresses that highlights higher yielding payouts with supporting fundamentals.
- Reduce portfolio stress by checking the 32 resilient stocks with low risk scores that focuses on businesses with stronger balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com