
Harley-Davidson (HOG) Dropped, What Is Driving Attention Now?
Harley-Davidson (HOG) is back in focus after a recent Citi upgrade and insider share purchases, moves that signal rising confidence even as LiveWire losses and revenue pressure keep investors focused on execution.
Across the past year, Harley-Davidson’s share price has had a choppy ride, with a 29.7% year to date share price return contrasting with a 3.43% total shareholder return over twelve months and weak total shareholder returns over three and five years. This suggests recent momentum has picked up as investors reassess profit potential and risk around LiveWire losses and cost saving plans.
Spot shifting sentiment around Harley-Davidson and then size up other potential rebound stories with our curated list of 33 high quality undervalued stocks.After a near 30% year-to-date rebound, Harley-Davidson now trades closer to analyst targets and industry P/E levels. Is most of the easy upside already in the mirrors, or does valuation still leave room for more?
Most Popular Narrative: 5% Undervalued
Harley-Davidson’s most followed valuation story pegs fair value at $28.18, a touch above the recent $26.76 close, which puts the recent rally in sharper context.
The partnership-driven shift in Harley-Davidson Financial Services toward a capital-light, fee-based servicing model, combined with the move from total debt plus deposits of US$7.4b to US$2.8b and a net cash position at HDMC, creates room for ongoing share repurchases and reinvestment that can support EPS and earnings quality. The Back to the Bricks cost program, which aims for at least US$150 million in run rate fixed cost savings and HDMC EBITDA of US$350 million or more by 2027 and is described as on track or slightly ahead after early headcount and cost of goods actions, provides Harley-Davidson with a clear path to support future operating margin and net income.
See why 13 investors see Harley-Davidson as 5% undervalued.
Result: Fair Value of $28.18 (UNDERVALUED)
Still, tariff costs and the tilt toward more affordable Harley-Davidson models could pressure margins and weaken the very earnings power that this narrative relies on.
Find out about the key risks to this Harley-Davidson narrative.
Another View: Harley-Davidson Through The P/E Lens
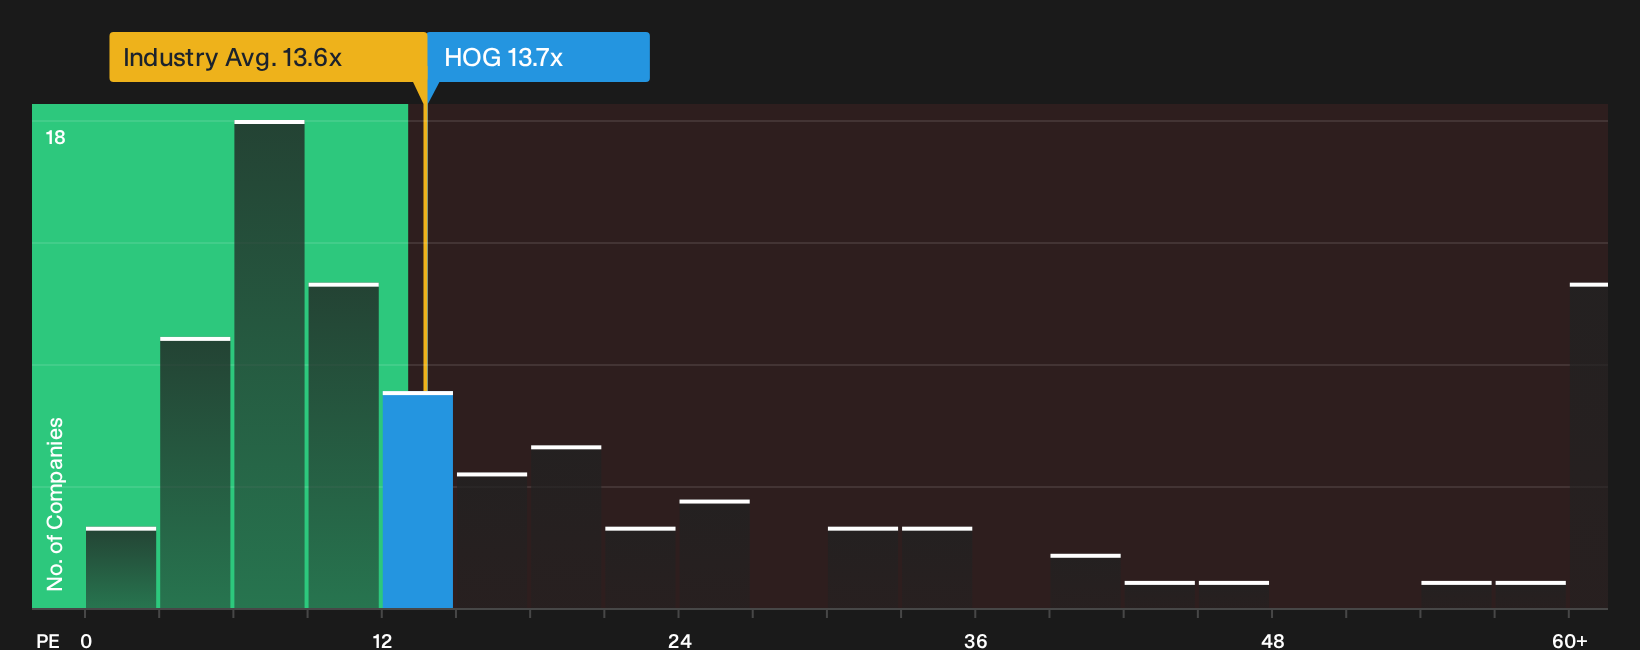
A second way to look at Harley-Davidson is through its P/E ratio. At 13.7x earnings, the stock is slightly more expensive than the global auto peer average of 13x and very close to the industry’s 13.6x level.
The fair ratio for Harley-Davidson is estimated at 15.2x, which is higher than where the shares trade today. That gap suggests the market is pricing in some risk relative to what the fair ratio implies, which leaves investors weighing whether that discount reflects caution or a potential opportunity.
For a closer look at how this earnings multiple compares with both peers and the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Harley-Davidson’s valuation, risks and rewards can be confusing, so consider reviewing the company while sentiment is evolving and test the numbers yourself using 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Harley-Davidson?
If Harley-Davidson has you thinking about what else could be mispriced, use the Simply Wall Street screener to spot other opportunities before the crowd catches on.
- Target potential rebound plays and underappreciated quality by scanning our curated pool of 33 high quality undervalued stocks.
- Strengthen your portfolio’s foundation by focusing on companies with healthier finances using the list of solid balance sheet and fundamentals (25 results).
- Lock in potential income ideas by reviewing a hand picked set of high yield candidates through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com