
Is Wendel (ENXTPA:MF) Cheap On Its Asset Management Leadership Push?
Wendel (ENXTPA:MF) has shifted attention to its growing third party asset management arm after appointing Bénédicte Rabier as Chief Product Officer for Wendel Investment Managers, effective 1 October 2026.
The appointment comes at a time when Wendel’s 1-year total shareholder return of 11.13% and 3-year total shareholder return of 34.46% contrast with a softer share price pattern. The 30-day share price return slipped 0.78% even as the stock has edged higher over 90 days and year to date. This hints that recent positive moves of 1.92% over one day and 3.65% over seven days may be rebuilding momentum after a longer, more mixed five-year total shareholder return that declined 10%.
Scan how Wendel's renewed asset management focus compares with peers by weighing it up against a hand picked 614 high quality undiscovered gems with similar fundamentals and under-the-radar potential.
Wendel trades at a sizeable discount to analyst targets after a mixed five year return record and fresh leadership moves in asset management. Is that gap a sign of warranted caution, or a mispricing that the numbers can clarify next?
Most Popular Narrative: 23% Undervalued
Against a last close of €82.25 for Wendel, the most followed narrative points to a fair value of about €106.67, so the gap between price and modelled worth is doing a lot of heavy lifting in this story.
Expansion of third-party assets under management, combined with a significant pipeline of undeployed capital and new product initiatives (retail fund offerings, European private credit), is set to increase fee-paying AuM, supporting top-line growth and earnings visibility for the asset management division.
Ongoing strategic portfolio rebalancing and asset recycling (divestment of mature or underperforming assets, potential sale of Stahl post-carve-out) frees up liquidity and enables higher reinvestment rates into higher-ROIC opportunities, supporting future revenue growth and net margin improvement.
See why 5 investors see Wendel as 23% undervalued.
The narrative uses a €106.67 fair value for Wendel, built off analyst forecasts that are discounted at 9.93% to reflect risk and time value. That framework leans on expectations for the asset management arm, portfolio reshaping and modest margin recovery, then rolls those projected cash flows and earnings into a single present value anchor.
Analysts in that narrative expect Wendel to move from a reported loss today to positive earnings over the coming years, with profit margin assumptions shifting from slightly negative to slightly positive. They also assume revenue growth that is steady rather than rapid, which keeps the discount rate and required future P/E of about 29x as key swing factors for anyone comparing this story with broader diversified financial peers.
Result: Fair Value of €106.67 (UNDERVALUED)
Still, that story can break if fundraising at Monroe and IK stalls in a tougher capital raising market, or if FX swings continue to erode reported asset values.
Find out about the key risks to this Wendel narrative.
Another Angle On Wendel’s Valuation
The earlier fair value story leans on earnings forecasts and analyst price targets. Our DCF model tells a different story. On that lens, Wendel at €82.25 trades above an estimated future cash flow value of €62.34, which flags the shares as overvalued rather than cheap. Which lens do you trust more: the cash flows or the earnings multiple story?
For a closer look at how this gap is built up through long term cash flow assumptions and discount rates, take a few minutes with the Look into how the SWS DCF model arrives at its fair value..
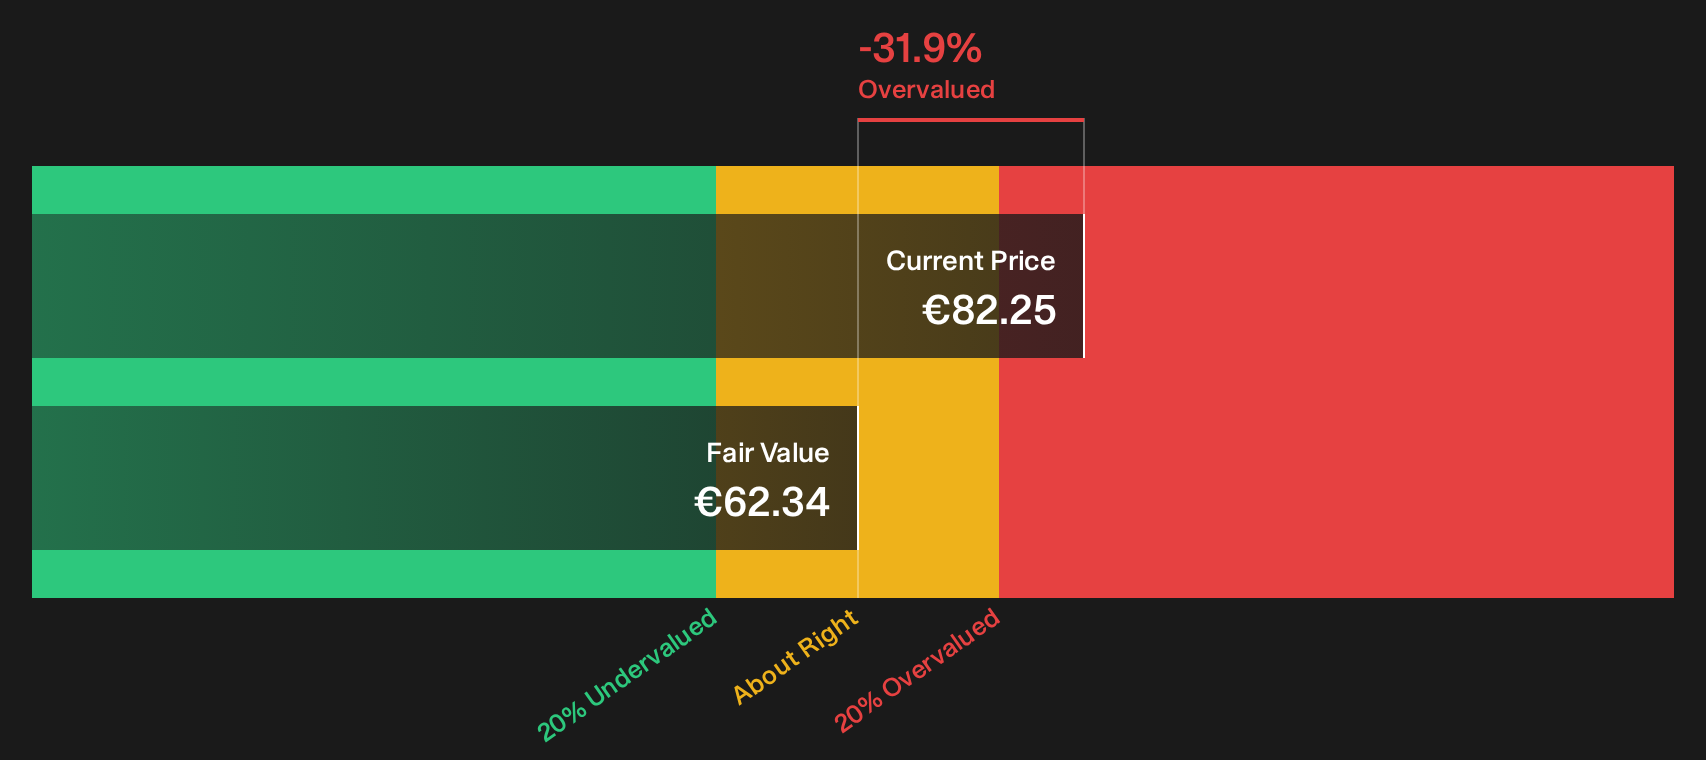
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wendel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Wendel is clearly split. Move quickly, look through the data for yourself, and weigh both sides of the debate with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wendel?
If Wendel has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted stock ideas that match different risk and return preferences.
- Target potentially mispriced opportunities by scanning a curated 189 high quality undervalued stocks that blend strong fundamentals with attractive entry points.
- Strengthen your income stream by reviewing a focused 215 dividend fortresses built around higher yields and durable payout records.
- Dial down risk while staying invested by checking a 232 resilient stocks with low risk scores that screens for sturdier balance sheets and more resilient business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com