
3 Australian Undervalued Stocks For October 2026
Oil prices hovering near multi month highs are pushing investors back toward hard numbers such as cash coming through the door. When energy and shipping costs shift, businesses with solid cash generation but muted share prices can quietly become interesting. Australian investors scanning for value now have a chance to look at companies where discounted cash flow models flag a gap between price and potential, and this article highlights three such stocks.
The three stocks below are just a starting sample, and the full screen surfaced 8 more companies with equally cash focused stories that are not covered here.
Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the ideas that best fit your own value checklist.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper producer whose Havieron project in Western Australia is central to its future mine cash flows, with the business currently generating A$2.26b from the Telfer Havieron segment and carrying an equity value around A$6.69b.
For investors focused on discounted cash flow potential, Greatland Resources offers a relatively direct way to gain exposure to a single large project where cash generation is the main story. The next phase of its journey is captured neatly in the following quote.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What happens if one key moving part behind those future cash flows shifts even slightly away from current expectations?
If that shift matters to your thesis on Greatland Resources, the full narrative for Greatland Resources outlines how cash flows, funding and project timing could be decoupling from headline sentiment.
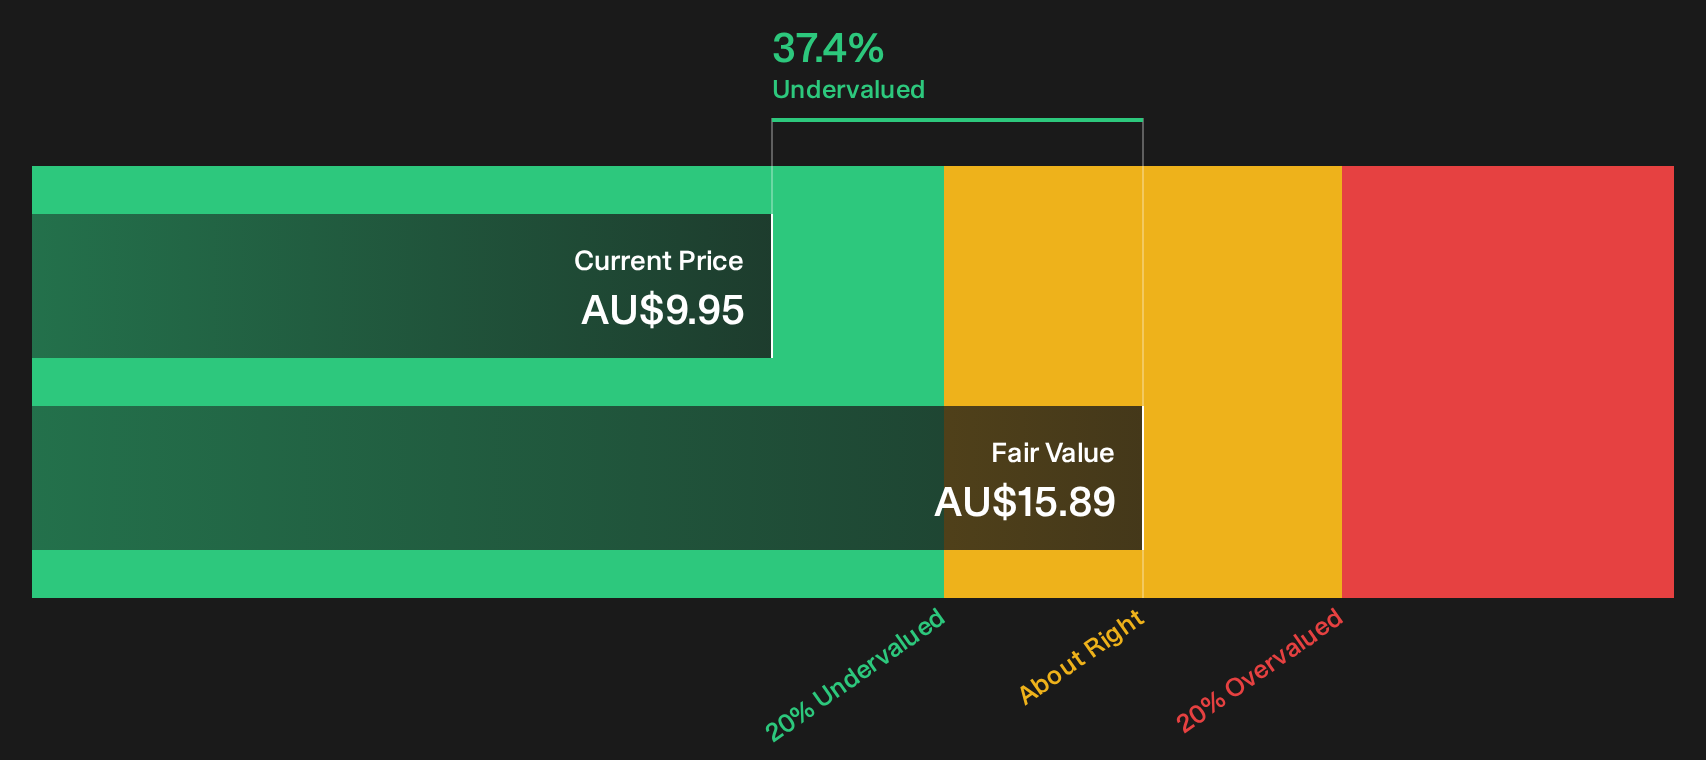
Ansell (ASX:ANN)
Ansell is a global protective gear specialist whose Healthcare arm, built around recurring glove and medical disposable sales, anchors its cash flow story, while the Industrial division broadens exposure to factory, construction and energy customers worldwide.
Healthcare brings in about US$1.19b of revenue and Industrial generates roughly US$947 million, with the group supported by an equity value near A$6.4b.
Ansell’s Healthcare glove lines, which are repeat‑use essentials for hospitals and labs, are a key reason it features in a cash‑flow‑focused value screen, even though Industrial safety gear also accounts for a sizeable share of activity.
Ansell matters for this list because investors are effectively weighing a global safety supplier with recurring Healthcare cash inflows against what a discounted cash flow model suggests those streams might be worth.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
The big watchpoint now is what happens to profitability if one less visible cost pressure shifts away from recent trends.
If that cost line is what you are watching, the full narrative for Ansell explains how shifting inputs, pricing power and product mix could be masking where Ansell’s next leg of strength comes from.

Origin Energy (ASX:ORG)
Origin Energy is an integrated power and gas group. Energy Markets generates about A$15.3b of revenue, while Integrated Gas adds roughly A$307 million through gas production and LNG sales that tie directly to the cash flow theme, with the stock valued around A$20.7b.
Origin Energy connects this cash flow focused screen to the real economy through its gas production and LNG business, which helps anchor steady earnings even as the rest of the portfolio leans into the energy transition.
"Capital-heavy investments in renewables, storage, and international software platforms (Kraken/Octopus) are being valued as sources of near-term EBITDA growth. However, these ventures may face execution risks and cost overruns, which could compress return on capital and drag on future earnings."
What happens to margins and cash returns if a single assumption about how quickly these newer platforms scale up proves even slightly off course?
If that scaling risk is on your radar, the full narrative for Origin Energy shows where Origin Energy’s LNG cash engine and transition bets could be quietly moving away from expectations.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, not last. While attention chases yesterday’s winners, new breakouts and quiet momentum often get missed under the radar for now.
- Spot steady cash engines and reduce balance sheet surprises by scanning the curated list of solid balance sheet and fundamentals (12 results) before others catch companies strengthening their financial footing.
- Track the next infrastructure developments by following power upgrades, grid tech and transmission specialists inside the hand picked 42 power grid technology and infrastructure stocks while market interest is still forming.
- Review the focused 55 AI infrastructure stocks to monitor how demand for chips, data centers and backbone tools could be building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com