
Stella International Holdings (SEHK:1836) Jumped, What Is Behind The Fresh Attention?
Stella International Holdings: Revenue Update Triggers Fresh Look
Stella International Holdings (SEHK:1836) just released unaudited revenue figures for the quarter and first nine months to 30 September 2026, giving investors fresh data after a period of operational reshuffling.
The footwear manufacturer reported third quarter revenue of US$412.9 million, compared with US$404.2 million a year earlier, and nine month sales of US$1,199.6 million versus US$1,179.2 million, in line with its mid term plan.
This performance came while shipment volumes were lower. Production was brought forward for a major customer, and a Philippines factory entered a phased shutdown, with output gradually transitioning to other regions.
Stella International Holdings has seen a pickup in momentum recently, with a 1 month share price return of 14.1% and a 7 day gain of 7.02%, even though the share price is still down 13.98% year to date and the 1 year total shareholder return is down 5.43%.
Over a longer stretch, the picture is very different, since the 3 year total shareholder return of 101.31% and 5 year total shareholder return of 126.69% show how strongly longer term holders have been rewarded. The latest revenue update is landing against that backdrop of earlier gains and a weaker recent 90 day share price return that declined 5.89%.
Compare Stella International Holdings with a curated 189 high quality undervalued stocks that also pair steady execution with solid balance sheets and may be positioned for the next leg of momentum.
Stella International Holdings appears to be a solid footwear platform on the operations side, yet the share price has only just started to wake up again. Is this still a quality business offered at a reasonable tag today?
Most Popular Narrative: 11.3% Undervalued
The most followed valuation narrative currently places Stella International Holdings at a fair value of HK$14.78 against a last close of HK$13.11. That gap rests on detailed assumptions about future earnings, margins and the discount rate of 8.64% used to bring those forecasts back to today.
Stella's ongoing expansion of manufacturing capacity, adding up to 25 million pairs across Indonesia and Bangladesh with dedicated facilities for top global brands, positions the company to benefit from increasing demand for premium and branded footwear as rising middle-class incomes and consumer upgrading trends continue globally. This is set to drive revenue growth and improve long-term earnings visibility.
See why 1 investors see Stella International Holdings as 11% undervalued.
Result: Fair Value of HK$14.78 (UNDERVALUED)
Still, rising labor and production costs, along with heavy reliance on a few large global customers, could quickly challenge the current valuation story for Stella International Holdings.
Find out about the key risks to this Stella International Holdings narrative.
Another View: Stella International Holdings On Earnings Multiples
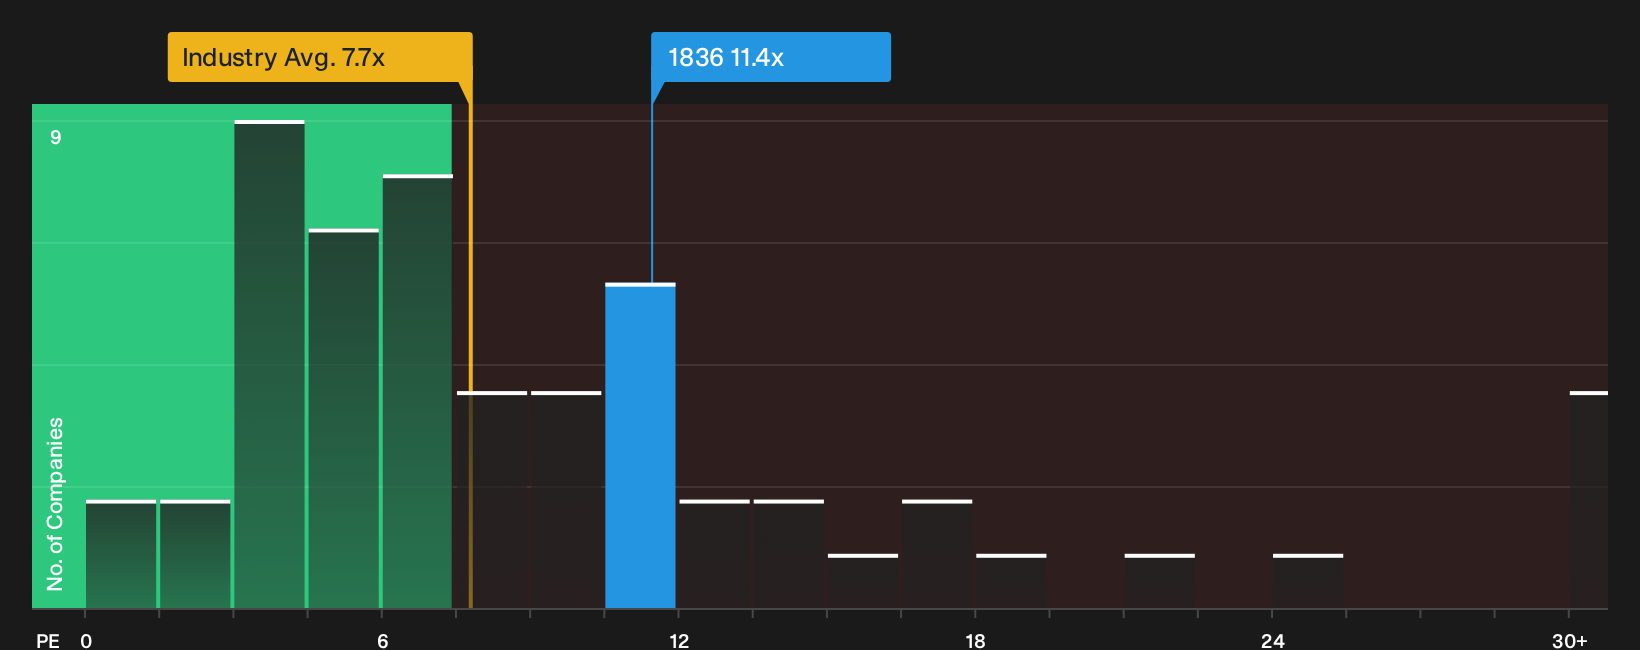
That 11.3% gap to fair value based on future cash flows is only one lens. On plain earnings, Stella International Holdings trades on a P/E of 11.4x, while the Hong Kong Luxury group sits at 7.7x and the fair ratio sits at 8.1x. The market is already paying a premium. Is that extra multiple breathing room or valuation risk if sentiment shifts?
For a closer look at how this earnings-based view compares with peers, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of cautious optimism and live debate around Stella International Holdings resonates, move quickly and stress test the story against both sides of the data, starting with the 2 key rewards and 1 important warning sign.
Ready For More Stock Ideas Beyond Stella International Holdings?
If Stella International Holdings has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more options when conditions change.
- Target resilient compounding potential by scanning a curated 189 high quality undervalued stocks that combine disciplined execution with supportive fundamentals and may suit investors who want quality at a measured price.
- Strengthen your income stream by reviewing a focused 215 dividend fortresses that aim to pair higher yields with balance sheet support and consistent shareholder payouts.
- Dial down portfolio stress by assessing a 232 resilient stocks with low risk scores that tilt toward sturdier financial profiles so short term swings do not dominate your decisions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com