
Learn Why The Bull Case For Best Buy Stock Could Change Following TV Ad Partnership
- LG Ad Solutions and Best Buy Ads recently announced a partnership that gives retail media advertisers access to LG Electronics' U.S. TV ecosystem, including previously unavailable Home Screen inventory, with programmatic buying through Magnite and Best Buy's closed-loop measurement.
- The collaboration connects Best Buy's first-party shopper audiences with LG's premium connected TV formats, tying advertising exposure more directly to recorded sales activity for consumer electronics brands.
- Investors will be watching how Best Buy's investment narrative around higher-margin Best Buy Ads is influenced by this expanded access to LG TV inventory.
Scan how Best Buy's ad partnership fits into a bigger retail media trend by reviewing 20 high quality undiscovered gems quietly building similar data and distribution advantages.
Best Buy Investment Narrative Recap
To hold Best Buy, an investor has to believe this retailer can keep tech upgrade cycles flowing while leaning harder on services, membership, Marketplace and advertising to support profitability. The near term focus sits on whether higher margin lines like Best Buy Ads and Marketplace can keep earnings resilient while core categories face product mix and pricing pressure.
The LG Ad Solutions deal ties directly into that thesis because it adds fresh connected TV inventory to Best Buy Ads, although the financial impact is not yet clear. The biggest near term risk still revolves around expense pressure outpacing newer revenue streams. This could weigh on operating income if ad, membership and Marketplace momentum slows.
The most relevant recent development for this story is the wider build out of Best Buy Ads itself, which previously collected about US$900m in ad spend and is targeted by analysts to grow by around 10%. That ad business already sits alongside Marketplace GMV of roughly US$1.3b. Together, these figures point to a meaningful shift toward fee based income.
The LG partnership plugs into that existing retail media engine by giving those Best Buy Ads audiences access to LG Home Screen and broader CTV video inventory, with programmatic buying through Magnite and closed loop measurement. For investors watching catalysts, execution now hinges on how effectively Best Buy monetizes these impressions while keeping selling and tech costs contained.
Best Buy's current analyst narrative points to revenues of US$44.0b and earnings of US$1.6b by 2029, based on an assumed 1.4% yearly revenue growth rate and a move in profit from US$1.3b today. This implies an earnings increase of about US$0.3b by that forecast year.
Uncover why Best Buy's fair value indicates a 6% potential downside to its current price, leaving little room for error.
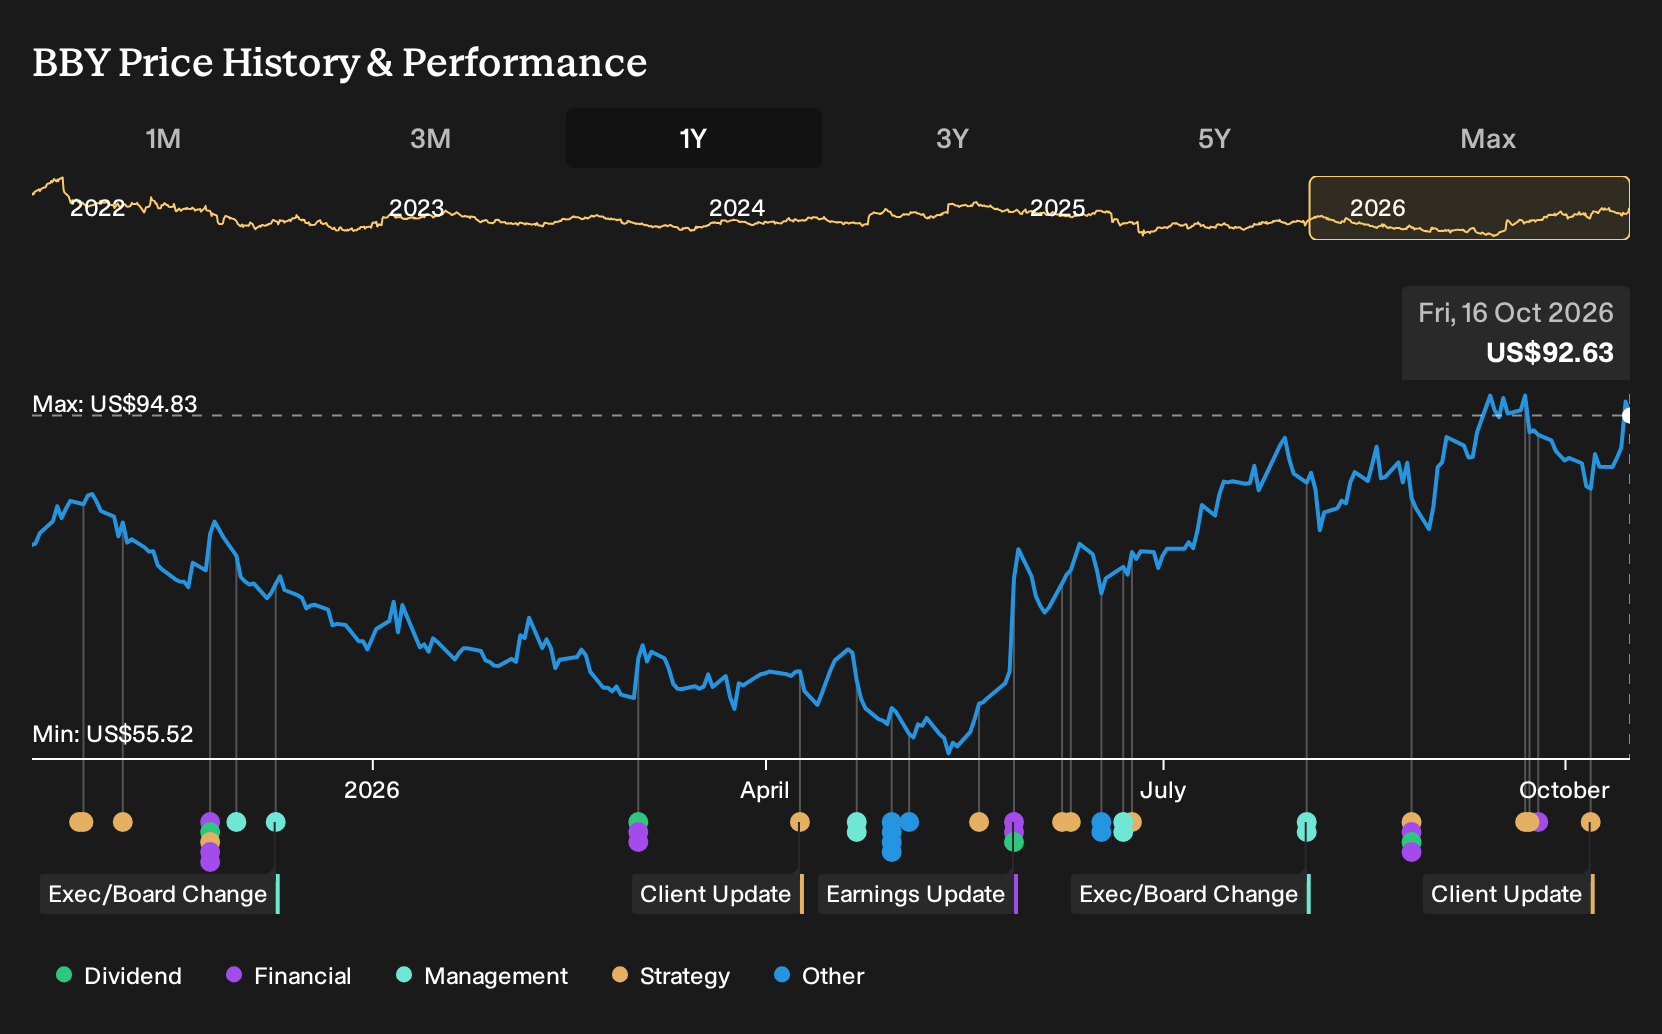
Exploring Other Perspectives
One alternate view leans on Best Buy Ads as a bigger upside swing factor than the consensus gives credit for. Bullish analysts were already penciling in US$45.0b of revenue and US$1.6b in earnings by 2029 before this LG TV deal. You can read that as a more optimistic story that might shift further once this new CTV access is fully reflected in forecasts.
Explore 6 other Best Buy fair value estimates, including one that suggests as much as 103% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Best Buy research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Best Buy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Best Buy's overall financial health at a glance.
Looking for more investment ideas beyond Best Buy?
Once you have a view on Best Buy, it often helps to compare it with other opportunities that share similar qualities, whether you care most about quality, income, or resilience. Use the Simply Wall St Screener to line up peers side by side and see how they stack up against the traits you value most.
- For investors chasing quality at a discount, scan the market using 33 high quality undervalued stocks that blend strong fundamentals with appealing valuations.
- If capital preservation is your priority, filter for 32 resilient stocks with low risk scores that pair sturdier balance sheets with lower risk scores.
- To spot future leaders before the crowd catches on, focus on 20 high quality undiscovered gems that already show solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com