
3 Japanese Growth Stocks With Earnings Growth Up To 28%
Global inflation picked up to 3.7% in September, driven mainly by higher energy costs. Rising fuel and power bills can squeeze household budgets, yet they can also focus attention on businesses that are still expected to grow earnings and keep their finances in check. This article looks at three Japanese high growth potential stocks from our screener, highlighting why they might appeal to investors hunting for resilient expansion.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses with balance sheets that analysts still view as acceptable. However, if you want the absolute best, these 17 best high growth potential stocks are the cream of the crop.
Sansan (TSE:4443)
Overview: Sansan is a Tokyo based SaaS provider whose core cloud platform helps companies manage business contacts, meetings, and related workflows.
Operations: Sansan generates about ¥48.9 billion from its Sansan and Bill One business and ¥7.1 billion from Eight, almost entirely in Japan.
Market Cap: ¥251.5 billion
Sansan is linked to the Healthy high growth potential theme, with a contact management SaaS engine that supports recurring revenue and earnings expansion. The company has issued guidance that indicates an expectation of higher profit and stable dividends. Investors watching for strong growth with acceptable finances may find the most interesting signal in how one less visible pressure could influence future margins.
That potential margin squeeze is exactly why it pays to see the full picture with the 3 key rewards and 1 important warning sign and understand how Sansan’s growth story could evolve.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor test equipment and probe cards that help chipmakers validate chips and improve manufacturing yields.
Operations: The business generates about ¥84.9 billion from the probe card segment and ¥1.4 billion from test equipment, across Japan and other Asian markets.
Market Cap: ¥521.5 billion
Micronics Japan aligns with the Healthy high growth potential theme, with trailing earnings growth of 89.4% and forecast earnings expansion of about 24.9% per year over the next 3 years. That outlook is closely connected to probe card demand for memory semiconductors, which concentrates risk around what may happen if a single key assumption does not hold.
If that hinges on a single assumption, read the 2 key rewards and 1 important major warning sign to see whether Micronics Japan's growth story is stretching or still grounded in its fundamentals.

Kasumigaseki CapitalLtd (TSE:3498)
Overview: Kasumigaseki Capital develops and operates solar power projects alongside real estate consulting, warehouses, apartment hotels, healthcare facilities, and overseas ventures in Japan.
Operations: Kasumigaseki Capital generates ¥163,756 million from its real estate consulting business, entirely from projects and assets located in Japan.
Market Cap: ¥171.0 billion
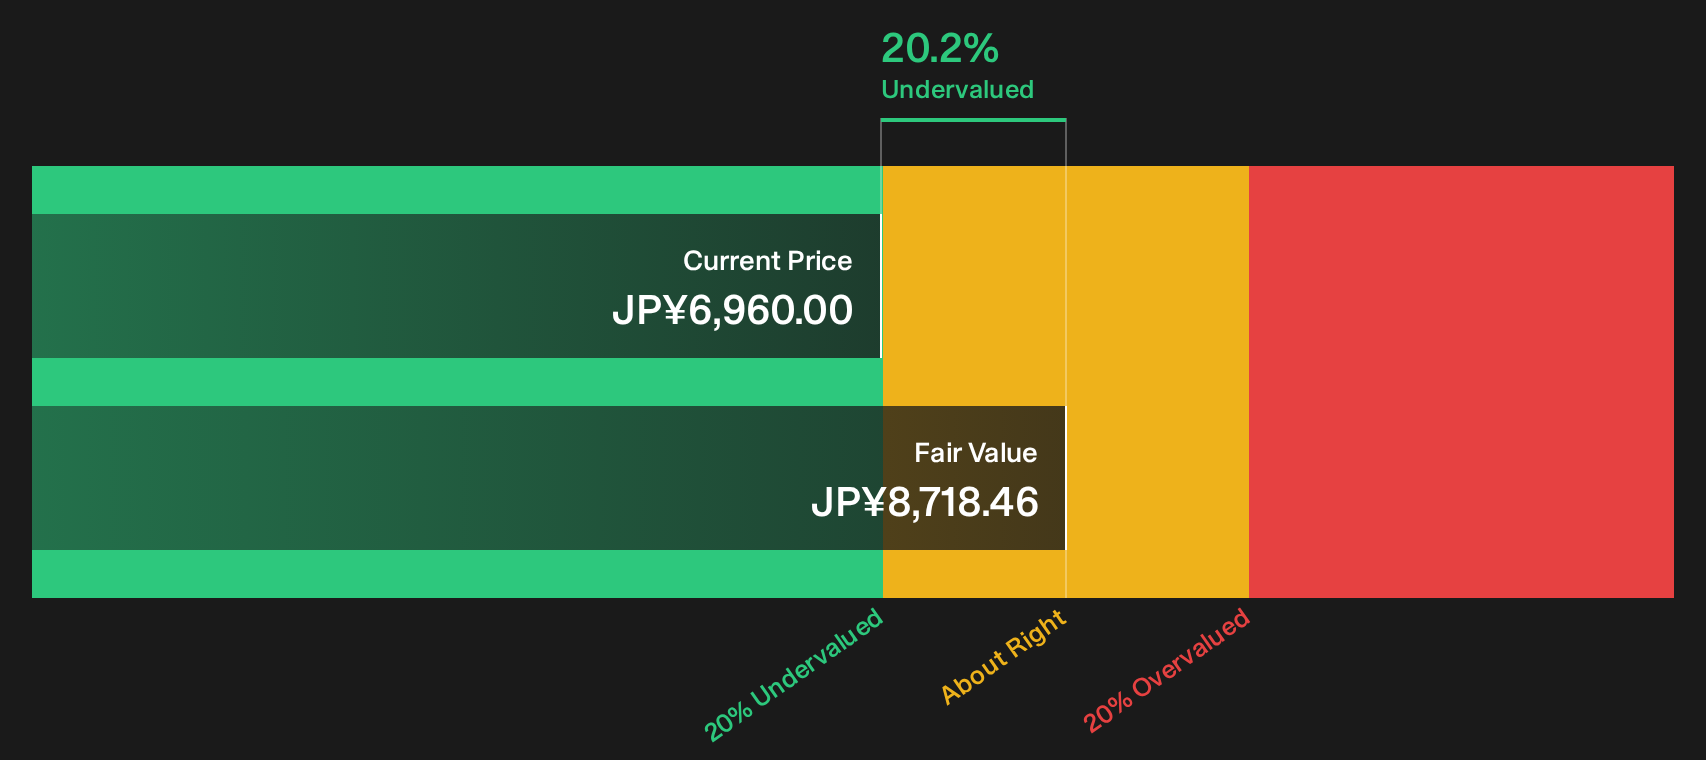
Kasumigaseki Capital aligns with the Healthy high growth potential theme based on analyst expectations of about 27.89% yearly earnings growth and a stock price roughly 20.2% below estimated fair value, supported by a growing portfolio of solar and property assets that may change significantly if one funding-related assumption shifts.
That funding swing is exactly where the 4 key rewards and 5 important warning signs (2 are major!) could reshape how you view Kasumigaseki Capital's upside relative to its capital stack pressure
Curious About Alternative Stock Paths?
Fresh ideas do not stay under the radar for long. Momentum builds, prices move, and the cleanest entry points can disappear before the crowd even looks. Consider exploring these themes while they may still be developing.
- Explore potential income opportunities by scanning a curated pool of potential yield candidates through the 29 dividend fortresses while yields still look attractive.
- Track early movers in real-world AI adoption by following companies inside the 39 profitable AI stocks that aren't just burning cash before any balance of growth and profitability becomes widely recognized.
- Review potential infrastructure beneficiaries by examining the curated 42 power grid technology and infrastructure stocks and see which operators are already participating in grid upgrade activity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com