
Dutch Bros (BROS) Is 52% Below Its All-Time High: Here's 1 Reason to Buy and 1 Reason to Pause.
Key Points
Dutch Bros has carved out a successful niche in the industry, but that hasn't helped the stock price in the past couple of years.
Management has its foot on the gas, with aggressive store expansion being a key part of the strategy.
The retail coffee market is fiercely competitive, with international and regional players all fighting for the same customer.
Dutch Bros (NYSE: BROS) has seen its name recognition grow over the years. Credit goes to the success of its small-format and drive-through locations. In addition to coffee, it sells a long list of customizable drinks. The company's customer service is a big draw.
It's not easy to establish a solid position in the retail coffee industry. However, Dutch Bros has successfully carved out a niche in the market.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
While the business is a success, the coffee stock has been wildly volatile. It currently trades 52% below its record high (as of Oct. 15).
Investors should listen to the bulls and the bears. Here's one reason to buy shares and one reason to pause.
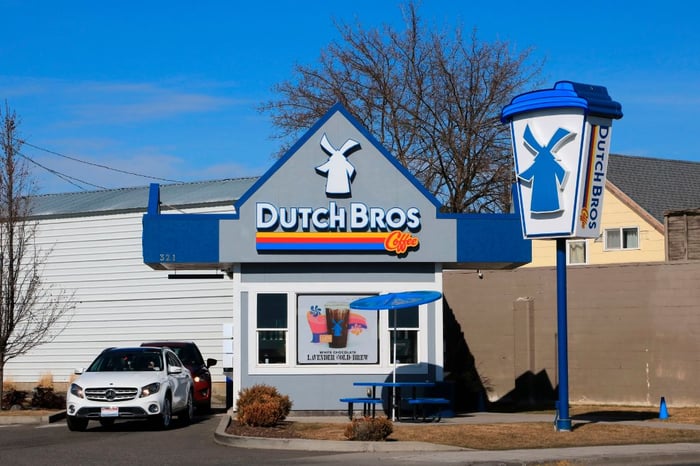
Image source: Getty Images.
Reason to buy: Projected store growth offers exciting possibilities
The main reason investors should consider buying the stock is its growth trajectory. As of June 30, there were 1,225 Dutch Bros locations in total. That's up 17% from 12 months ago. Management believes that it has a total addressable market of 7,000 stores. That would be almost six times larger than the current footprint.
The coffee chain has a strong presence in the western and southern parts of the U.S. That still leaves plenty of expansionary runway across the country. In May, for instance, the first Dutch Bros location opened in the Chicago area. New stores, of course, support higher revenue over time.
But each shop is also becoming more productive. Dutch Bros reported same-store sales growth in the last 13 straight quarters. That's a promising indicator at a time when the macroeconomic environment has pressured consumer confidence.
Analysts project the top line will rise 97% from 2025 to 2028. With the stock significantly off its highs, robust growth can be a tailwind for investors.
Reason to pause: The retail coffee market is crowded
This industry is extremely competitive. Barriers to entry are low, opening up the door to new rivals. And customers have no switching costs; they can spend their money wherever they please with each transaction.
So, it's valid to question if Dutch Bros has a durable moat. Its brand is becoming more well-known, to be fair. Does this drive loyalty over time, though? That's hard to say.
The challenging industry backdrop might give investors pause. There is competition all over the place. Large chains like Starbucks, McDonald's, and Dunkin' have massive footprints that support their scale advantages. Dutch Bros can't go toe-to-toe with them when securing favorable real estate, marketing efforts, or procuring coffee and other key inputs.
There is also pressure coming from direct competitors. Smaller players like 7 Brew and Biggby Coffee operate with similar strategies. Customers can easily start to favor them if they pop up nearby.
Dutch Bros' growth has been impressive, but the company's future success is far from guaranteed.
Neil Patel has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Dutch Bros and Starbucks. The Motley Fool recommends the following options: long January 2028 $320 calls on McDonald's and short January 2028 $340 calls on McDonald's. The Motley Fool has a disclosure policy.