
Learn Why The Bull Case For Huntington Ingalls Industries Stock Could Change Following AUKUS Navy Contract
- Huntington Ingalls Industries' Newport News Shipbuilding division secured a US$56 million U.S. Navy contract, with an option up to US$91 million, to provide engineering and design support for the AUKUS submarine program, including SSN-AUKUS work and broader technology, supply chain and workforce initiatives across the U.S., U.K. and Australia.
- In the same period, HII has invested in hiring events across its Newport News, Charleston and Ingalls Shipbuilding operations, indicating an effort to align workforce capacity with long-duration nuclear submarine and carrier responsibilities linked to AUKUS and other U.S. Navy programs.
- We will now look at how this AUKUS engineering award could influence Huntington Ingalls Industries' long-term shipbuilding margin narrative.
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to believe its huge backlog in carriers, submarines and Mission Technologies can be turned into steadier cash flow and higher shipbuilding margins. The recent AUKUS engineering award supports that long term story, but at US$56 million with an option to US$91 million, it is not likely to change the near term cash profile by itself.
The more immediate swing factor remains whether 2026 free cash flow, guided to be heavily back end weighted, actually comes through. Execution risk on carrier programs such as CVN 80, together with debt that is not well covered by operating cash flow, still looks like the biggest constraint on the Huntington Ingalls Industries margin narrative.
The most relevant update alongside AUKUS is HII ramping hiring across Newport News, Ingalls and the newer Charleston operations. That recruitment push matters for investors because the whole margin and cash flow story rests on higher throughput and more reliable schedules across nuclear carriers, Virginia and Columbia submarines and refueling programs.
If Huntington Ingalls Industries can staff and train those hundreds of new shipbuilders effectively, it is better positioned to meet rising funded demand from recent multibillion dollar Virginia, Columbia and carrier overhaul contracts. If labor, training or supply chain strain outpaces that build out, the risk is that shipbuilding margins and the 9% to 10% target stay out of reach for longer.
Huntington Ingalls Industries' current analyst narrative points to revenue of US$15.3b and earnings of US$965.0m by 2029. This outlook is built on assumed yearly top line growth of 5.2% and an increase in profit margins from 5.0% today to 6.3%, which would mean earnings rising by US$304.0m from US$661.0m on the latest analyst consensus path.
Uncover how Huntington Ingalls Industries' fair value indicates a 31% potential upside to its current price, which could narrow quickly.
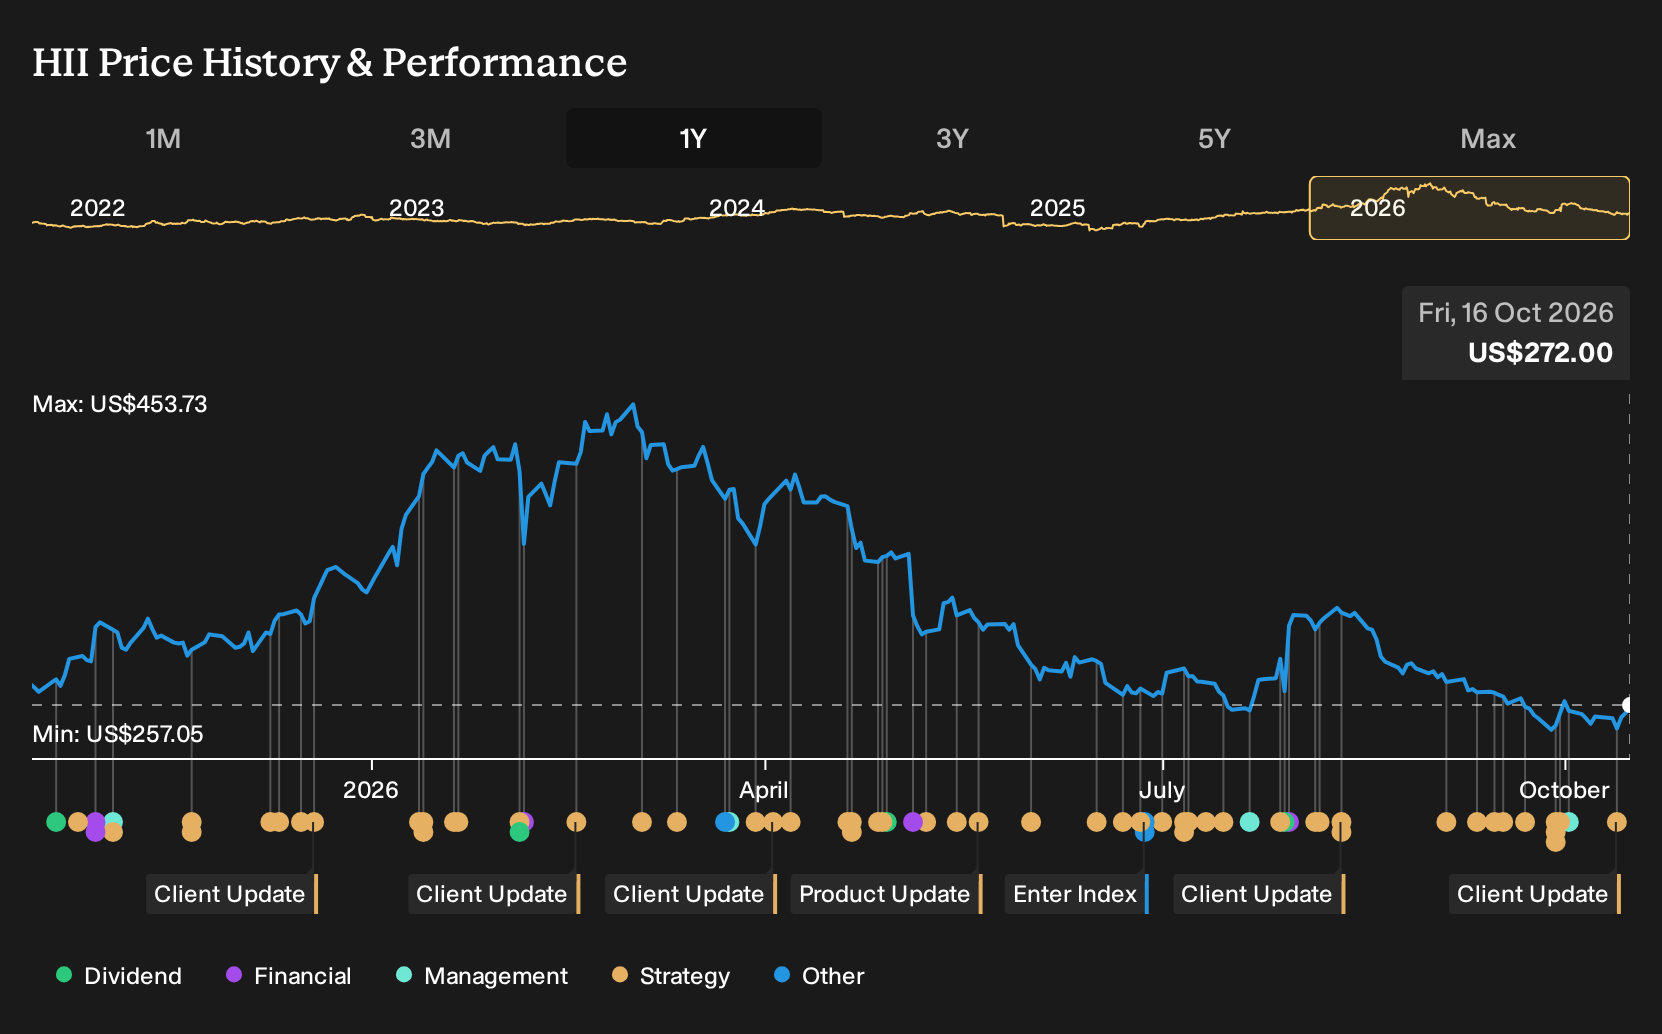
Exploring Other Perspectives
You might view the AUKUS contract as a test of the bullish workforce story around Huntington Ingalls Industries. The most optimistic analysts were already pencilling in about US$16.3b of revenue and US$1.2b of earnings by 2029 before this news. Those forecasts could look conservative or stretched once updated views reflect these announcements.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests potential upside of as much as 79% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking for more investment ideas beyond Huntington Ingalls Industries?
If the Huntington Ingalls Industries story has sharpened your thinking and you want to pressure test your thesis against a wider opportunity set, the Simply Wall St Screener can help you quickly surface stocks that better align with your risk tolerance and income or growth goals.
- For investors focused on quality at a reasonable price, scan a curated group of companies that pair solid fundamentals with attractive valuations using our 33 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, narrow your watchlist to businesses that score well on financial resilience and risk using the 32 resilient stocks with low risk scores.
- For those hunting for future leaders before the crowd arrives, broaden your opportunity set with a hand picked pool of companies that combine strong fundamentals with lower market attention through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com