
Did AI Workflow Launch Just Shift EPAM Systems (EPAM) Investment Narrative?
- EPAM Systems recently introduced a new AI-focused service that builds a foundational intelligence layer for frontier models, targeting complex, specialized enterprise workflows with high-fidelity data generation, rigorous model evaluation and custom reinforcement learning environments.
- The offering leverages EPAM Systems' multi decade experience with intricate enterprise workflows to create secure simulation environments that stress test multi step, tool using AI agents before deployment, directly addressing reliability and governance needs for large organizations.
- The next area of focus is how EPAM Systems' new frontier AI simulation and workflow offering could influence its broader investment narrative.
Scan beyond EPAM Systems and see how other AI infrastructure players are gearing up for the same shift into complex enterprise workflows with our curated 55 AI infrastructure stocks.
EPAM Systems Investment Narrative Recap
To hold EPAM Systems, investors need to believe the pivot toward AI native and consulting heavy work can offset softer demand and slower decision making in its core markets. The new frontier AI simulation service fits this story, but does not immediately change the near term reality of reduced 2026 growth guidance and muted North American momentum.
The main near term catalyst is execution on larger AI led programs that can stabilize revenue and support the current margin ambitions. The biggest risk remains a prolonged drag in North America combined with weaker free cash flow, where recent quarterly losses and longer collection cycles already point to pressure on cash generation.
The new AI simulation and workflow offering sits alongside EPAM Systems' applied AI work with Anthropic and its OpenAI Advanced Partner agreement, which is intended to certify thousands of specialists. Together, these efforts point the operational focus toward higher value AI projects that can support larger engagement sizes if clients follow through with spend.
For catalysts, the key question is whether this cluster of AI services helps EPAM Systems convert its pipeline of large AI led consolidation and agentic managed services deals into revenue from 2027. Execution risk is real. The firm still needs to balance investment in these complex offerings with tighter working capital so that cash generation does not lag reported earnings for too long.
EPAM Systems' narrative projects US$6.3b revenue and US$539.8 million earnings by 2029. This builds in 4.1% yearly revenue growth and an earnings increase of about US$138.1 million from current earnings of US$401.7 million.
Discover why EPAM Systems' fair value appears to be essentially in line with its current price.
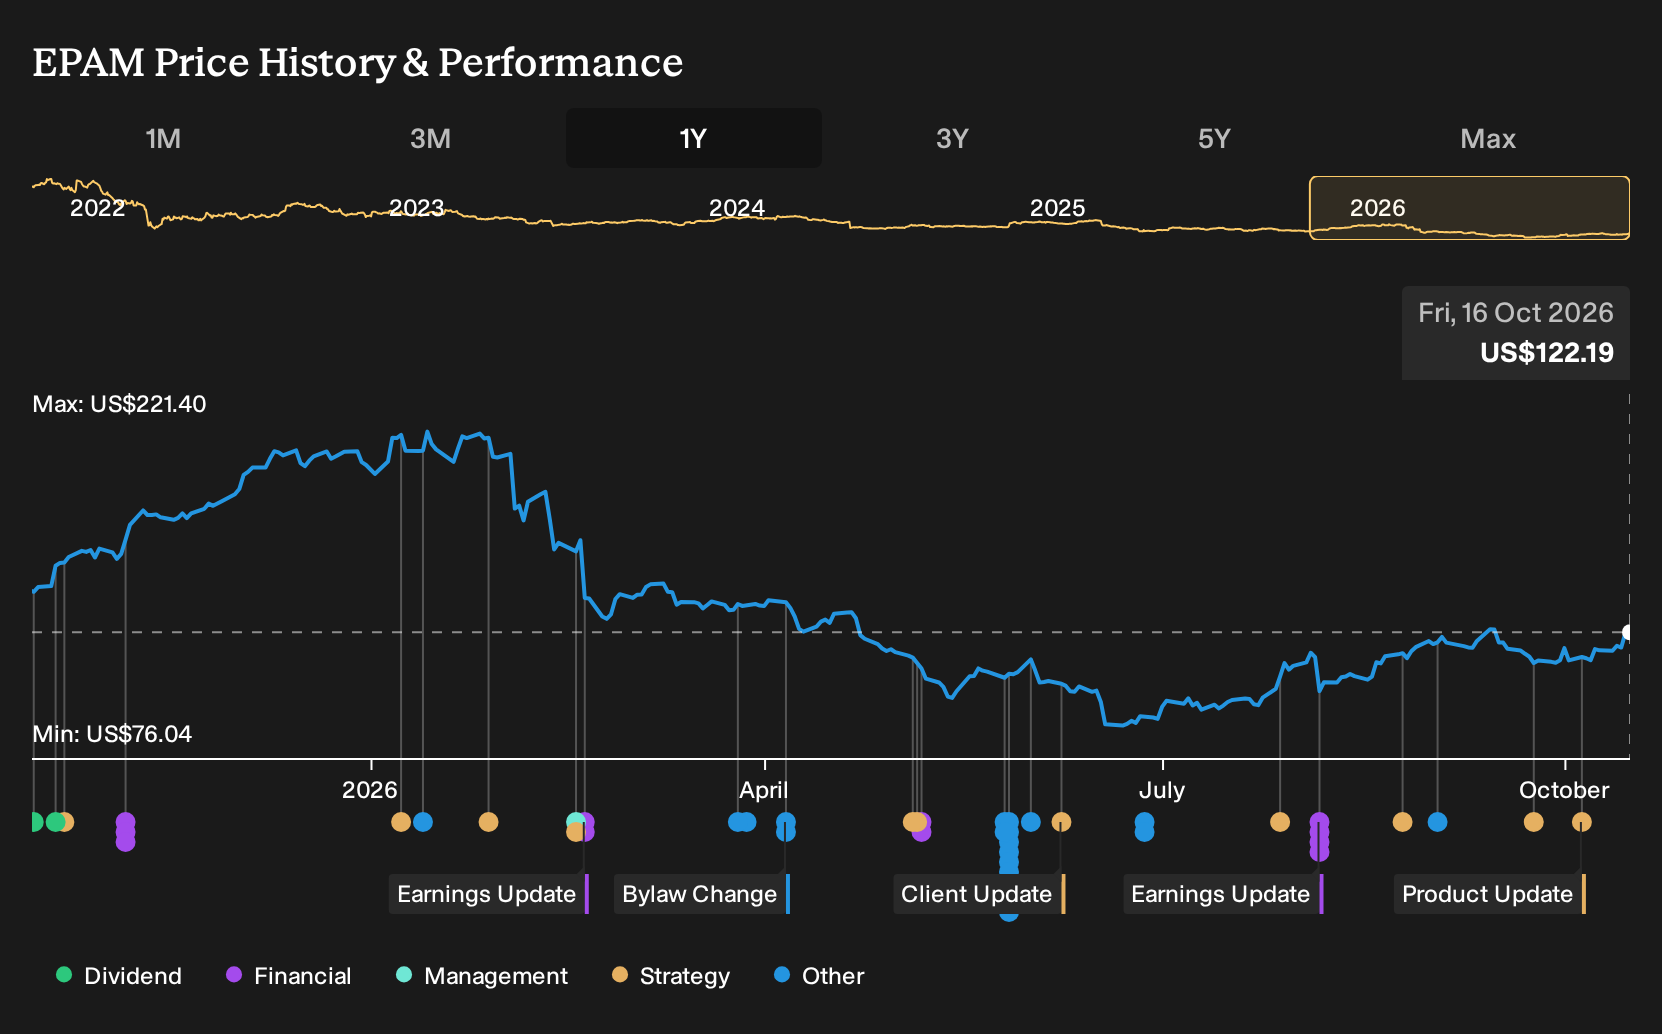
Exploring Other Perspectives
Some of the most optimistic analysts frame this new EPAM Systems AI offering as potential fuel for larger consolidation deals, since they were already penciling in 5.4% annual revenue growth and about US$603.9 million in earnings by 2029. You can treat this launch as a fresh data point and explore how those expectations might shift.
Explore 5 other EPAM Systems fair value estimates, including one that suggests as much as 88% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own judgment.
- A great starting point for your EPAM Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for EPAM Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPAM Systems' overall financial health at a glance.
Looking For More EPAM Systems Sized Ideas?
If EPAM Systems has sharpened your focus on where AI heavy workflows and solid fundamentals meet, it can help to line it up against a broader watchlist built with a consistent framework.
- For investors who want quality on sale, compare EPAM Systems against a wider field of resilient businesses trading below their estimated worth through 33 high quality undervalued stocks.
- If capital preservation sits high on your priority list, widen your research to companies that pair sturdy balance sheets with steady fundamentals using the list of solid balance sheet and fundamentals (25 results).
- When you are hunting for under followed opportunities, broaden your search to a curated pool of quieter high quality stories via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com