
Emerald Resources And 2 Australian Quality Stocks To Own
US debt interest costs now sit at about US$3b a day, which keeps pressure on global bond markets and raises the bar for anything to be considered high quality. That backdrop gives patient investors in Australian smaller companies a rare opening. While big funds stay crowded in larger stocks, some strong but overlooked businesses are quietly trading on the sidelines. This piece highlights three of the most compelling overlooked Australian stocks in that group.
The three stocks covered below are only a small sample of what fits this high quality, under the radar profile, with the full screen surfacing 12 more businesses with equally compelling stories that are not covered in this article. To see the wider field and identify your own highest conviction ideas, head straight to the High-Quality Undiscovered Gems screener
Emerald Resources (ASX:EMR)
Overview: Emerald Resources is a Perth based gold producer built around its 100% owned Okvau Gold Project in Cambodia, a near-term focused operation that fits the screener’s under-the-radar small-cap resource theme.
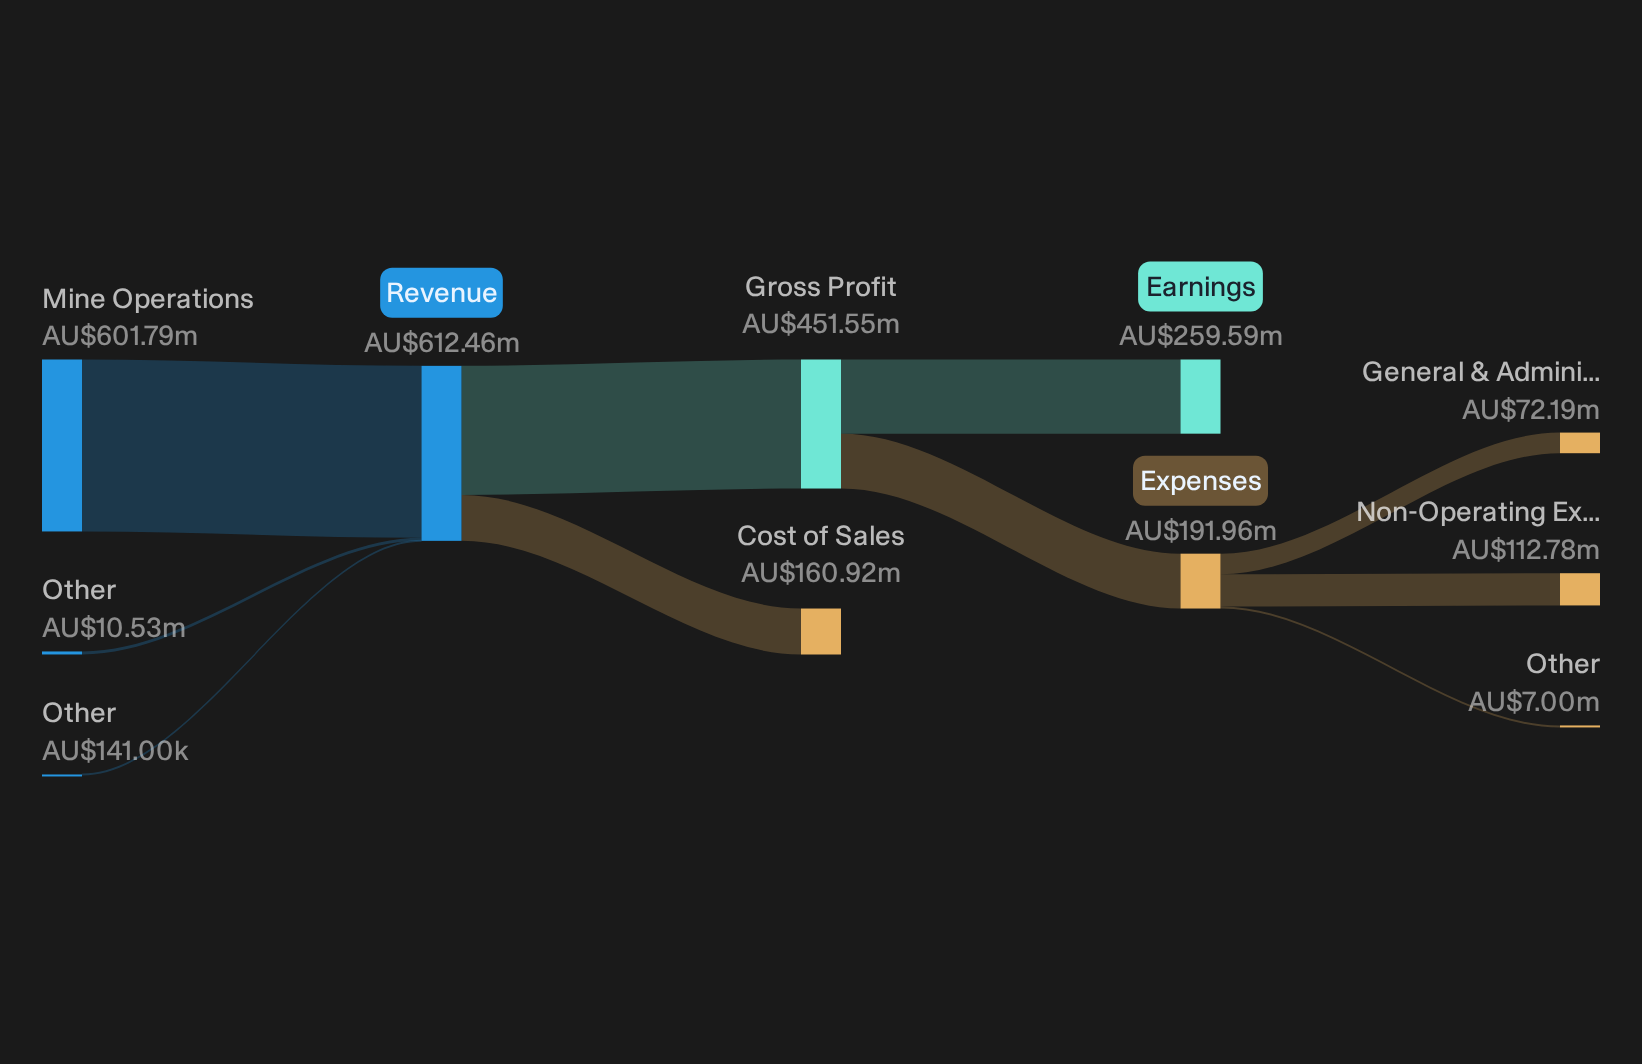
Operations: Emerald Resources generated about A$612 million from mine operations, with roughly A$609 million tied to Cambodian activities and A$3 million from Western Australia.
Market Cap: A$4.40 billion
Emerald Resources aligns with the High-Quality Undiscovered Gems theme because almost all of its income comes from the Okvau Gold Mine. Recent A$612 million in sales and A$259.59 million in net income indicate a profitable, focused producer that still sits outside most big fund portfolios. Ongoing performance will depend on how various operational and market factors ultimately affect its margins.
To see how those margin swings could affect Emerald Resources in practice, review the Emerald Resources financial health report to understand what the raw balance sheet is signaling next.
Australian Ethical Investment (ASX:AEF)
Overview: Australian Ethical Investment is a Sydney based fund manager that runs ethical mutual funds and ETFs, including active small cap strategies targeting under researched businesses with solid fundamentals.
Operations: Australian Ethical Investment generated about A$129.55 million in funds management revenue, almost entirely from clients in Australia.
Market Cap: A$475 million
Australian Ethical Investment matters for this screener because it aims to be the kind of active ethical manager that hunts for under appreciated small caps before bigger institutions arrive.
"The growing preference for ethical investment is accelerating, driven by increased public and regulatory focus on sustainability and governance, which favors managers with authentic, differentiated ESG offerings. This is expanding the addressable market and should drive continued net inflows and top-line revenue growth."
What really shapes how Australian Ethical Investment converts that tailwind into outcomes is how one quiet pressure on its profitability evolves.
This quiet pressure is exactly what full narrative for Australian Ethical Investment unpacks in detail, examining how Australian Ethical Investment might respond in ways that focus on scale as well as profitability.

EDU Holdings (ASX:EDU)
Overview: EDU Holdings runs higher education and vocational colleges focused on human services and education degrees and VET courses for domestic and international students.
Operations: EDU Holdings generated about A$100.583 million in revenue, entirely from Australian based education services across its higher education and vocational training arms.
Market Cap: A$106 million
EDU Holdings fits the High-Quality Undiscovered Gems theme as a tuition-led education provider. Ikon and Australian Learning Group quietly turn specialist courses in counselling, community services, aged care and early childhood into meaningful cash flow while larger funds focus elsewhere.
"The single biggest risk is regulatory. A minister can wake up tomorrow and decide private education providers are politically inconvenient."
What ultimately matters for EDU Holdings is whether one underappreciated regulatory shift feeds through into the enrolment funnel and long term earnings power.
That inflection point is exactly what the full narrative for EDU Holdings lays out, showing how EDU Holdings could turn regulatory risk into an accelerating advantage for its student pipeline.

Seeking Fresh Alternatives Before They Fly
Fresh ideas rarely stay under the radar for long. Breakout stories build momentum, and by the time headlines catch up, the best entry points are gone. Move while it still matters and get in early.
- Spot cash generative small caps before the crowd by running the 5 high quality undervalued stocks while prices are still dropping into attractive territory and expectations remain muted.
- Target companies reinforcing their finances as conditions shift by scanning the list of solid balance sheet and fundamentals (12 results) and focus on businesses built to keep compounding through tougher cycles.
- Ride the next leg of the AI build out by checking the 55 AI infrastructure stocks and track potential beneficiaries of rising data center and chip demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com