
Brunello Cucinelli (BIT:BC) Lifts 2026 Growth Outlook, Is The Stock Still 14% Undervalued?
Brunello Cucinelli (BIT:BC) raised its 2026 revenue growth outlook to 12% after third quarter sales slightly topped expectations, sparking a sharp rebound in the share price and reviving debate around valuation.
The raised guidance comes after a tough spell for Brunello Cucinelli, with the share price down about 10% year to date even though the 5 year total shareholder return is close to 79%. Recent momentum has turned sharply, with a 13% 1 month share price return and a 20% 3 year total shareholder return. This suggests that investors are reassessing both growth potential and perceived risk around the current €87.28 level.
Compare Brunello Cucinelli's renewed growth story with other premium businesses by scanning our hand picked 617 high quality undiscovered gems that also pair strong fundamentals with fresh investor interest.
After that sharp rebound, Brunello Cucinelli now asks a simple question of you as an investor. Step in at €87.28 after the guidance upgrade, or sit back and wait for the next opening while valuation cools.
Most Popular Narrative: 14% Undervalued
Against the current €87.28 share price, the most widely followed narrative implies a fair value of about €101.71, so the market is treating Brunello Cucinelli with a clear discount while still assigning it a premium profile within luxury.
The company is capitalizing on increasing demand for authenticity and "quiet luxury," with a firm focus on artisanal quality and exclusivity in both product and brand experience, supporting pricing power and the ability to sustain high gross margins.
Proactive expansion into underpenetrated luxury markets, notably China, the Middle East, and North America, combined with a steady pipeline of boutique openings and enlargements, is set to broaden the addressable market and drive high single-digit to low double-digit annual revenue growth.
See why 25 investors see Brunello Cucinelli as 14% undervalued.
Result: Fair Value of €101.71 (UNDERVALUED)
Still, rising net debt and faster growth in personnel and rent expenses leave Brunello Cucinelli exposed if luxury demand cools or expansion plans underperform expectations.
Find out about the key risks to this Brunello Cucinelli narrative.
Another View: Brunello Cucinelli Through The P/E Lens
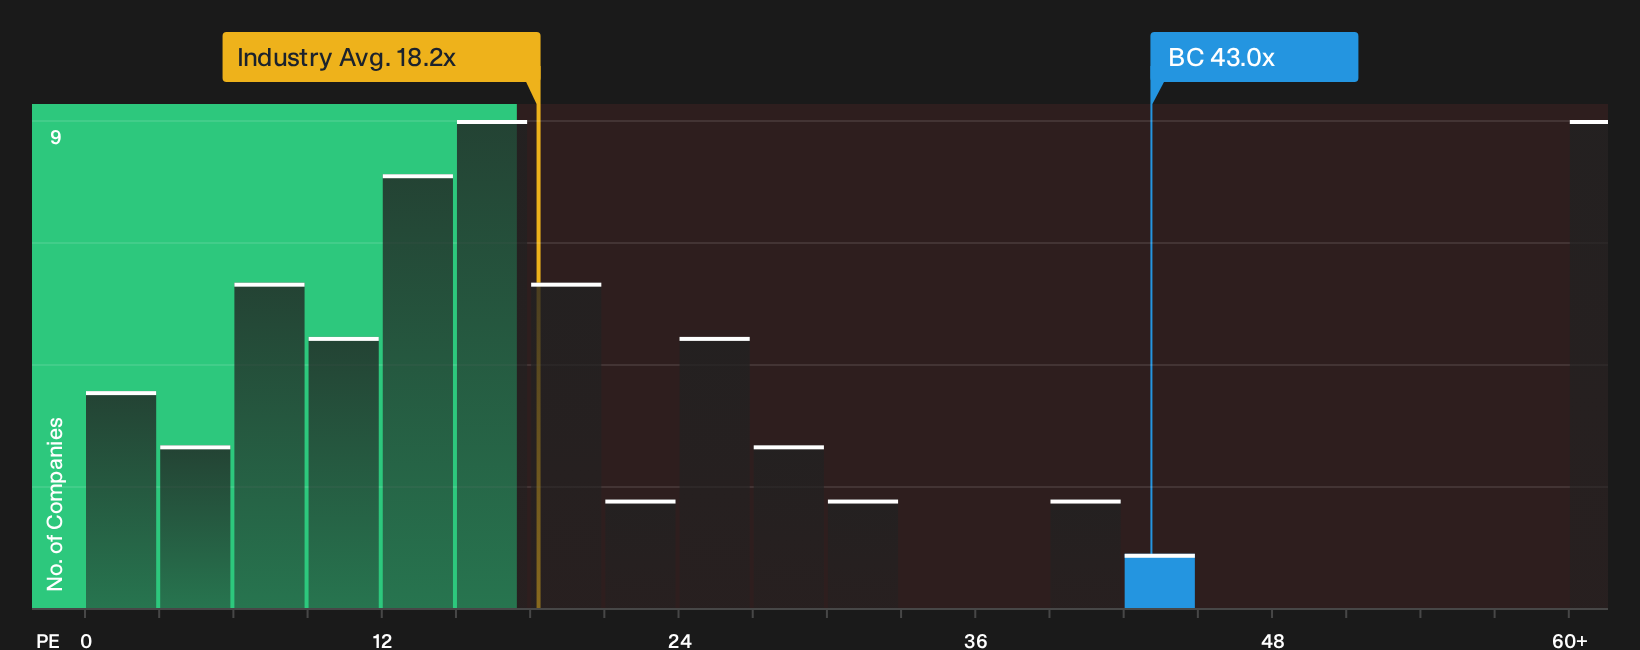
There is a catch. On a P/E of 43x, Brunello Cucinelli trades well above the European luxury group on 18.4x and also above its own fair ratio of 23.4x, which is the level the market could move toward if enthusiasm cools. That gap points to meaningful valuation risk if expectations reset.
To see what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment around Brunello Cucinelli split between premium pricing and perceived upside, use the tools at hand and pressure test the story yourself. To see what optimism is currently anchored on, take a closer look at the 2 key rewards
Looking For More Ideas Beyond Brunello Cucinelli?
If Brunello Cucinelli has caught your attention, do not stop there. Use Simply Wall Street screeners to uncover fresh opportunities before everyone else spots them.
- Target potential mispricing by scanning a focused set of 189 high quality undervalued stocks where fundamentals may not yet be fully reflected in the current share prices.
- Build staying power into your portfolio by checking a list of solid balance sheet and fundamentals (205 results) that can help you stress test resilience across different businesses.
- Reduce unpleasant surprises by filtering for 234 resilient stocks with low risk scores so you can concentrate on companies that score well on financial and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com