
First Busey (BUSE) Reaffirms Its Dividend, Is The Stock Fairly Valued?
First Busey (BUSE) just reaffirmed its income story for shareholders. On 13 October 2026, the bank declared a quarterly cash dividend of $0.26 per share, tied to an upcoming October payout.
First Busey’s latest dividend decision comes after a mixed stretch in the market, with a 1-day share price return of 0.58% and a 7-day gain of 1.73%, but a 30-day share price return that slipped 2.68% alongside a 90-day decline of 1.87%.
Even with that recent cooling, the share price performance so far in 2026 shows a 23.14% year-to-date gain. Longer term total shareholder returns of 36.28% over one year, 73.59% over three years, and 36.50% over five years point to a story where momentum has generally built over time despite shorter term pullbacks.
Scan beyond First Busey and size up other income-focused opportunities with our curated 8 dividend fortresses built for investors who want equity payouts to help replace shrinking fixed-income yields.
First Busey looks like a solid income engine, backed by steady revenue and net income growth on top of that fresh dividend call. The open question now is whether the current share price at $29.43 still offers a fair deal.
Price-to-Earnings of 11.5x: Is it justified?
On the valuation front, First Busey trades on a P/E of 11.5x at a closing price of $29.43, which puts the stock slightly above both its sector yardstick and its own internally estimated fair level.
The P/E ratio measures how much investors are paying for each dollar of earnings, which tends to matter a lot for banks where profit stability and credit quality drive sentiment. For First Busey, the combination of earnings growth over the past year and a 27.1% net margin should be front of mind when deciding whether that 11.5x earnings tag feels reasonable.
There is a split message in the data. On one side, the ticker is described as good value when stacked against a peer average P/E of 13x, so the market is not assigning a premium to those profits relative to similar U.S. banks. On the other side, that same 11.5x is described as slightly expensive compared with an estimated fair P/E of 10.5x. This points to a level the market could move towards if sentiment cools and earnings forecasts for 1.6% annual profit growth and 2.2% annual revenue growth stay modest.
Relative to the broader U.S. banks industry, the stock is only just above the 11.4x sector average. This means investors are not paying an extreme mark up for exposure to First Busey even after a year where earnings growth of 174.2% ran ahead of both its 5 year trend and the wider industry.
Explore the SWS fair ratio for First Busey.
Result: Preferred multiple of 11.5x price-to-earnings (ABOUT RIGHT)
Still, the First Busey story could be knocked off course if loan performance weakens or if higher funding costs squeeze that 27.1% net margin.
Find out about the key risks to this First Busey narrative.
Another View on First Busey’s Value
The P/E story paints First Busey as roughly fairly priced, yet the SWS DCF model points in a different direction. That cash flow lens suggests the shares at $29.43 trade well below an estimated future cash flow value of $51.09, which frames current pricing as potentially conservative.
For readers who want to see how that cash flow view is built step by step, Look into how the SWS DCF model arrives at its fair value.
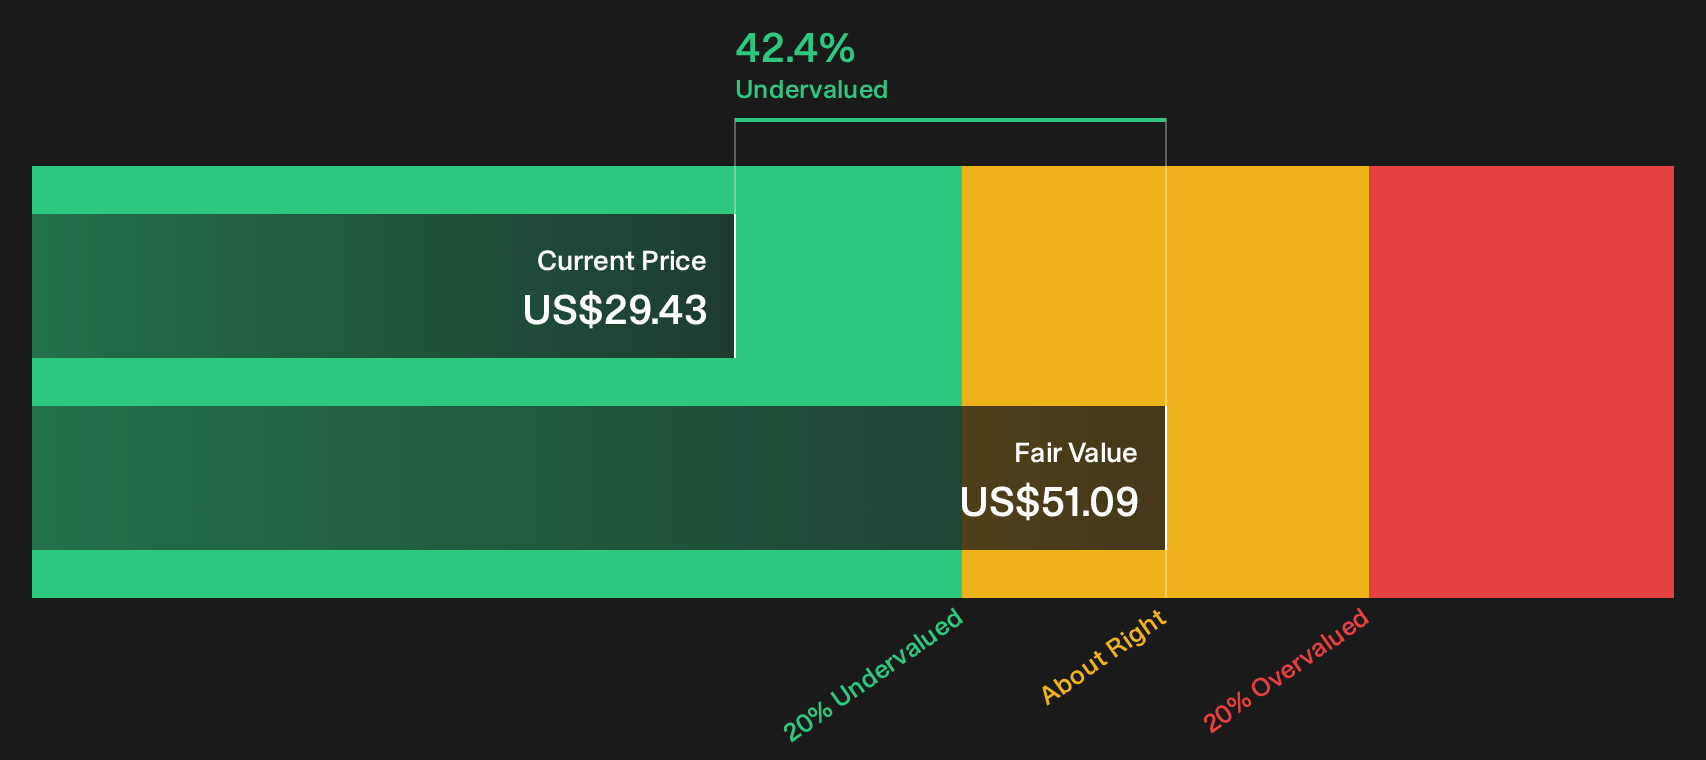
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Busey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The tone of this First Busey story appears cautiously optimistic around income and value. Review the full breakdown of potential upsides and decide whether those strengths align with your own checklist by checking the 3 key rewards.
Looking for more investment ideas beyond First Busey?
If you stop at First Busey, you could miss other opportunities that fit your goals even better, so give yourself options and scan wider.
- Target reliable cash flow by focusing on companies with strong payouts using the 8 dividend fortresses.
- Hunt for mispriced quality by filtering for strong businesses trading below what their fundamentals suggest through the 33 high quality undervalued stocks.
- Prioritize capital protection by zeroing in on companies with sturdier profiles via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com