
How Investors Are Reacting To FLSmidth (CPSE:FLS) Major Mining Orders
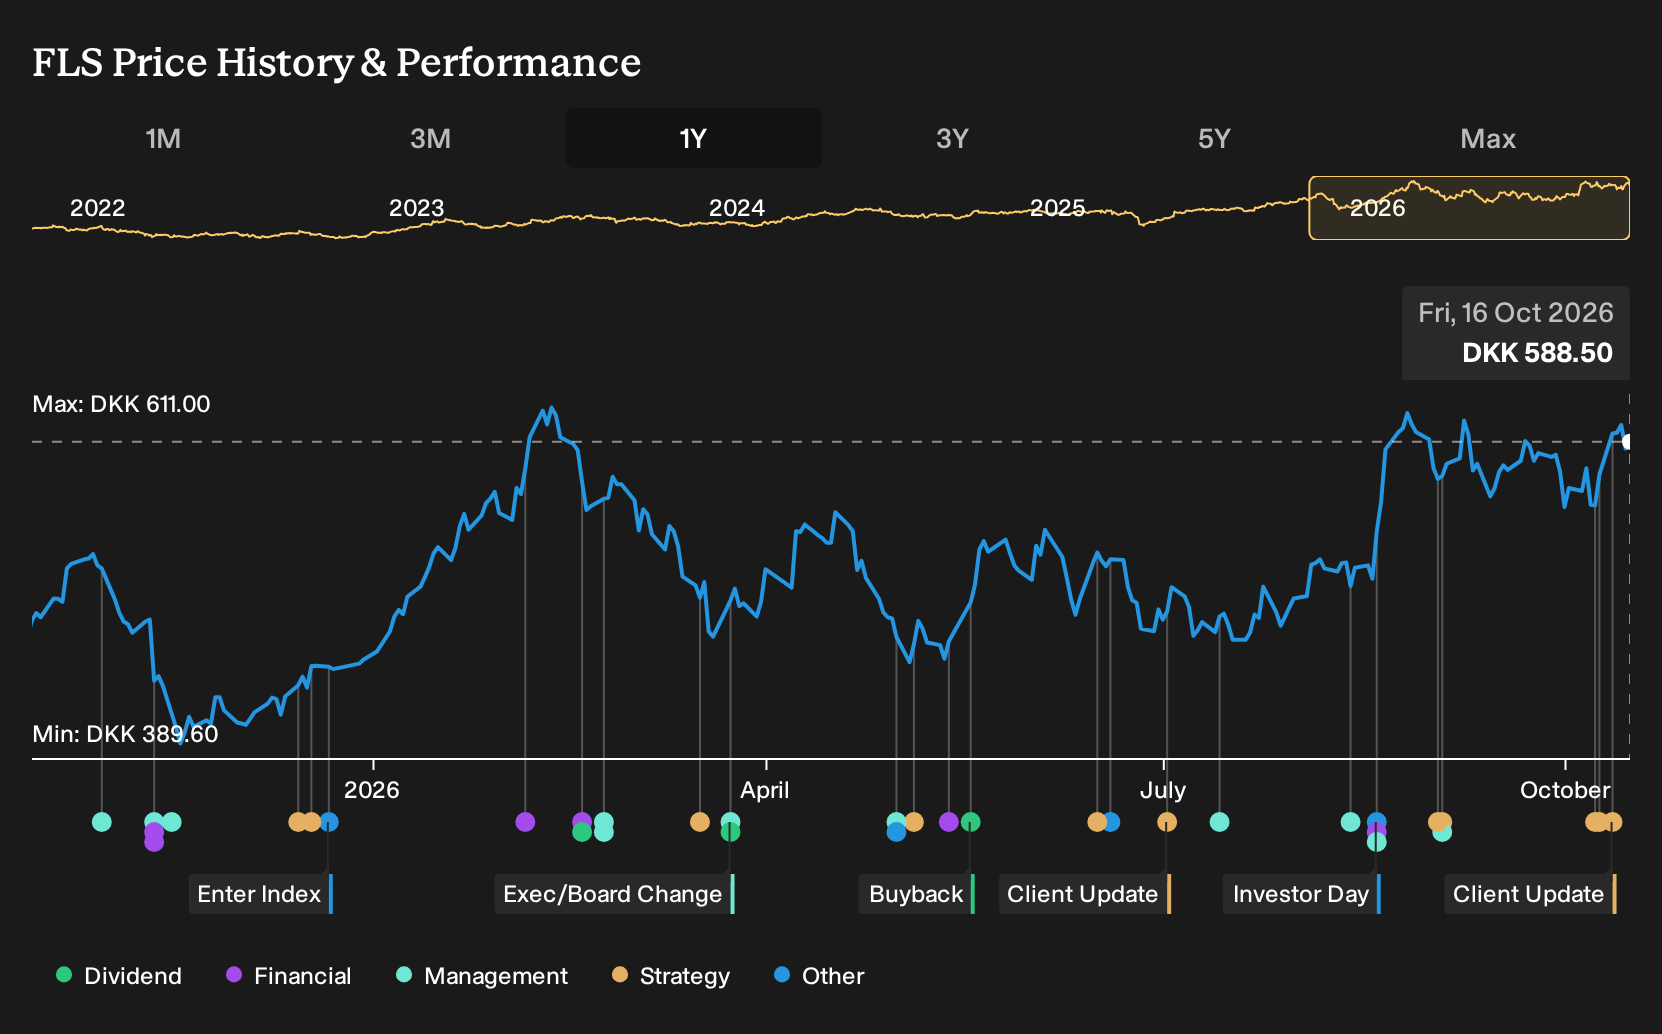
- FLSmidth disclosed several large mining equipment orders in October 2026, including a DKK 360 million crushing and grinding package in Northern Chile, a DKK 175 million grinding line in Chile, and a DKK 225 million mill technologies contract for a gold project in North America. All were booked in the third quarter and left 2026 guidance unchanged.
- The clustering of high value copper and gold contracts, all featuring FLSmidth’s mill and crusher technologies plus long term service and spares, highlights how the mining segment depends on the group’s process expertise and installed base to secure follow on work across multiple projects and regions.
- We will now look at how these sizeable mining equipment wins, especially the Chilean copper expansions, could influence FLSmidth's investment narrative.
Scan beyond FLSmidth and see which peers could be lining up similar contract momentum by running our curated list of 41 power grid technology and infrastructure stocks across your watchlist ideas.
What Is FLSmidth's Investment Narrative?
To own FLSmidth you need to buy into a fairly straightforward idea. This is an equipment and service specialist that wins by securing long lead, capital intensive mining projects, then staying close to those sites for years through spares, upgrades and on site support. Recent copper and gold orders in Chile and North America fit that script. They add visible workload into 2027 to 2030 without changing 2026 guidance, so they look more like reinforcement of the pipeline than a near term earnings swing.
In the short term, the real swing factors remain tied to execution on the current backlog, pricing discipline on complex mill and crusher packages, and how capital spending plans from miners translate into new bids. FLSmidth is growing earnings, trades on a P/E around 20x and screens as good value versus some machinery peers, but reported profit has been influenced by large one off items. That combination of contract wins, capital intensity and accounting noise means investors still have to watch how cash conversion tracks the story.
Even so, one issue around how FLSmidth funds and manages that heavy project load can easily be missed until you look closely at...
There's only one way to know the right time to buy, sell or hold FLSmidth. Head to Simply Wall St's company report for the latest analysis of FLSmidth's Fair Value.
Exploring Other Perspectives
Some analysts see a very different risk for FLSmidth. You might worry that copper project approvals stay slow, which is exactly what the most cautious forecasters assume. They were pencilling in DKK 17.4b of revenue and DKK 1.9b of earnings by 2029, so their slower buildout story could shift as these new orders sink in.
Explore 2 other FLSmidth fair value estimates, including one that suggests it could be worth just DKK 660.42.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your FLSmidth research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FLSmidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FLSmidth's overall financial health at a glance.
Looking For More Ideas Beyond FLSmidth?
If you want to stress test your thesis on FLSmidth and broaden your opportunity set at the same time, a quick pass through the Simply Wall St Screener can surface other stocks that match the kind of risk and quality profile you prefer.
- For investors who care most about resilient balance sheets and fundamentals, filter potential candidates with a curated list of solid balance sheet and fundamentals (205 results) to see which listings share that financial strength profile.
- If you are hunting for companies that combine quality with the potential for mispricing, scan through our hand picked 191 high quality undervalued stocks to compare against what you see in FLSmidth.
- Those looking for under the radar stories with sound financial traits can run a focused search using a 617 high quality undiscovered gems and build a watchlist that goes well beyond the usual tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com