
3 AI Infrastructure Stocks With Real Exposure To Data Center Spending
AI data center buildouts have become the latest front in the fight over inflation, with massive hardware spending colliding with a Federal Reserve that is openly worried about an overheating cycle. That clash creates a live test for which businesses actually earn durable cash flows from this rush, and which just ride the hype. This article walks through three stocks directly exposed to that story and how the current backdrop might help or hurt each one.
The stocks discussed below are only a small sample of the idea, and the full screen surfaced 68 more companies with equally detailed AI data center and semiconductor infrastructure stories that do not fit into a single article. To go straight to the source and identify your own highest conviction candidates, analyze the AI Data Center & Semiconductor Infrastructure Leaders screener.
FormFactor (FORM)
Overview: FormFactor builds probe cards and test systems that help chip makers qualify advanced AI, GPU, and data center semiconductors before deployment.
Operations: FormFactor generates about US$747 million from Probe Cards and US$155 million from Systems, with revenue concentrated in South Korea and Taiwan.
Market Cap: US$8.9b
FormFactor matters for this AI data center screen because every cutting edge GPU, HBM stack, and custom accelerator depends on reliable testing before it ever hits a server rack.
"Accelerating adoption of generative AI, high performance computing, and HBM DRAM in data centers is continuing to raise test complexity and intensity, and FormFactor’s HBM probe card revenue guidance for the first half of 2026 sits more than 50% above the first half of 2025."
What happens to FormFactor’s margins and cash generation if a single key assumption about future test intensity in AI hardware shifts?
That hinges on more than one test cycle or pricing tweak, and the full narrative for FormFactor shows how FormFactor’s AI demand story could accelerate or quietly stall.

ASE Technology Holding (TWSE:3711)
Overview: ASE Technology Holding provides semiconductor packaging, testing, and electronic manufacturing services that help scale AI and data center chips from fabs into finished systems.
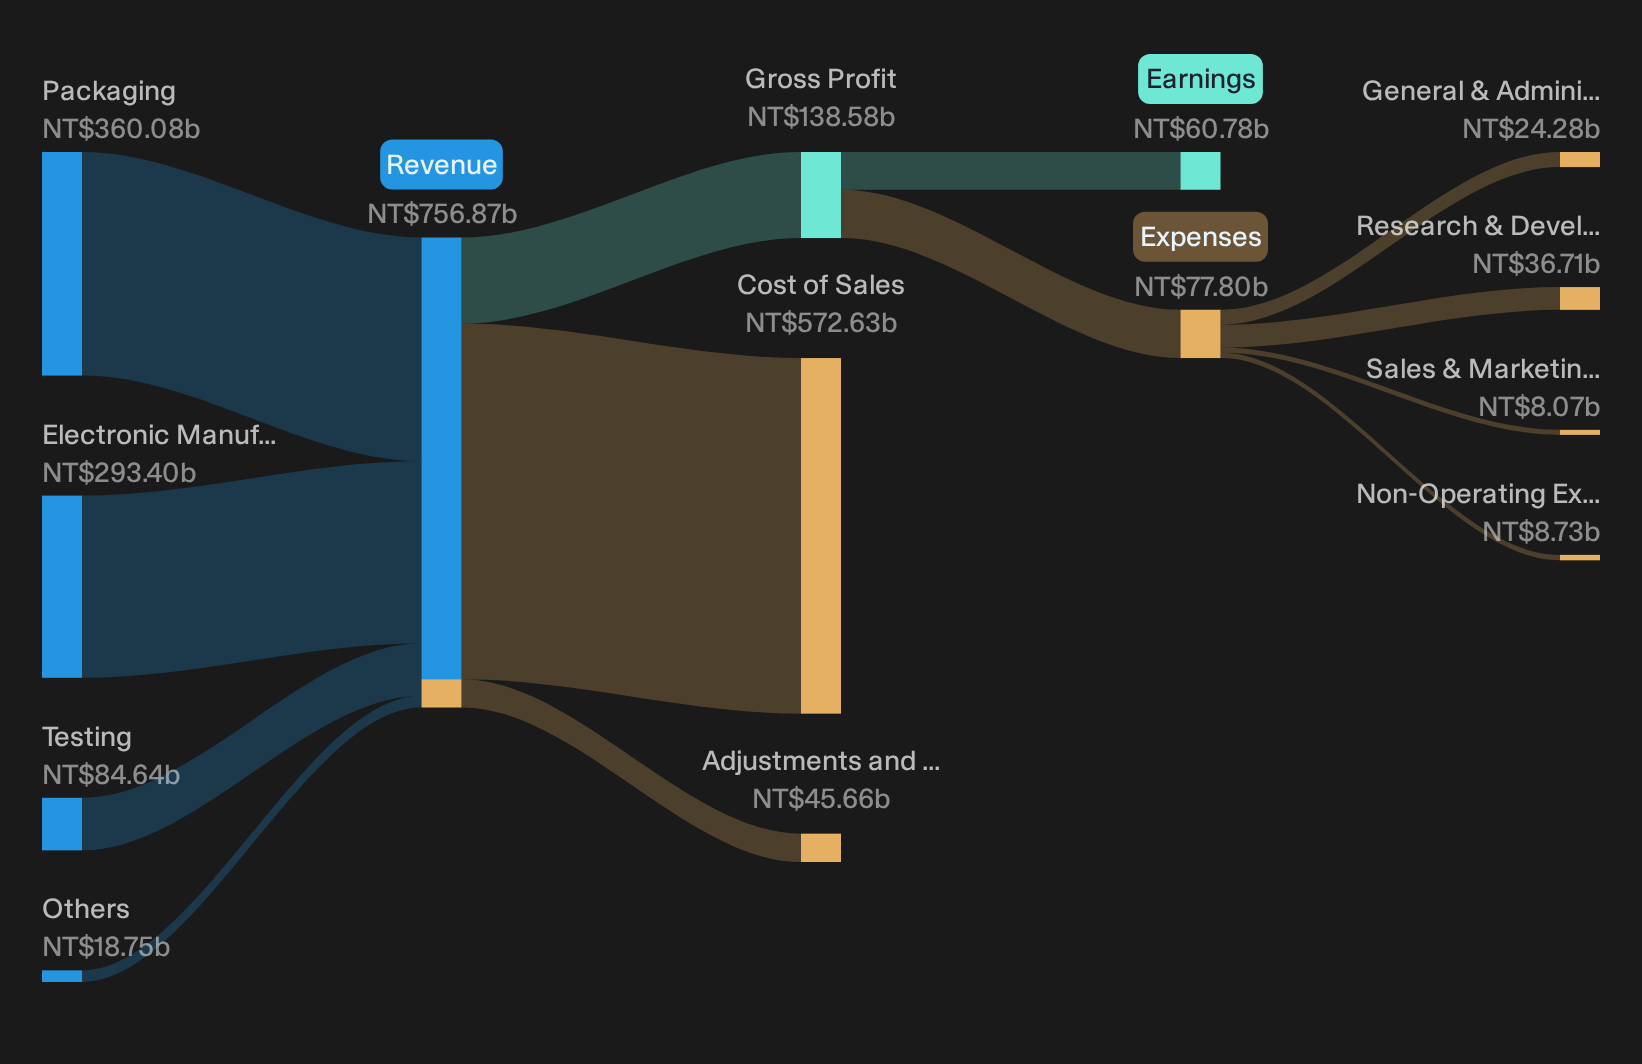
Operations: ASE Technology Holding generates around NT$360.1b from Packaging, NT$84.6b from Testing, and NT$293.4b from EMS, with smaller contributions elsewhere.
Market Cap: NT$2.95t
ASE Technology Holding matters for this AI data center screen because its assembly and test lines sit directly behind the surge in accelerator and server silicon coming out of the big foundries.
"ASE Technology Holding is benefiting from strong demand for AI related advanced packaging and testing, with LEAP services revenue expected to exceed US$3.5b in 2026 and management aiming to double LEAP revenue again in 2027. If installed capacity starts to run ahead of AI related demand, utilization could slip, which would put pressure on gross margin and asset returns."
What investors really have to watch now is how one pressure point in this build out shapes the balance between high growth and healthy returns.
If that balance between capacity and returns is what you care about, read the full narrative for ASE Technology Holding to see how ASE Technology Holding could still surprise optimists.
Camtek (CAMT)
Overview: Camtek supplies inspection and metrology systems that help AI focused semiconductor fabs and packagers qualify advanced chips and packaging steps.
Market Cap: US$6.1b
Camtek matters for this AI data center list because every HBM stack and chiplet package relies on precise inspection before it moves into high performance compute racks.
"Although Camtek is securing large orders tied to AI related advanced packaging through 2027, its non advanced packaging businesses such as CMOS image sensors and other 2D inspection tools are described as only stable with small growth, which could cap overall revenue expansion once the current AI and HBM cycle normalises and dilute earnings leverage."
What really shapes Camtek’s upside is how one quiet shift in future AI focused capex ripples through tool demand and pricing power.
That quiet shift in Camtek’s AI capex exposure is exactly what the full narrative for Camtek unpacks, including how inspection demand could keep accelerating beyond today’s headline orders.

Seeking Alternatives Before The Crowd
Fresh opportunities do not stay quiet for long. Breakout stories gain momentum, latecomers get caught chasing, and under the radar for now ideas drop off fast, so consider acting before attention builds.
- Spot resilient cash generators with strong balance sheets before they start gaining wider notice by scanning the curated list of solid balance sheet and fundamentals (25 results) that screens for financial strength and disciplined fundamentals.
- Look at early momentum in targeted AI leaders by reviewing the hand picked 38 profitable AI stocks that aren't just burning cash that filters for real earnings power instead of cash burning stories.
- Track potential metal supply pressures by reviewing the focused 17 top copper producer stocks that highlights producers with meaningful exposure to copper demand trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com