
Beam Therapeutics (BEAM) After BEAM 302 Data And Probe Is The Undervaluation Case Broken
Beam Therapeutics (BEAM) is under legal scrutiny after Pomerantz LLP opened an investigation into potential securities law violations, following updated BEAM-302 clinical data that coincided with a 9.54% share price drop.
That legal overhang lands on top of a weak tape for Beam Therapeutics, with the share price down 5.1% on the day, 8.7% over the past week and 14.8% across three months, even though the 3 year total shareholder return is up 32.7% and the 5 year total shareholder return is down 75.0%. This points to fading near term momentum after an earlier recovery as investors reprice both clinical opportunity and legal risk around BEAM-302 at a current share price of US$23.47.
Broaden your watchlist beyond Beam Therapeutics by scanning 32 resilient stocks with low risk scores that may hold up better when single-stock headlines trigger sharp moves.
The sharp swing in Beam Therapeutics now forces a simple question for investors: Did the latest slide expose something fundamental in the business, or did sentiment overshoot on legal and clinical risk, and how does that stack up against the current valuation?
Most Popular Narrative: 54% Undervalued
On the most followed narrative, Beam Therapeutics screens as materially cheaper than its modelled fair value of $51.07, compared with a last close of $23.47. This puts the legal headlines up against a story built around pipeline progress and long term potential.
The development of ESCAPE technology aims to expand the addressable patient population for gene editing by eliminating chemotherapy, which could significantly increase the market and, subsequently, revenue and margins. Beam has nominated BEAM-103 and BEAM-104 for their ESCAPE program, which could bring transformative changes in transplant medicine by enabling non-genotoxic conditioning, leading to broader patient access and a potential increase in revenue.
See why 60 investors see Beam Therapeutics as 54% undervalued.
Result: Fair Value of $51.07 (UNDERVALUED)
Still, that story can break if safety setbacks in conditioning regimens or slower than expected trial progress for BEAM-302 and risto cel dent confidence in Beam Therapeutics.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: Beam Therapeutics Looks Expensive On Sales
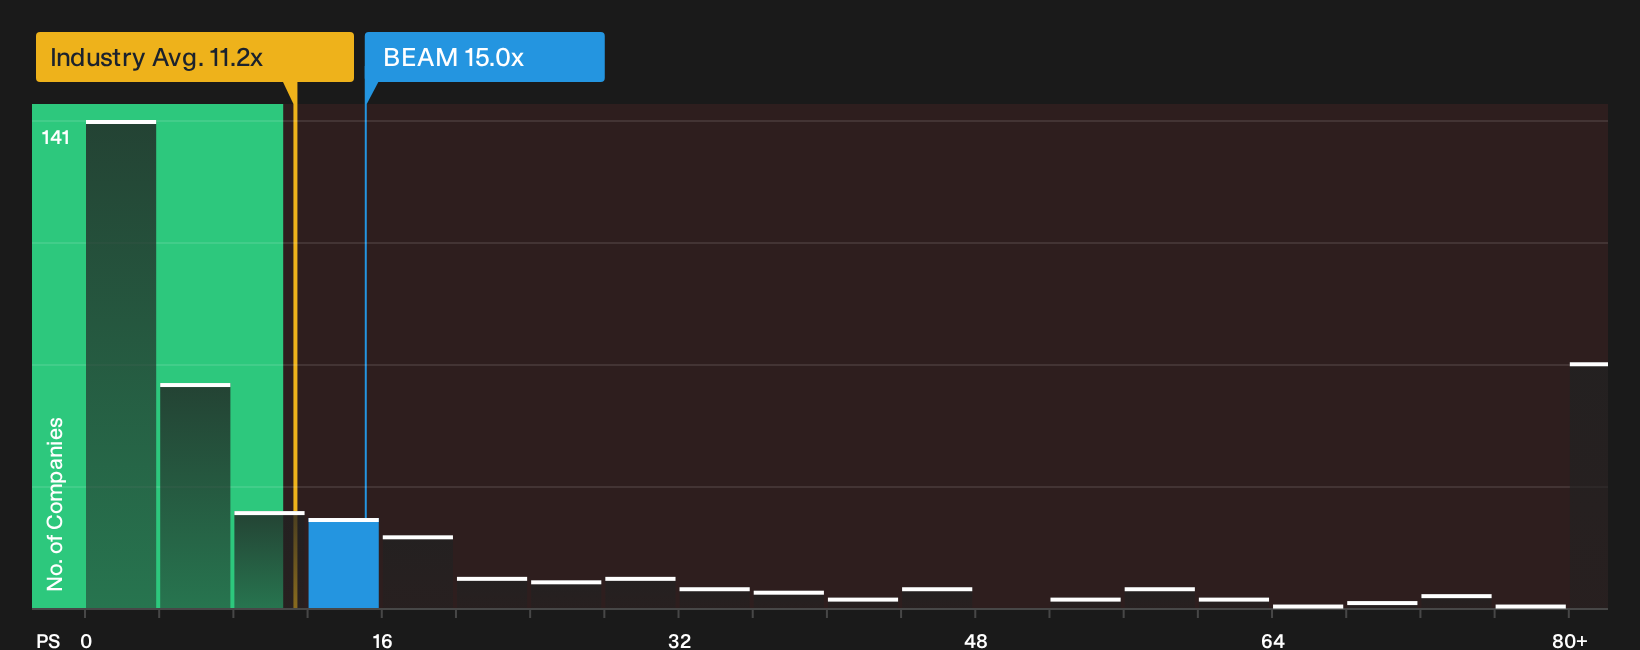
That 54% upside story for Beam Therapeutics meets a very different message once P/S is brought into the frame. At roughly 15x sales, the stock sits above the US Biotechs industry at 11.1x and above peers at 12.2x, while the fair ratio sits far lower at 0.8x. If the market leans back toward that fair ratio instead of the growth narrative, how much valuation risk are you really comfortable holding?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Beam Therapeutics can feel hard to read, so move quickly and test the numbers, sentiment and legal overhang yourself. To weigh that mix of caution and optimism directly, start with the 2 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Beam Therapeutics?
Do not stop your research with Beam Therapeutics. Broader context often reveals better risk and reward trade offs, and a few focused stock lists can sharpen your next move.
- Target potential mispricing by scanning companies flagged as 33 high quality undervalued stocks that combine quality fundamentals with appealing price tags.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks when headlines hit.
- Hunt for off-the-radar opportunities by checking out 20 high quality undiscovered gems poised to reward investors who do the work early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com