
MercadoLibre (MELI) Could Be 43% Below Fair Value Before Earnings
MercadoLibre (MELI) recently lagged the broader market, with its stock slipping 1.16% ahead of an earnings release that has traders focused on projected changes in revenue and earnings per share.
The pullback over the past week, with a 7 day share price return of down 2.96%, comes on top of a year to date decline of 7.08% and a 1 year total shareholder return of down 9.43%. However, longer horizons remain stronger, with 3 and 5 year total shareholder returns of 56.80% and 21.96% respectively.
Spot opportunities with similar e-commerce and fintech stories by scanning our curated list of 20 high quality undiscovered gems before MercadoLibre's next earnings reset expectations.After a sharp run over three and five years but a weaker recent tape, the real debate on MercadoLibre is simple. Is most of the return already in the rear-view mirror, or does today’s price still leave meaningful upside?
Most Popular Narrative: 43% Undervalued
On Simply Wall St, the most followed narrative pegs MercadoLibre’s fair value at $3,219, against a last close of $1,834. That gap is large enough that the whole debate turns on how you treat its lending engine and the cash it consumes.
Here is the part that should make you smarter about valuation generally, not just about this one stock. The exact same business, run through two defensible cash flow models, produces two wildly different verdicts. Neither model is dishonest. They just disagree about what "cash flow" means.
See why 151 investors see MercadoLibre as 43% undervalued.
Result: Fair Value of $3,219 (UNDERVALUED)
Still, MercadoLibre’s story can be knocked off course if credit quality worsens and the capital needed to fund Mercado Credito continues to pressure free cash flow.
Find out about the key risks to this MercadoLibre narrative.
Another View: MercadoLibre Through The P/E Lens
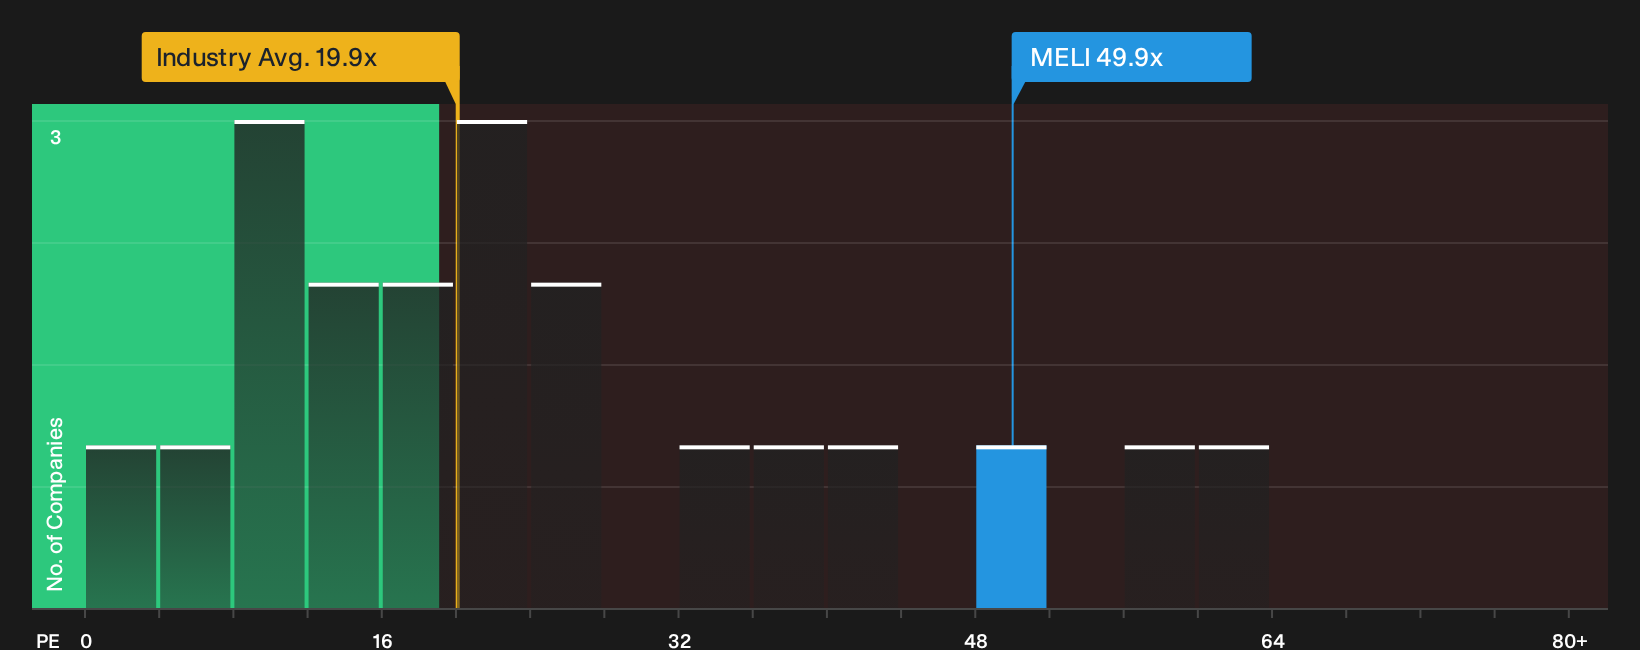
The story looks very different once you set the cash flow models aside and instead ask what investors are paying for each dollar of MercadoLibre earnings. On this measure, the stock is not cheap.
MercadoLibre trades on a P/E of 49.9x, compared with 21.1x for peers and 19.9x for the wider Global Multiline Retail group. The fair ratio is 32.6x. That gap points to valuation risk if sentiment cools, even if long term forecasts play out as expected.
Numbers rarely agree perfectly. The question for you is whether to rely more on the richer P/E signal or place greater weight on the cash flow work instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on MercadoLibre valuation and sentiment do not have to paralyze you. Move quickly to test the numbers yourself and weigh both the upside case and the weak spots, starting with 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond MercadoLibre?
If MercadoLibre has your attention, do not stop there. Use the Simply Wall St screener to surface other opportunities that might fit your style before they move first.
- Target steadier potential by focusing on companies that combine earnings strength with discounted valuations through the 33 high quality undervalued stocks.
- Secure income-focused ideas by filtering for firms offering higher yields and resilient payout histories using the 8 dividend fortresses.
- Reduce portfolio stress by concentrating on businesses with healthier balance sheets and consistent fundamentals found via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com