
The Bet Behind Bombardier's Rally
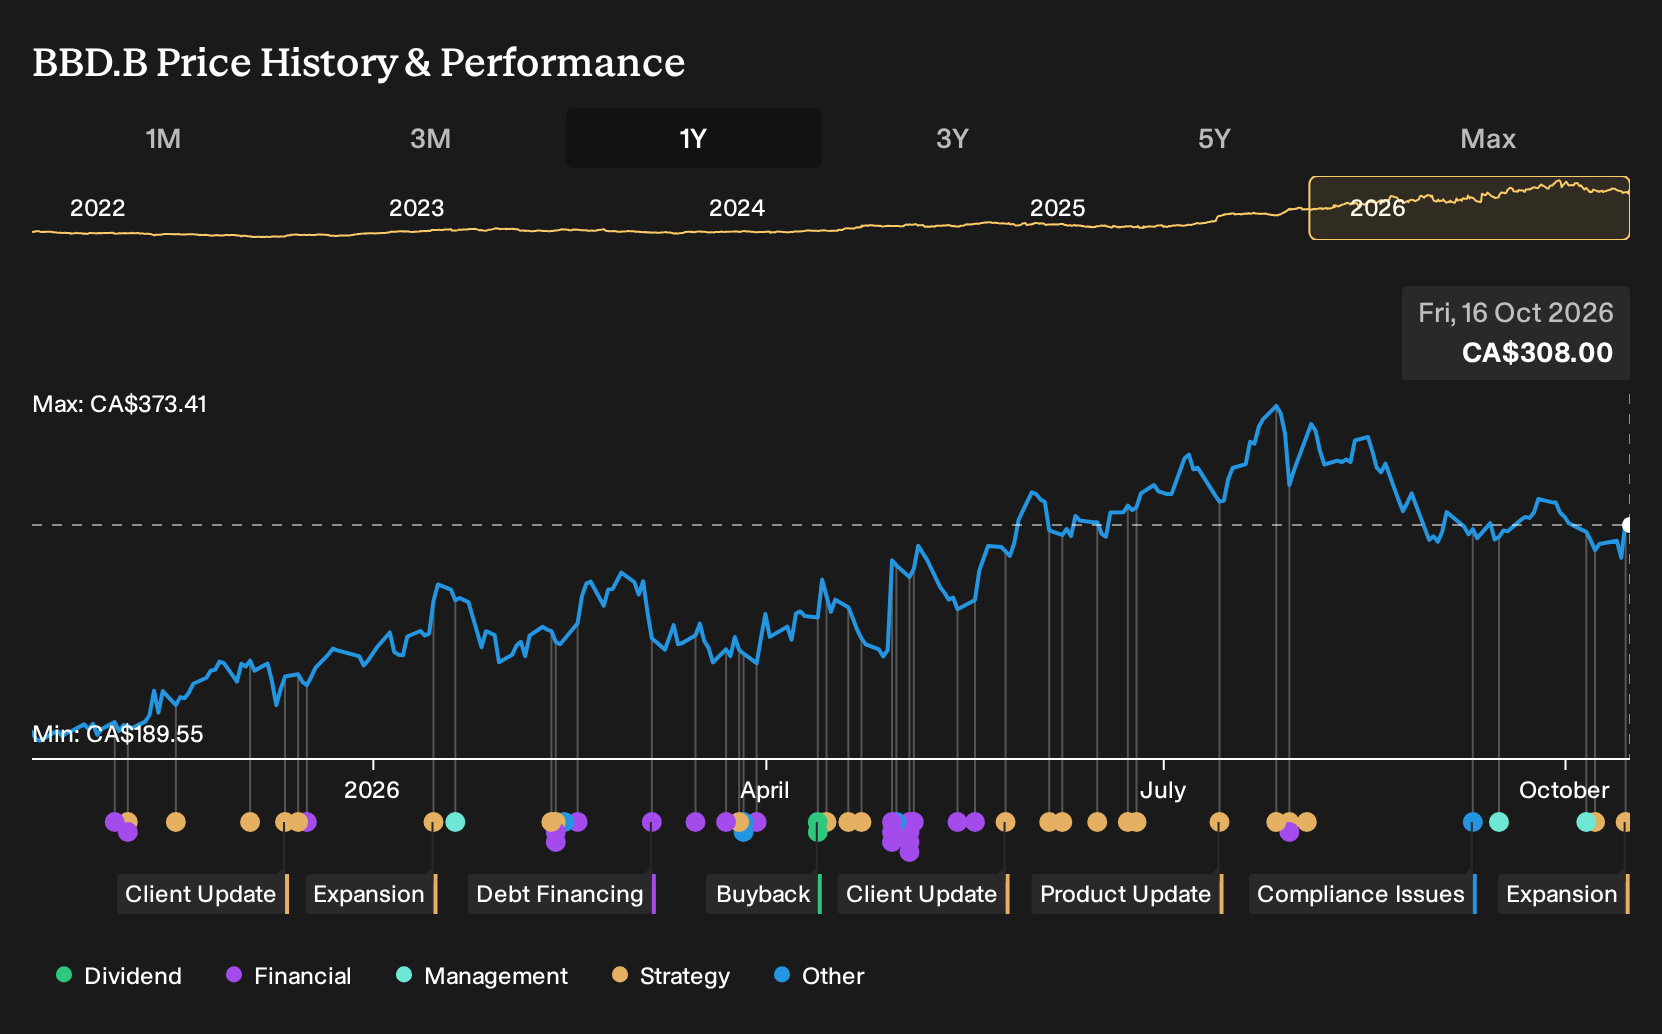
If you were watching Bombardier this year, the announcement that The Helicopter Company signed an LOI for up to 60 jets was the sort of concrete contract that sharpened attention on its order book. Investors who held Bombardier over the past year are up 62.5%, including dividends. If that outcome was on your radar back on 16 October 2025, what did you need to believe about future demand and trade risks before any of this news arrived?
Bombardier has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Bombardier
At that point the shares cost CA$190, so any view on Bombardier boiled down to which story about its future business you trusted more.
The bullish narrative saw a Fair Value of CA$201, a price implied by a belief that growing global wealth, green trends and expansion in higher margin service and defense work could support faster revenue growth and rising profit margins, helped by investments in sustainability focused technology.
The bearish view pointed to a Fair Value of CA$120, based on concern that heavier environmental regulation and tighter global monetary policy could restrict private jet usage and shrink the addressable market for new aircraft.
What The Bombardier Results Actually Tested
The biggest new data point was Bombardier lifting 2026 free cash flow guidance above US$1b after a strong first quarter and a backlog above US$20b, which leaned toward the bullish service and defense story. Later Q2 2026 figures showed revenue at US$2,150m and net income at US$184m, with net margin slipping from 9.2% to 8.6%. Together, the evidence cut both ways.
The clear hinge here was cash and backlog quality versus profitability. When you assess another aerospace stock, track whether rising order books and free cash flow are matched by stable or improving net margins, rather than assuming one automatically supports the other.
What Bombardier’s Run Already Prices In
Bombardier now trades at CA$308 after a 62.5% gain over the past year, while the selected Narrative’s Fair Value sits below the current price based on its own assumptions.
The Narrative centers on whether backlogs, services and defense work can keep supporting strong cash generation despite trade frictions and supply strain. A buyer today has to judge that cross border access and supply capacity remain sufficient for that cash story to continue.
"Current valuation suggests Bombardier shares already reflect a scenario where the company sustains solid cash generation, maintains a reduced debt load, and continues to fund growth and potential future shareholder returns without major setbacks."
One Narrative disagrees with today's price. → See where this Narrative says Bombardier should trade
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 44% below our estimate - accelerates higher grade ore feed and advances new underground deposits to extend reserves.
- Company 2 - 46% below our estimate - ramps advanced networking and AI hardware programs for hyperscalers while shifting toward richer services.
- Company 3 - 23% below our estimate - uses a high margin mine to fund drilling that aims to turn intercepts into reserves.
Three companies from the same screener. Open all 8 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com