
BancFirst (BANF) Is Getting Attention Today, What Is Behind It?
Why BancFirst Is On Watch Today
BancFirst (BANF) has drawn fresh attention after a recent move in its share price, with the stock last closing at US$109.03. That shift gives investors a new reference point for assessing valuation and recent performance.
The recent 0.81% 1-day share price return and 2.68% 7-day move suggest short-term momentum is picking up for BancFirst, even though the 90-day share price return is down 6.12% and the 1-year total shareholder return has slipped 1.66% against much stronger 3-year and 5-year total gains.
Scan how BancFirst stacks up against other resilient regional lenders by running the hand picked list of solid balance sheet and fundamentals (25 results) while this price action is front of mind.
Bulls point to BancFirst’s long record of positive multi year returns and its recent revenue and net income growth. Bears note a flat 1 year performance and a pullback over the past 90 days. Which case does today’s price appear to support?
Most Popular Narrative: 12.3% Undervalued
The most followed valuation narrative for BancFirst points to a fair value of about $124 per share, compared with the latest close at $109.03. That gap is based on specific business drivers rather than just a simple comparison of recent returns.
Continued consolidation in the Tulsa market through the completed American Bank of Oklahoma integration and the planned Spirit BankCorp acquisition increases BancFirst’s branch footprint, loans and deposits in a key metropolitan area. This can support higher revenue and earnings if those assets are deployed efficiently.
See why 1 investors see BancFirst as 12% undervalued.
Result: Fair Value of $124.33 (UNDERVALUED)
Still, the BancFirst story can weaken quickly if revenue growth continues to be described as mediocre and efficiency drifts, or if its premium P/E multiple compresses sharply.
Find out about the key risks to this BancFirst narrative.
Another View On BancFirst’s Valuation
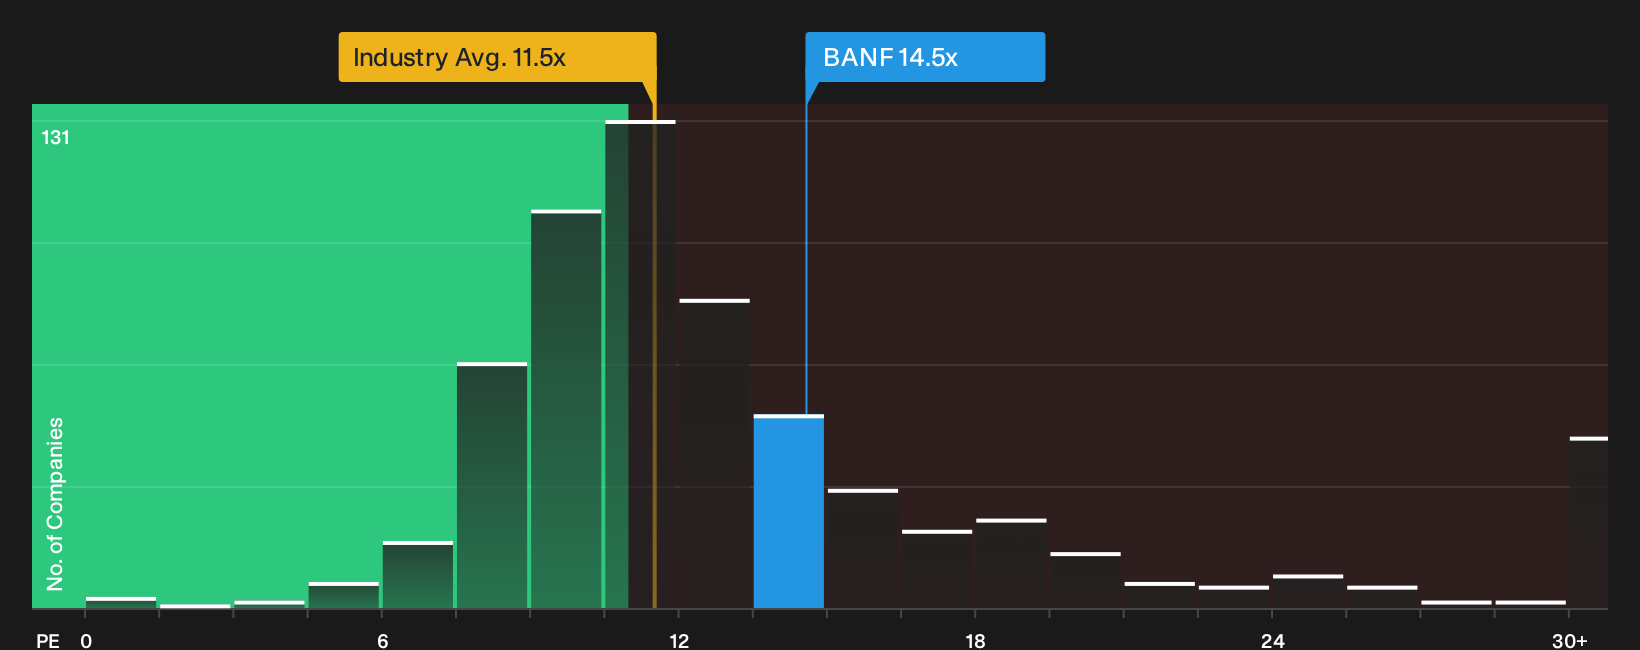
On price multiples, BancFirst looks far less generous than the 12.3% discount implied by the fair value estimate. The stock trades on a P/E of 14.5x, compared with 11.4x for the US Banks industry, 13x for peers, and an estimated fair ratio of 11.3x, which points to valuation risk if sentiment cools.
For an investor, that gap means the share price already embeds a quality premium, so any slip in earnings or returns could drag the multiple closer to the fair ratio and compress returns in the process. The question is whether you believe BancFirst’s track record is strong enough to keep that premium in place.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on BancFirst so far leaves you undecided, take that as a signal to act promptly and evaluate the evidence for yourself using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BancFirst?
Do not let your BancFirst research be the end of your work. Treat it as a starting point and widen your opportunity set while this mindset is fresh.
- Target potential mispricings by scanning a curated set of quality companies through the 33 high quality undervalued stocks.
- Prioritize resilience by reviewing a 32 resilient stocks with low risk scores that can help you focus on steadier return profiles.
- Hunt for future leaders by checking a 20 high quality undiscovered gems that may not yet be on most investors' radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com