
10x Genomics (TXG) Expands Fred Hutch Cancer Work, Is The Valuation Case Still Convincing?
10x Genomics (TXG) is back in focus after a new multi project research tie up with Fred Hutchinson Cancer Center, linking its single cell platforms more directly to potential cancer diagnostic use.
Recent trading tells a contrasting story. The share price has slid 13.4% over the past week and 9.2% over the last month, even after a 59.7% 90 day share price return and a very large 1 year total shareholder return, as investors weigh 10x Genomics’ clinical progress against concerns about revenue trends and the risks tied to past growth efforts.
Spot opportunities across oncology-focused tools by scanning the hand picked 33 healthcare AI stocks, which, like 10x Genomics, tie advanced data-driven platforms to real clinical research use cases.Bulls point to 10x Genomics’ fresh Fred Hutch tie up and recent 90 day surge, while bears focus on revenue worries and past losses. Which side does the current valuation actually support next?
Most Popular Narrative: 7.7% Undervalued
The most followed valuation storyline for 10x Genomics puts fair value at about $75.67, a touch above the last close at $69.86. That gap frames a debate where product momentum and AI related demand need to carry a lot of weight in the long term model.
The acquisition of Scale Biosciences broadens 10x Genomics' technical capabilities in single-cell analysis, allowing integration of foundational innovations like combinatorial indexing and quantum barcoding, which may accelerate innovation, reduce costs, and open up new high-value markets, positively impacting future revenue growth and margins.
See why 27 investors see 10x Genomics as 8% undervalued.
Result: Fair Value of $75.67 (UNDERVALUED)
Still, the story around 10x Genomics can change quickly if life science funding stays tight and product transitions keep pressuring pricing power and profitability.
Find out about the key risks to this 10x Genomics narrative.
Another View: Price-To-Sales Sends A Harsher Signal
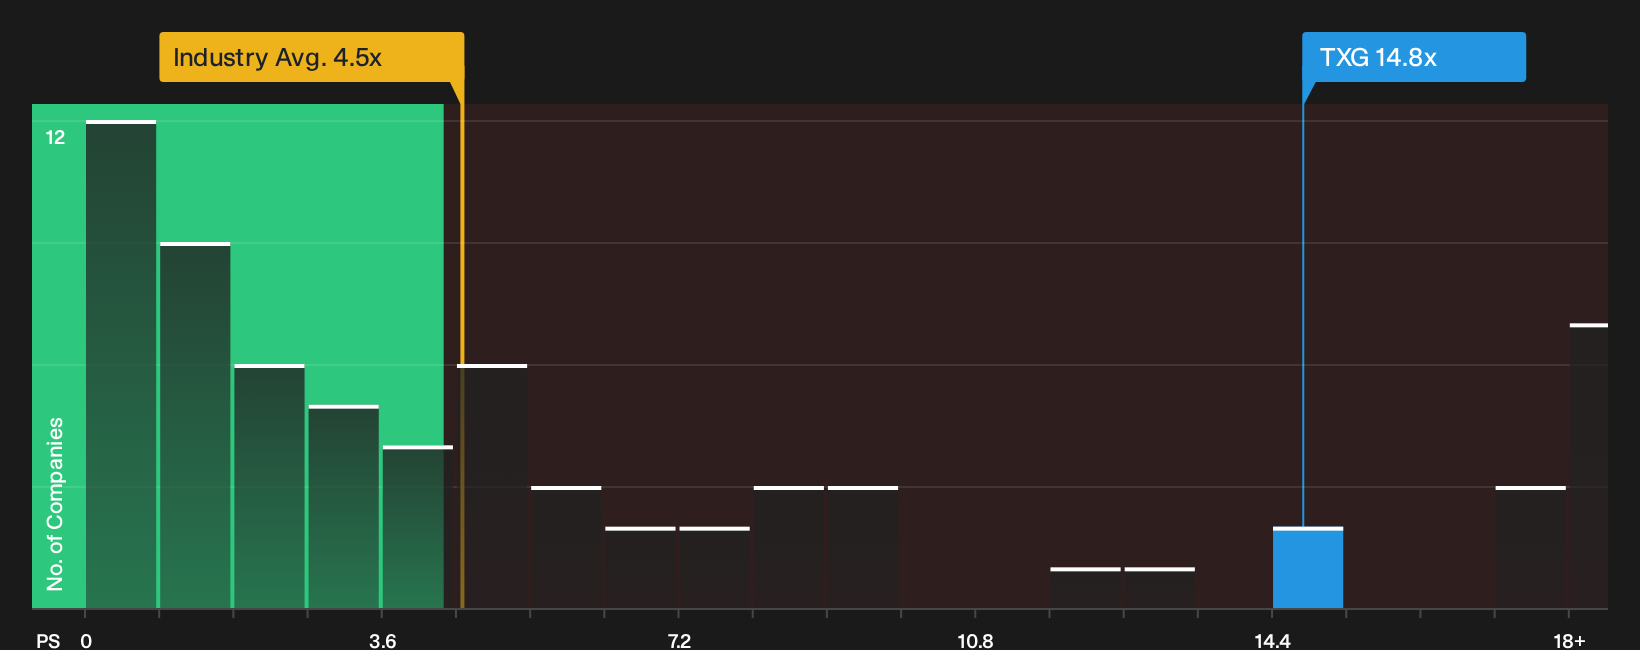
That 7.7% gap between 10x Genomics’ share price and the $75.67 fair value story looks modest. The P/S ratio tells a tougher story. At 14.8x sales, TXG trades at more than double US Life Sciences peers on 4.5x and far above its own 6.8x fair ratio, which may lift valuation risk if sentiment cools.
Put simply, the current P/S suggests investors are paying a premium well beyond sector norms. If the market were to move back toward that 6.8x fair ratio, would the first valuation framework still feel as comfortable to you, or does this richer multiple change how much potential upside you see?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment like this rarely stays neutral for long, so move quickly, review the full data set, and weigh both the upside potential and downside risk using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond 10x Genomics?
If 10x Genomics has caught your attention, do not stop there. Broaden your watchlist now so you are not relying on a single story.
- Target durable value by scanning a curated mix of quality opportunities through the 33 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by reviewing companies with stronger financial footing using the list of solid balance sheet and fundamentals (25 results).
- Hunt for future standouts before they become crowded trades by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com