
Does RBC Upgrade Change The Bull Case For Casey's Stock?
- Casey's General Stores recently drew attention in two ways, with industry data showing year over year lunchtime traffic gains while several major convenience rivals saw fewer visits.
- In the same period, a research upgrade contrasted Casey's operational trends with more leveraged peers and highlighted how its food led traffic appears to be holding up where others are seeing lunchtime softness.
- This article examines how Casey's General Stores' investment narrative is affected by the strong lunchtime traffic trends described in this report.
Casey's General Stores Investment Narrative Recap
For a shareholder in Casey's General Stores, the core belief is simple. Prepared food, beverage and higher margin categories need to keep pulling more customers through the door, while new stores, remodels and technology investments translate that volume into solid earnings. The recent lunchtime traffic gains help that story, but the short term catalyst still hinges on consistent same store performance as remodels and CEFCO conversions ramp.
The biggest near term risk sits on the cost and cash side. Operating expenses in Q1 FY27 ran faster than inside sales, and free cash flow fell to US$190 million from US$262 million as remodel capex stepped up. If that gap between spending, cash generation and fuel or inside volumes widens, the Casey's General Stores expansion and capital return ambitions could feel tighter even with positive traffic headlines.
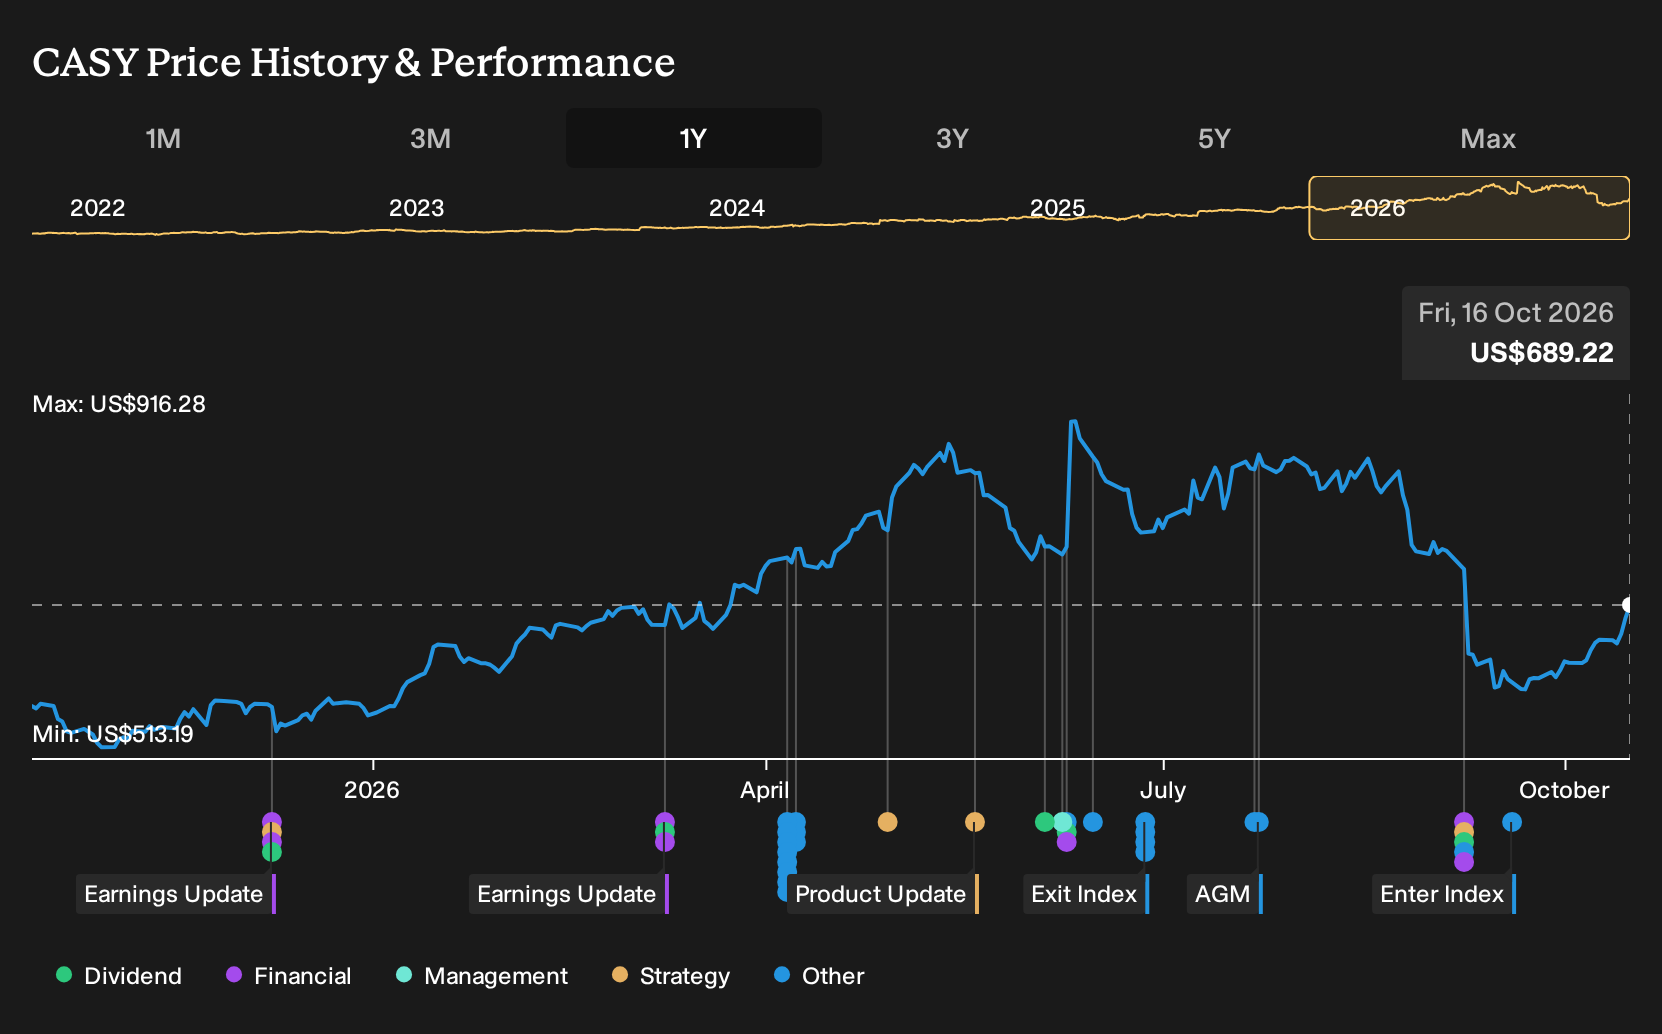
The RBC upgrade to Outperform with a US$825 price target ties directly back to these operating debates. Lunchtime traffic strength, prepared food mix and store growth are all in focus, but the upgrade lands while analysts are still watching fuel margin durability and inside trends after earlier price target cuts. Recent share gains of 2.8% on the call highlight how sensitive the stock can be to small shifts in sentiment around those fundamentals.
For you as an investor, the more interesting part is how this attention intersects with actual execution. Casey's General Stores is already planning at least 400 net new units between fiscal 2027 and 2029, integrating deals like CEFCO, Pak A Sak and ASAP Energy, and leaning on conversions that have been tied to about a 30% lift in prepared food and dispensed beverage sales. The upgrade does not change that roadmap. It simply raises the stakes on whether lunch led traffic momentum and expense control show up cleanly in the next few quarters of results.
Casey's General Stores' current analyst scenario points to revenues of US$22.2b and earnings of US$979.7m by 2029, based on 5.9% yearly revenue growth and an earnings increase of about US$207m from US$772.8m today.
Uncover why Casey's General Stores' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic Casey's General Stores story revolves around earnings power rather than lunchtime traffic. The most bullish analysts were pencilling in revenue of about US$25.3b and earnings near US$1.1b by 2029, far above consensus. Those forecasts came before this upgrade and traffic surprise, so you may see those views shift again as new data lands.
Explore 3 other Casey's General Stores fair value estimates, including one that suggests as much as 35% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Casey's General Stores research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Casey's General Stores. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casey's General Stores' overall financial health at a glance.
Looking for more Casey's General Stores style ideas?
If the lunchtime momentum story at Casey's General Stores has sharpened your interest in this part of the market, it can be useful to scan for other businesses with similar financial traits using the Simply Wall St Screener.
- For investors who want stronger balance sheet support behind their thesis, consider running a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If potential mispricing is your focus, search for stocks trading below their estimated worth by checking out 33 high quality undervalued stocks that already show solid fundamentals.
- Income focused portfolios may benefit from steadier cash returns, so it can help to review 8 dividend fortresses and see which ones match your yield and risk preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com