
Verastem (VSTM) Could Be 50% Undervalued Following VS 7375 Data And Equity Raise
Verastem (VSTM) has become a talking point after detailed TARGET-D 101 data for KRAS G12D inhibitor VS-7375 and a roughly US$250 million follow-on equity raise drew fresh attention to the stock.
Verastem’s latest data and the roughly US$250 million equity raise come on top of a strong 90-day share price return of 43.45% and a 30-day share price gain of 14.57%, even though the 1-year total shareholder return is still down 6.18%. This shows that momentum has picked up recently while longer term holders remain under water.
Spot similar oncology stories building fresh momentum by scanning our hand-picked 33 healthcare AI stocks alongside Verastem’s latest VS-7375 update.Verastem now has fresh VS-7375 data, a larger cash balance and a share price that has already moved sharply. The next step is simple: Do those pieces add up to a fair valuation today?
Most Popular Narrative: 50% Undervalued
Verastem’s most followed narrative pegs fair value at about $17.22 a share, compared with a last close of $8.65. That gap reflects a view that recent VS-7375 progress and the broader RAS or MAPK franchise are not fully captured in the current price.
The combination of an active commercial franchise and a RAS or MAPK focused pipeline, underpinned by a cash position of US$137.7 million and a stated runway into the second half of 2026, gives Verastem room to fund launch activities and clinical development, which directly touches future earnings and the potential to narrow current net losses.
See why 4 investors see Verastem as 50% undervalued.
Result: Fair Value of $17.22 (UNDERVALUED)
Still, the narrative around Verastem can shift quickly if the loss making profile persists alongside high R&D spend, or if key trials like RAMP 301 or TARGET D 101 disappoint.
Find out about the key risks to this Verastem narrative.
Another View: Verastem Through a Sales Multiple Lens
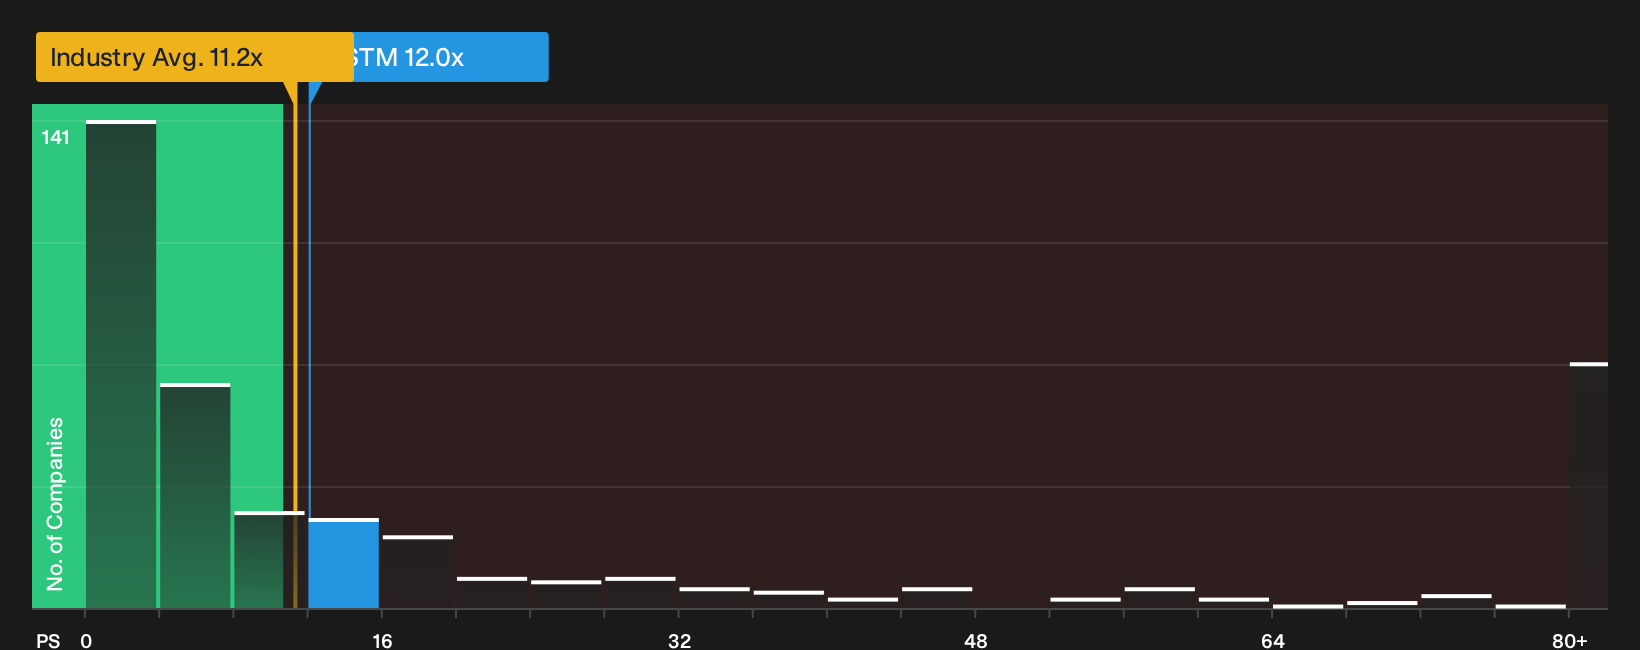
Verastem appears inexpensive relative to the $17.22 fair value narrative, yet its current revenue base suggests a more constrained picture. The stock trades on a P/S of 12x, which is slightly higher than the US Biotechs average of 11.1x and just under the fair ratio of 12.2x that our models indicate the market could move toward.
This combination, a premium to the broader group but close to both peers at 12.5x and the fair ratio, indicates a market that already reflects a meaningful portion of anticipated growth. The key question is whether the VS-7375 data and oncology pipeline justify paying near fair value on sales while the discounted cash flow view still indicates substantial upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Verastem so far, with sharp recent gains and live trial risks in play, mean you may want to act promptly and test the numbers yourself using 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Verastem?
If Verastem has caught your attention, do not stop there. Cast a wider net and pressure test your thesis against other opportunities using the Simply Wall Street Screener.
- Target potential mispricing by reviewing the 33 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect their underlying strength.
- Prioritise resilience by scanning the list of solid balance sheet and fundamentals (25 results) to focus on companies that carry less financial strain on their books.
- Hunt for off-the-radar opportunities through the 20 high quality undiscovered gems that many investors may not even be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com