
3 Defensive Dividend Stocks Holding Up As Interest Rates Stay Higher
Hotter inflation readings and a higher chance of another Fed hike have put rate sensitivity back in the spotlight, yet some dividend payers are holding their ground as bond yields swing. Income investors now face a genuine fork in the road: stick with cash and short-term bonds, or consider equities that historically lean defensive when borrowing costs stay elevated. This article walks through three stocks exposed to this backdrop from our U.S. Rate-Resilient Defensive Equity Income screener and explains why each could matter for your portfolio decisions today.
The three stocks in this article are only a sample, and the full screen surfaced 24 more U.S. Rate-Resilient Defensive Equity Income companies with similarly income focused stories that are not covered here. To go deeper, identify your own short list and analyze them side by side, head straight to the U.S. Rate-Resilient Defensive Equity Income screener.
Otter Tail (OTTR)
Otter Tail fits this screener as a regulated electric utility with extra earnings support from manufacturing and plastics, giving income-focused investors a mix of defensive cash flows and cyclical exposure that can matter when rates stay higher for longer.
Otter Tail runs a regulated electric utility plus manufacturing and plastics operations, with revenue of about US$575 million from Electric, US$407 million from Plastics and US$332 million from Manufacturing, and a market value near US$3.8b.
"Continued execution of Otter Tail’s US$1.9b electric capital program, with a reaffirmed 10% rate base CAGR and nearly 1:1 conversion of that rate base growth into utility earnings, is expected to support future EPS."
What happens to Otter Tail’s margin profile if one pressure point inside that diversified plastics and manufacturing mix does not break the way management expects?
If that margin risk is on your mind, read the full narrative for Otter Tail to see how Otter Tail’s utility growth and plastics swings could be decoupling beneath the surface.

MGE Energy (MGEE)
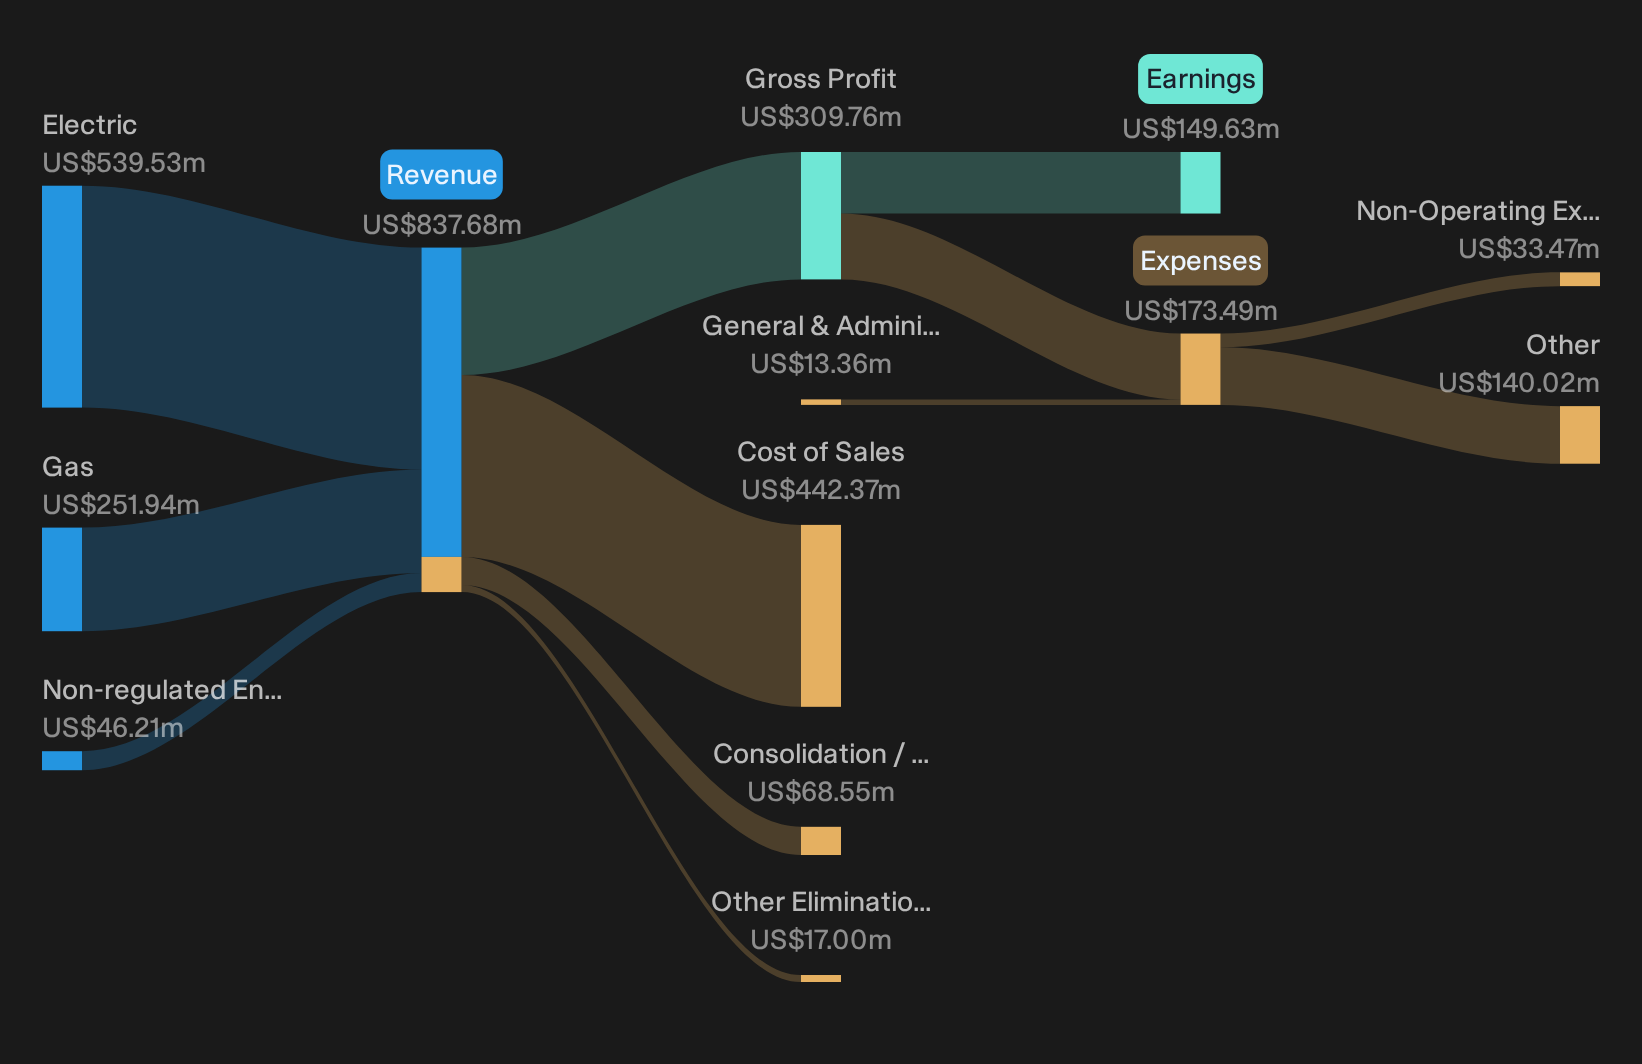
MGE Energy is a regulated utility focused on electricity and natural gas, a classic fit for a defensive income theme that leans on predictable cash flows. It generates about US$540 million from Electric, US$252 million from Gas and US$46 million from Non regulated Energy, with a US$2.7b market value.
MGE Energy offers what many rate conscious investors want from a utility stock: regulated earnings, a 2.63% forward yield and a 51 year dividend increase streak. It also carries high debt and dividends that are not well covered by free cash flow, so the appeal of that long history depends on how one unseen pressure plays out.
That unseen pressure is the real story behind MGE Energy’s income appeal, so go straight to the 3 key rewards and 2 important warning signs and see what could be quietly driving returns.
Sysco (SYY)
Sysco sits in the screener as a large, dividend paying foodservice distributor whose staple like orders can help smooth income when rate sensitive growth stocks feel the heat from higher yields.
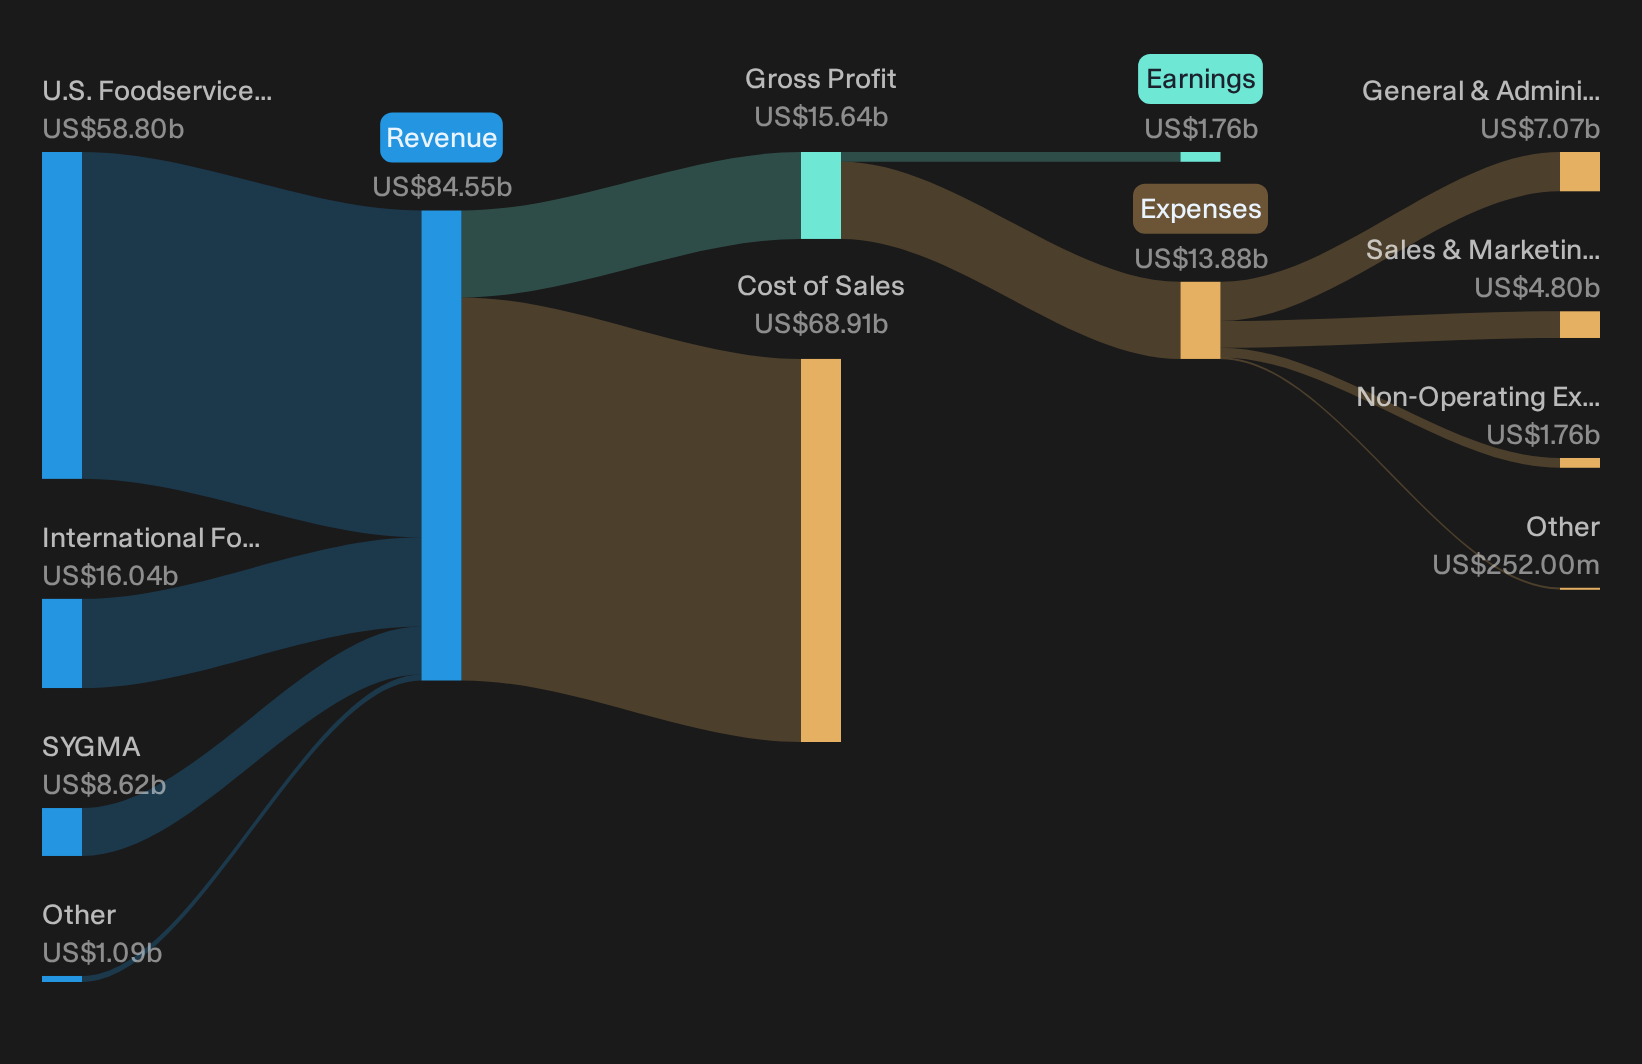
Sysco is a global foodservice distributor supplying restaurants, hospitals, schools and hotels, with about US$58.8b from U.S. Foodservice Operations, US$16b from International Foodservice Operations, US$8.6b from SYGMA and US$1.1b from Other segments, and a market value near US$40.4b.
"Sysco is rolling out more than 30 AI and technology projects across sales, supply chain, merchandising and back office, with about US$100 million of in-year savings built into fiscal 2027 guidance and a targeted US$500 million profit improvement by fiscal 2029 that is aimed at higher operating margins and earnings."
What happens if the one big swing factor behind those potential efficiency gains and future margins does not land exactly as planned?
If that uncertainty around execution is on your mind, the full narrative for Sysco explains where Sysco’s efficiency efforts could either accelerate, stall, or quietly reshape its earnings mix.
Seeking Alternatives Before The Crowd
Fresh ideas move first. The strongest breakouts, fading laggards and quietly improving dividend payers often fly under the radar for now. Screen them while it matters and consider action in a timely way.
- Target reliable cash generators and stress test them against rising rates using the curated list of solid balance sheet and fundamentals (25 results) so you are not left holding fragile stories.
- Track fast moving gold producers with real projects by scanning the tightly filtered 36 elite gold producer stocks before momentum runs and valuations start stretching.
- Spot early robotics companies building real revenue instead of hype by working through the focused 92 robotics and automation stocks while expectations are still dropping in many crowded themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com