
Is Entra (OB:ENTRA) Undervalued After Its Quarterly Loss And Rising Financing Costs?
Entra (OB:ENTRA) has landed in the spotlight after its third quarter 2026 report showed a sharp swing to loss, even as occupancy stayed high and new long term leases were signed in Oslo.
At a share price of NOK94.7, Entra has seen a short burst of strength, with a 7 day share price return of 4.18%. However, the 90 day share price return is down 9.81% and the 1 year total shareholder return has fallen 18.15%.
Spot under-pressure real estate plays like Entra and compare them with 234 resilient stocks with low risk scores, which pairs steadier balance sheets with more resilient share price performance.Entra now trades higher on the week but carries heavier losses, both in the latest quarter and over the past year. Does that mix of fresh leasing progress and financing strain still skew the risk reward toward buyers?
Most Popular Narrative: 9% Undervalued
With Entra last closing at NOK94.7 against a widely followed fair value of NOK104.4, the narrative presents the gap as a discount while still emphasizing that strong Oslo offices and higher assumed margins need to carry substantial weight in the story.
Strong demand for prime office locations in Oslo and other major Norwegian cities, combined with limited new supply in the near term, is likely to support higher occupancy and above-inflation rental growth in Entra's portfolio positively impacting future revenue and earnings.
Continued central government and technology sector employment in Norway provides Entra with a stable, creditworthy tenant base, reducing vacancy risk and supporting sustained rental income visibility for long-term revenue growth.
See why 2 investors see Entra as 9% undervalued.
Result: Fair Value of NOK104.4 (UNDERVALUED)
Still, the Entra narrative can be knocked off course if vacancies in smaller offices persist, or if high leverage meets tougher refinancing conditions.
Find out about the key risks to this Entra narrative.
Another View: What Multiples Say About Entra
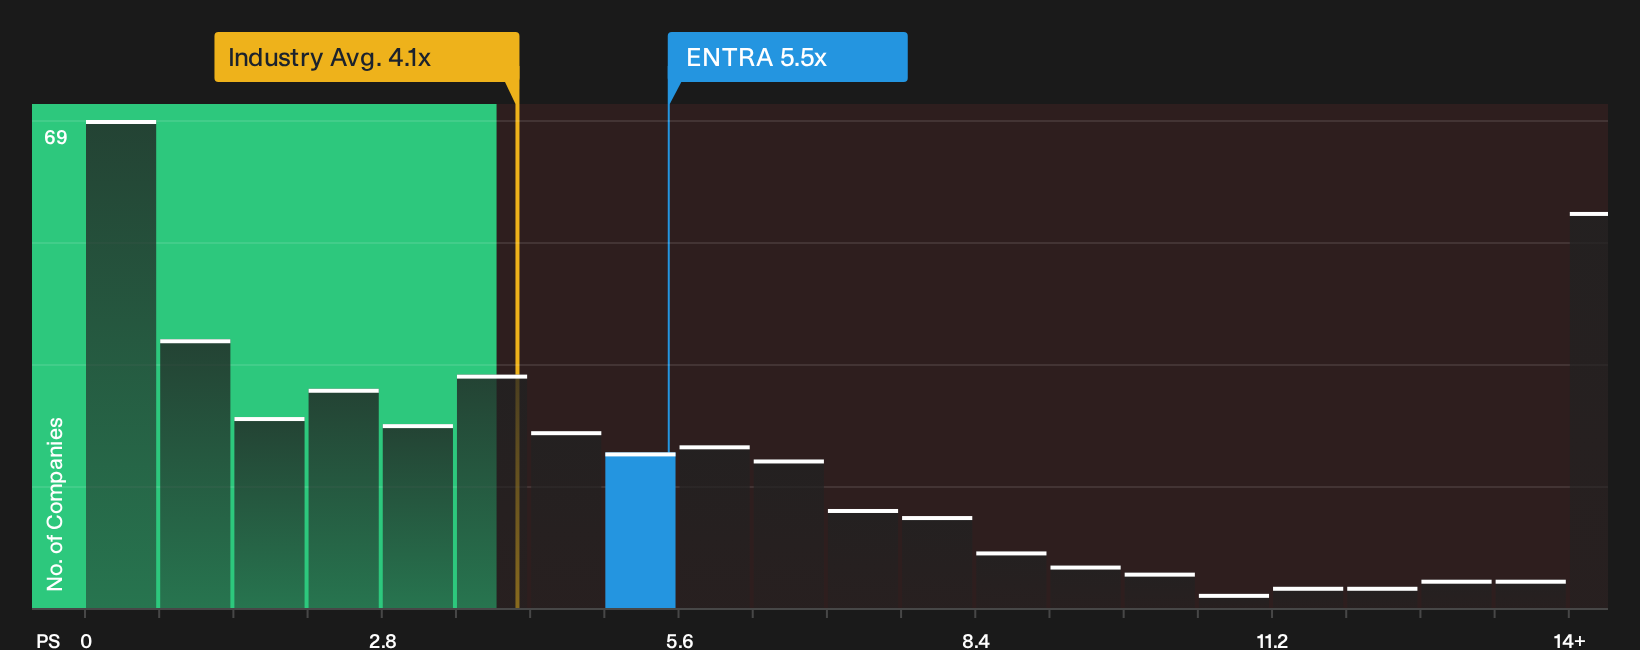
The analyst fair value of NOK104.4 suggests Entra is 9% below that mark, yet the market is already paying a rich P/S of 5.5x against both the European real estate peer group at 4x and a fair ratio of 7.6x. That mix of premium pricing and remaining headroom on the fair ratio raises a simple question: is this a mispriced opportunity or a sign that expectations are already running hot?
To see how that pricing gap stacks up against detailed valuation work and comparable companies, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Entra's valuation and recent losses can pull sentiment in both directions, so move fast, review the numbers, and weigh both the upside and the downside using the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Entra?
Do not stop your research with Entra. Broaden your watchlist using focused stock lists that surface different types of opportunities across quality, value, and income.
- Target potential mispricings by scanning a curated set of companies trading below estimated value through the 191 high quality undervalued stocks.
- Strengthen your defense by focusing on businesses with healthier finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (205 results).
- Lock in income ideas by reviewing companies screened for higher yields and more robust payouts inside the 215 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com