
Should Earnings Estimate Cut Require Action From Adidas Stock Investors?
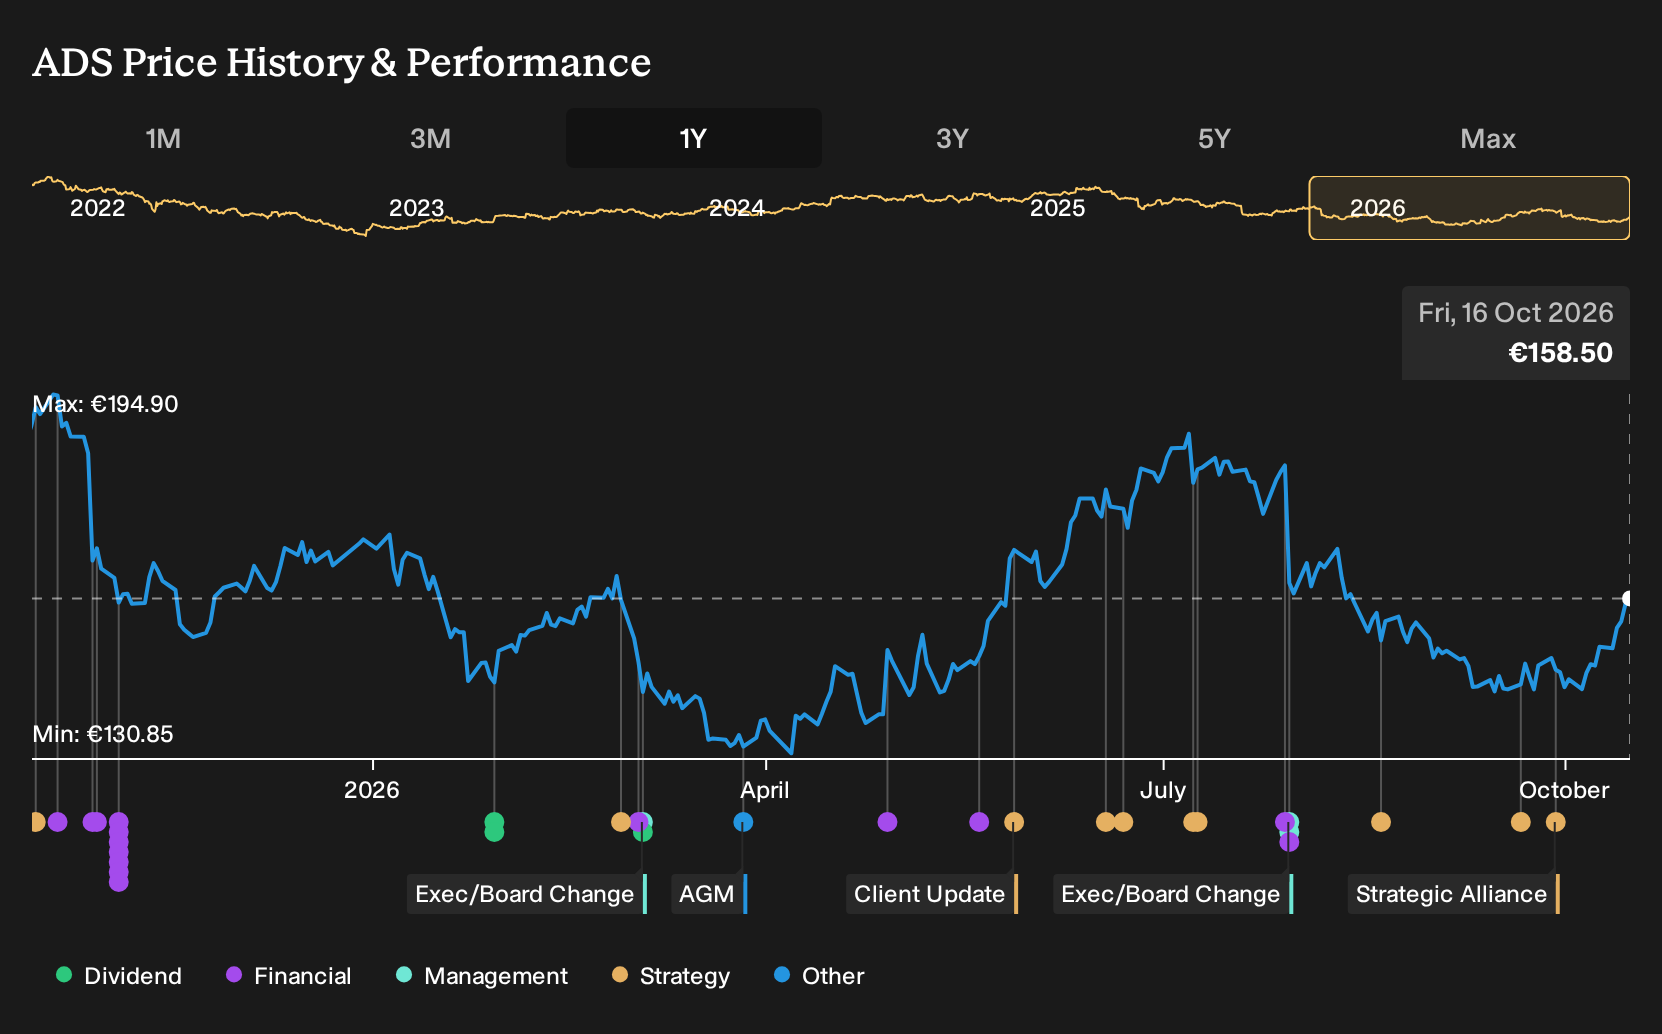
- Adidas AG has recently faced a 5.1% cut to current year earnings estimates, as analysts highlight pressure on near term profitability from tariffs, fashion cycle risk, and questions around cost discipline and demand resilience.
- The more interesting angle for investors is how these cost and demand pressures intersect with adidas's push toward higher margin direct to consumer channels and performance categories that underpin its longer term commercial ambitions.
- We will now look at how adidas's investment narrative holds up in light of the earnings estimate cut and profitability concerns.
Pressure test adidas against its peers and search for other brands managing similar cost headwinds with a curated list of list of solid balance sheet and fundamentals (205 results)
adidas Investment Narrative Recap
For adidas, the big picture you need to buy into is fairly clear. The business leans on higher margin direct to consumer sales and performance categories like running and football to keep returns attractive while dealing with tariffs and promotions in wholesale. The recent earnings cut highlights that near term profitability is under pressure, yet the core product and channel focus still sits at the centre of the thesis.
The critical short term catalyst is whether adidas can hold gross margins around the low 50% range while absorbing roughly €200m of tariffs and foreign exchange drag. The biggest risk is that heavy discounting by competitors and flat lifestyle footwear leave adidas choosing between protecting pricing and accepting softer volume, or chasing volume at the expense of profitability.
With no fresh corporate announcements tied directly to this earnings revision, the most relevant reference point is management's unchanged ambition for about €2.3b of EBIT and the focus on cost discipline. That target, together with a plan to keep gross margins resilient despite tariff and FX headwinds, is exactly what investors will measure against the new estimate cuts.
Execution around direct to consumer, performance categories and local for local initiatives in Greater China and other Asian markets still acts as the main operational swing factor. If adidas keeps growing these higher margin regions and channels while managing promotional intensity in Europe and North America, the current tariff and cost concerns look more like an earnings quality test than a shift in how the business fundamentally earns money.
What The adidas Forecasts Actually Assume
On the current analyst view, adidas is effectively being judged on whether it can turn its direct to consumer and performance push into much larger earnings by the end of the decade. Consensus models point to revenues of €32.0b and profits of €2.4b by 2029, with the long term story hinging on whether that bigger, more profitable version of the company can coexist with the tariff and promotion pressures hitting near term results.
Those projections build in 7.1% yearly revenue growth and an earnings move from €1.4b today to a forecast €2.4b in 2029. That is an increase of about €1.0b in earnings, with analysts effectively asking whether adidas can scale its direct to consumer mix and performance categories enough to support that higher profit base while tariffs, FX and marketing spend keep biting into the income statement over the next few years.
Uncover why adidas' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take focuses on adidas using big global events as a springboard. The most optimistic analysts were pencilling in revenue of €33.5b and earnings of €2.7b by 2029 before this Zacks Rank change. That is a more upbeat story than consensus, and it may be revised once this earnings cut sinks in.
Explore 5 other adidas fair value estimates, including one that suggests as much as 118% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your adidas research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for adidas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate adidas' overall financial health at a glance.
Looking for more adidas investment ideas?
If adidas is already on your watchlist and you want to round out your research, the Simply Wall St Screener can help you line up other opportunities with similar or complementary traits so your portfolio is not leaning on a single story.
- If you want potential mispricing combined with quality fundamentals, consider widening your search with a curated set of 190 high quality undervalued stocks that share solid earnings power and cleaner balance sheets.
- If resilience matters most to you, filter for businesses that prioritise financial strength and conservative risk profiles through a focused 233 resilient stocks with low risk scores that keeps capital protection front and centre.
- If you are hunting for stocks that the crowd may have overlooked, use a hand picked 618 high quality undiscovered gems to surface under followed companies with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com