
3 UK Stocks for Trusted Cloud and Data Sovereignty Exposure
UK politics is suddenly colliding with artificial intelligence, as concern over Chinese models like DeepSeek puts data sovereignty and trusted cloud infrastructure under a harsh spotlight. That shift could reshape where sensitive workloads, security budgets and compliance spending go next, creating potential openings as well as traps for investors watching UK Sovereign and Trusted Cloud Infrastructure stocks. This article unpacks the theme and then explores 3 UK-listed companies directly exposed to this news.
The stocks covered below are just a starter pack, and the full screen surfaced 13 more UK Sovereign and Trusted Cloud Infrastructure companies with equally compelling narratives that are not in this short list. If you want to identify potential winners at scale, head straight into the UK Sovereign and Trusted Cloud Infrastructure screener
Redcentric (AIM:RCN)
Overview: Redcentric provides UK-based managed IT services, combining secure cloud hosting, networking, communications and security solutions for public sector bodies and private enterprises.
Operations: Redcentric generates about £132 million of revenue from managed service provider activities, almost entirely from customers in the United Kingdom.
Market Cap: £88 million
Redcentric matters for this UK Sovereign and Trusted Cloud Infrastructure theme because it already runs critical managed services where data location, control and security are central to customer decisions.
"Positioning Redcentric as a preferred provider of sovereign, compliant and regulated IT services in the U.K., including operation of national government and large sovereign cloud platforms, creates a differentiated offering that can support contract wins, recurring revenue and longer term earnings visibility."
What happens to Redcentric’s margin potential if a single key assumption about future high quality contract mix or cost savings does not hold?
If that contract mix question is front of mind, the full full narrative for Redcentric shows how those margin swings could be accelerating or masking Redcentric’s true potential.

SEGRO (LSE:SGRO)
Overview: SEGRO is a UK REIT that owns and develops warehouses, industrial parks and data centres that support logistics and AI-era digital infrastructure.
Operations: SEGRO generates £630 million of rental income from investment and trading properties, with £473 million from the UK and £183 million from Continental Europe.
Market Cap: £12.4b
SEGRO gives you exposure to the physical backbone behind sovereign cloud and AI in the UK, where secure power, proximity and colocation space all matter more as policymakers push workloads away from Chinese platforms.
"Segro's power reserves and high-yield projects, which we characterized as a 'hidden treasure' on its balance sheet, inevitably made the company a highly attractive acquisition target."
What happens to SEGRO’s pricing power and cash generation if one unseen constraint on future data centre build outs tightens further?
If that constraint risk worries you, the full narrative for SEGRO shows how SEGRO’s power reserves, capital plans and tenant mix could be accelerating or masking long term value.

Capita (LSE:CPI)
Overview: Capita runs large scale outsourcing and digital services for UK public bodies and corporates, including secure, AI enabled government IT operations.
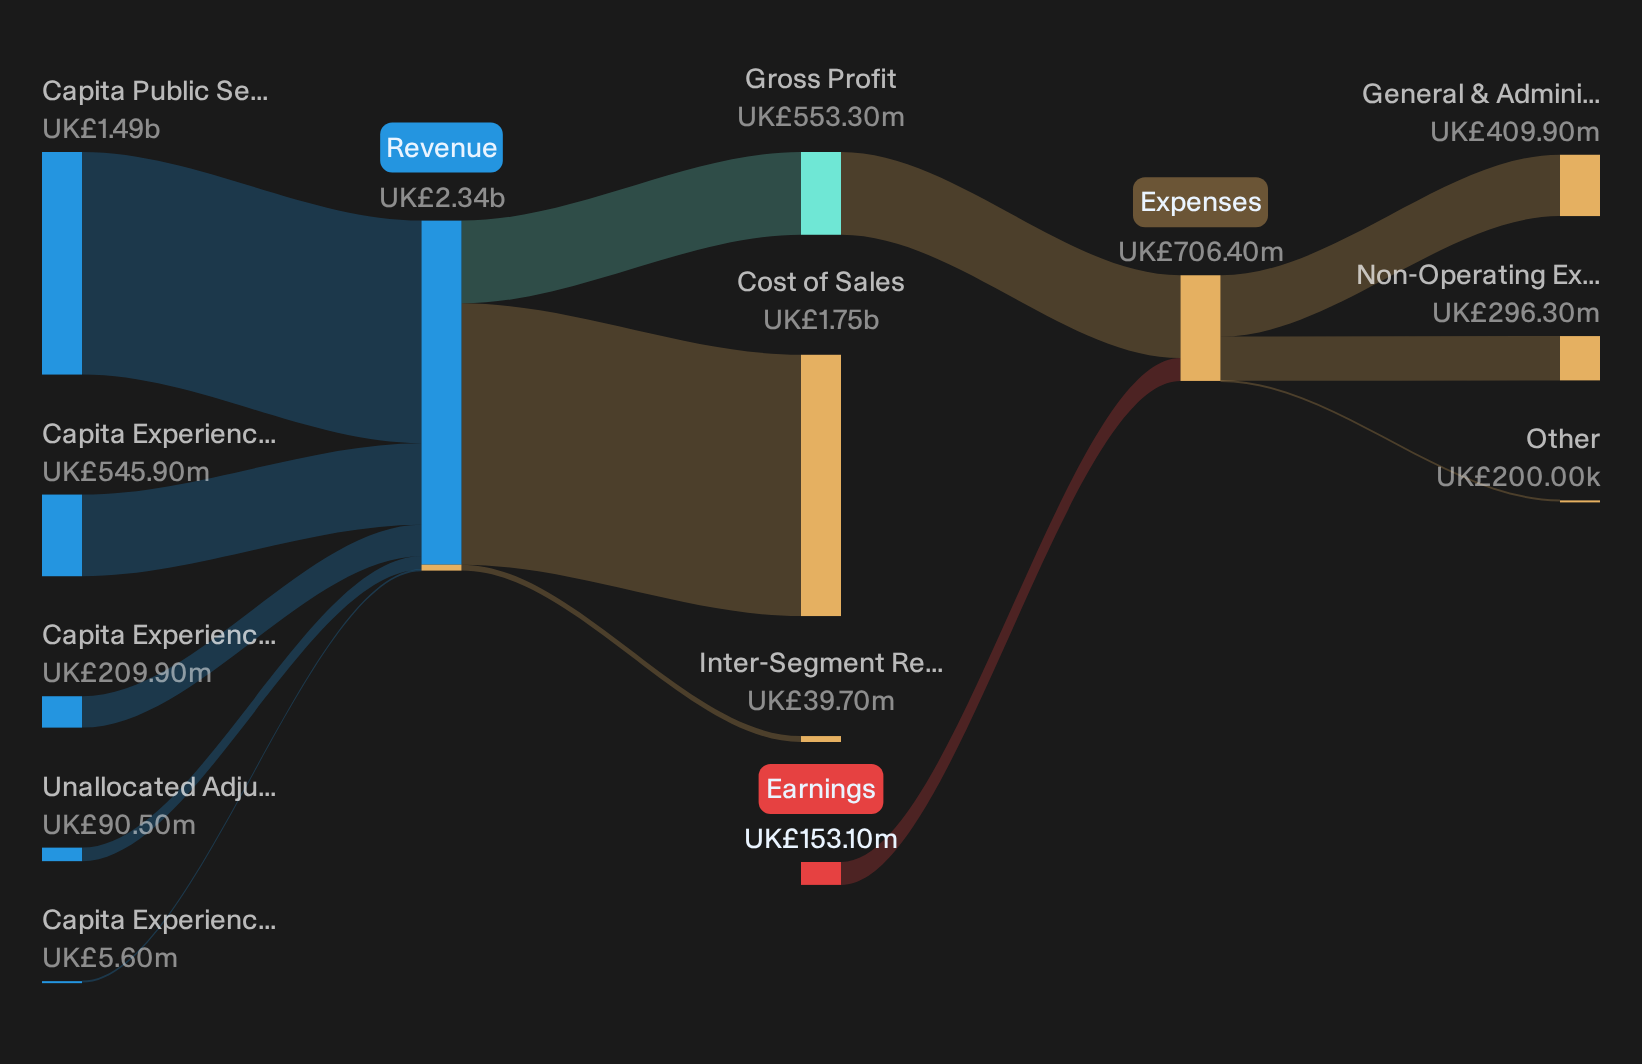
Operations: Capita generates about £1.5b from Public Service contracts and roughly £762 million from Experience activities spanning contact centres and pension solutions.
Market Cap: £344 million
Capita matters for the UK Sovereign and Trusted Cloud Infrastructure theme because it already runs sensitive public sector systems where AI, data governance and secure cloud choices directly affect how government services are delivered.
"Capita has introduced the Forward Deployed Orchestrator, or FDO, an operating model aimed at helping organisations convert AI investments into measurable operational outcomes in middle and back office functions, with a focus on safe deployment in regulated environments. Within Capita's own operations, early use of the FDO model in high-volume recruitment has been associated with over 1,000 management and recruitment hours saved in the first four months, a 43% reduction in candidate screening time and faster processing of straightforward applications in another regulated service."
What happens to Capita’s earnings potential if a single assumption about how public bodies value trusted AI partners in regulated settings shifts?
If that shift in how decision makers price trusted AI partnerships is the real swing factor, the full narrative for Capita shows where Capita’s risk and upside may be quietly decoupling.
Curious About Alternatives Worth Investigating?
Fresh ideas move first. By the time every headline chases a breakout, the real momentum has often flown. Scan under the radar for now, act now.
- Spot steady cash generators before they hit the mainstream by scanning a curated list of solid balance sheet and fundamentals (9 results) that highlights resilient operators while the crowd is still looking elsewhere.
- Ride structural demand shifts by tracking 41 power grid technology and infrastructure stocks that could benefit as electricity infrastructure, grid upgrades and reliability pressures filter through to listed businesses.
- Position around AI’s real money makers by focusing on 38 profitable AI stocks that aren't just burning cash that already balance growth ambitions with tangible earnings, not just headline-grabbing promises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com