
Pro Medicus Stock Gets A Digital Pathology AI Showcase At PathVisions 2026
- Pro Medicus, via subsidiary Visage Imaging, recently showcased new Visage 7 CloudPACS and Digital Pathology capabilities at PathVisions 2026, including automatic registration, AI-assisted cell counting, fluorescence support and z-stacking for integrated imaging workflows.
- The push to fold digital pathology, AI tools and multimodality viewing into a single Visage 7 platform points to deeper cross specialty usage and potentially higher transaction volumes per client over time.
- We will now examine how Pro Medicus' expanded Visage 7 digital pathology and AI toolkit could reshape the broader investment narrative for the business.
Scan how Pro Medicus is leaning into AI driven imaging workflows, then size up a curated set of peers riding the same trend through our 7 healthcare AI stocks.
Pro Medicus Investment Narrative Recap
To own Pro Medicus, you need to believe its cloud based Visage 7 platform can keep winning hospital deals, extend into new ologies and support high margins for a long time. The key near term swing factor is how consistently it converts current pipelines into large, multi year contracts, especially in North America where revenue concentration is high.
The biggest risk right now is that health systems delay imaging upgrades or opt for cheaper bundles from large incumbents and AI specialists, which could pressure pricing on renewals. The PathVisions 2026 feature set looks helpful for differentiation, but on its own it is not a clearly material catalyst in the very short term.
The PathVisions 2026 showcase around Visage 7 CloudPACS and Digital Pathology matters most because it goes directly to the multi ology thesis. Radiology, pathology and other image heavy specialties on one platform give Pro Medicus a clearer operational story to tell in U.S. integrated delivery network RFPs where buyers want fewer vendors and consistent workflows.
For catalysts, that same toolkit sits alongside existing efforts to expand into cardiology, AI and full cloud deployments on AWS, Azure or GCP. Execution risk is still real, since rivals are investing heavily and digital pathology adoption is early, but if clients standardise on One Platform the potential contract sizes and attached AI usage could become more meaningful over time.
Pro Medicus' current analyst narrative points to A$508.6 million in revenue and A$287.1 million in earnings by 2029, based on forecast yearly revenue growth of 24.8%. That outlook implies an earnings increase of A$21.8 million from earnings today of A$265.3 million.
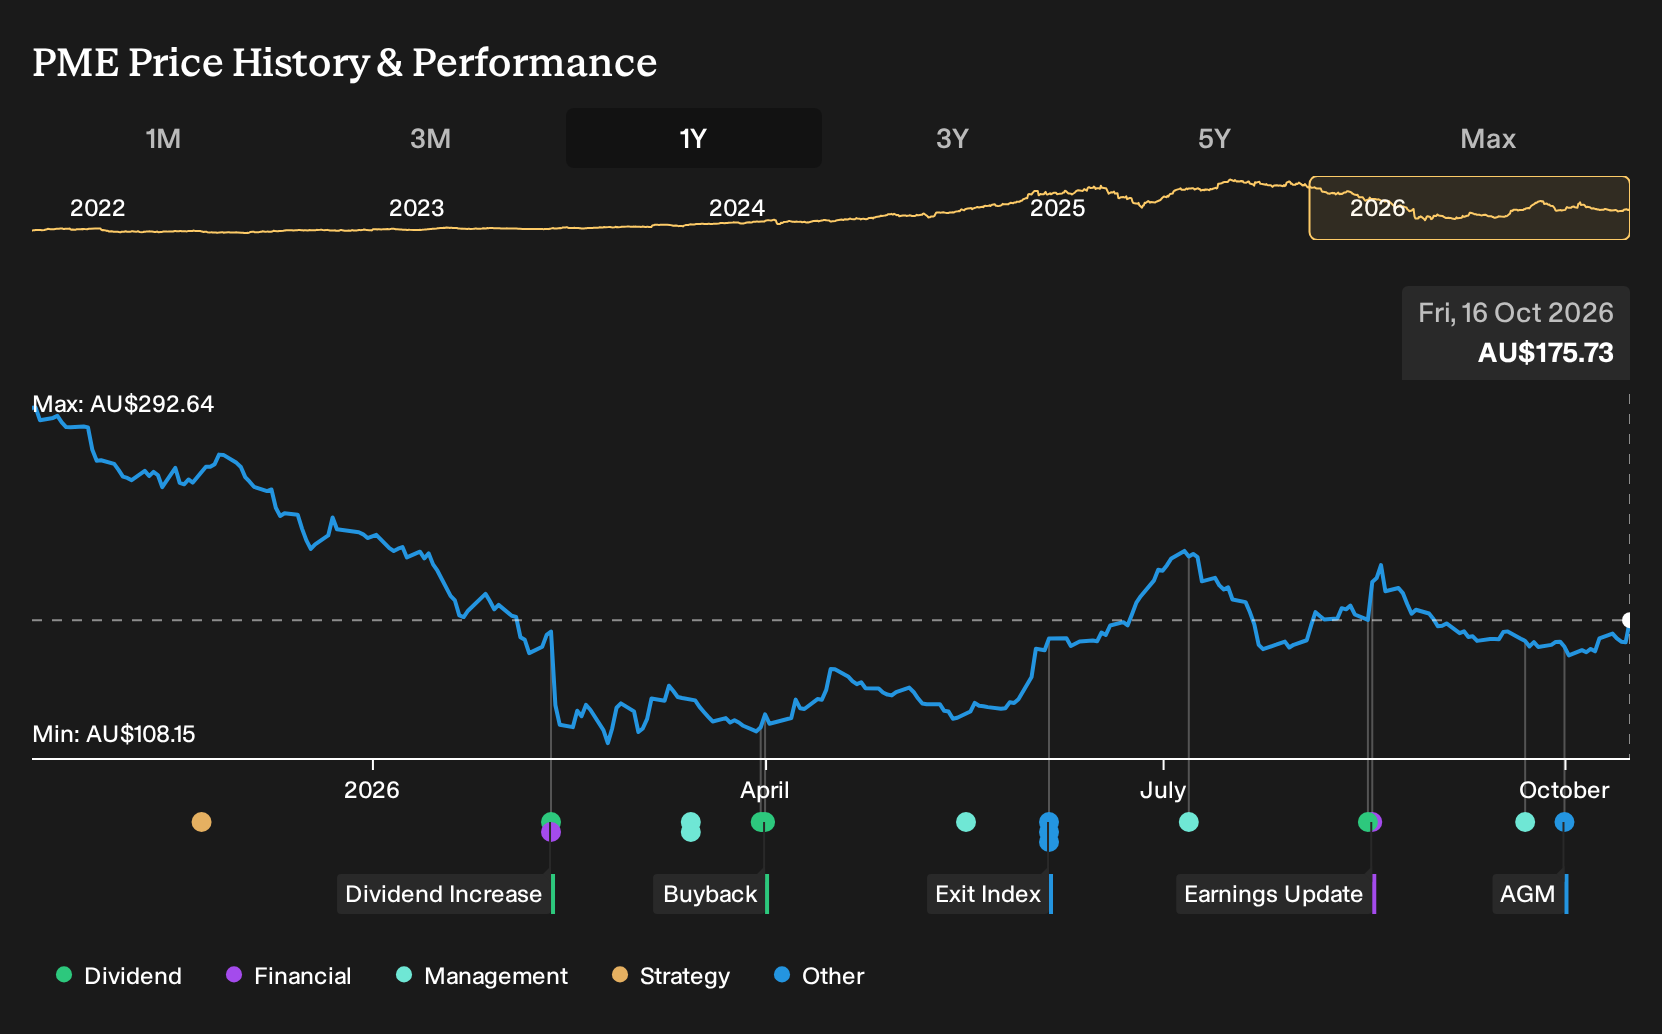
Uncover why Pro Medicus' fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most cautious analysts focus on a different angle. They worry that digital pathology and AI might ramp more slowly, which could keep 3 year revenue growth closer to 17.5% and pull 2029 earnings toward A$232.7 million instead of A$287.1 million. Those views were set before this news, so you may see forecasts shift as expectations reset.
Explore 9 other Pro Medicus fair value estimates, including one that suggests as much as 69% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pro Medicus research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pro Medicus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pro Medicus' overall financial health at a glance.
Looking For More Investment Ideas Beyond Pro Medicus?
Once you have formed a view on Pro Medicus, it can help to set that opinion alongside a wider watchlist of companies with different risk and return profiles. The Simply Wall St Screener lets you move quickly from a single ticker view to a short list that matches the kind of balance sheet strength, income profile or potential upside you want to focus on next.
- If you want potential upside paired with financial resilience, start by reviewing a 15 high quality undiscovered gems that already show solid fundamentals but attract less market attention.
- For a focus on capital preservation and smoother rides through volatility, filter for a 6 resilient stocks with low risk scores that score well on stability and balance sheet quality.
- If income is a priority, zero in on companies offering a 4 dividend fortresses where higher yields are backed by underlying fundamentals rather than just headline payout ratios.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com