
Is CorVel (CRVL) Overvalued As AI Optimism Lifts Its Fair Value Estimate?
Argus recently lifted its fair value estimate for CorVel (CRVL) to US$87, spotlighting the healthcare cost management specialist and its use of artificial intelligence tools in workers’ compensation and liability claims.
CorVel’s recent share price action has been firm, with a 30 day share price return of 11.88% and a 90 day move of 29.16% clustering around the current US$79.69 level. The 1 year total shareholder return of 11.49% points to more moderate longer term progress and hints that recent enthusiasm has picked up as investors reassess growth potential and risk around its AI driven claims platform.
Spot fresh AI driven healthcare opportunities beyond CorVel by scanning our hand picked 33 healthcare AI stocks that may be catching similar attention from the market.After that sharp 90 day climb, the live question is whether CorVel’s AI story still offers valuation upside, or if most of the repricing now sits in the rear view mirror.
Price-to-Earnings of 34.9x: Is It Justified For CorVel?
On a simple comparison, CorVel trades on a P/E of 34.9x while peers average 65.1x, yet the shares also change hands at $79.69 against an SWS DCF estimate of $65.75, so the picture is mixed rather than cleanly cheap or expensive.
The P/E ratio links the current share price to the last reported earnings per share, which makes it a useful shorthand for what investors are willing to pay for each dollar of profit. For a healthcare cost management business like CorVel that leans on software and services, earnings based measures can capture how the market weighs its profit track record, perceived resilience and any optimism around its AI powered claims platform.
CorVel has a record of earnings growth of 14.2% per year over the past 5 years, with the most recent year at 14.4%, and carries a high 28.2% return on equity together with high quality earnings and improving net profit margins from 11% to 11.7%. That mix of consistent profit expansion and strong capital efficiency gives at least some rationale for a premium P/E to the broader US Healthcare industry average of 25.6%, even if it still screens as lower cost than the 65.1x peer average cited in the data. Investors are paying more than the industry for each dollar of earnings, so the question is whether that earnings and margin profile sufficiently supports the premium or whether expectations have become stretched.
Against the industry, the gap is clear. The stock trades materially above the sector P/E of 25.6x, which signals the market is assigning CorVel a richer earnings tag than typical healthcare operators and baking in stronger profitability or durability than the sector at large.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 34.9x (OVERVALUED)
Still, CorVel’s premium P/E rests on faith that its AI heavy model continues to resonate with payors. Any slowdown in claims volumes or tech adoption could quickly challenge that confidence.
Find out about the key risks to this CorVel narrative.
Another View On CorVel’s Valuation
The P/E comparison paints CorVel as expensive against the wider US Healthcare sector, yet more affordable than its direct peers. The SWS DCF model adds a tougher lens. It places fair value at $65.75, which frames the current $79.69 price as overvalued and raises the question of whether enthusiasm around its AI tools has gone a little too far.
Look into how the SWS DCF model arrives at its fair value.
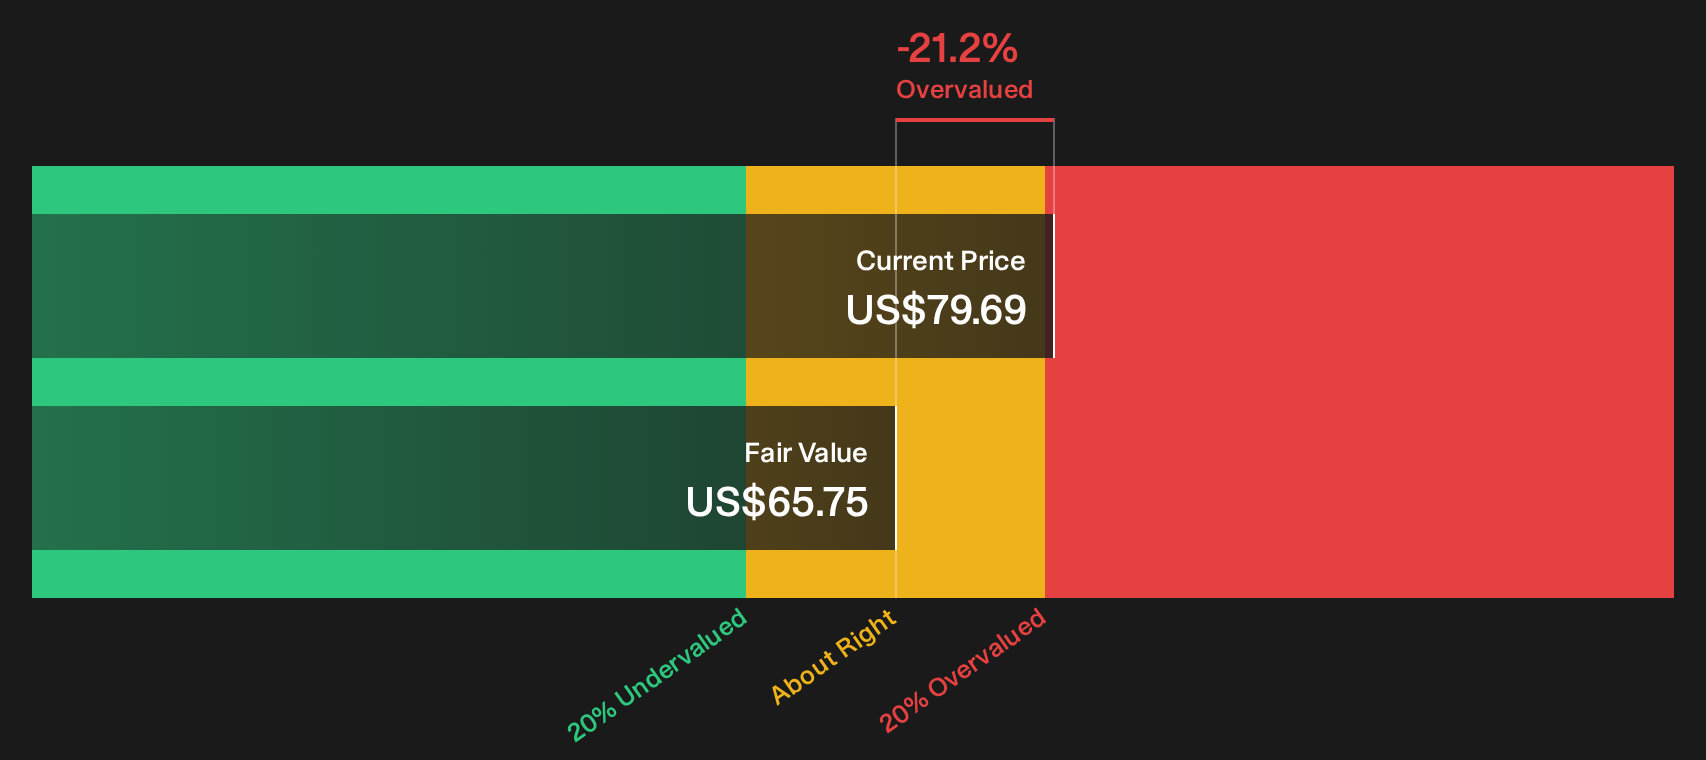
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CorVel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
CorVel inspires both confidence and caution in this story, which is exactly when it pays to look at the underlying data yourself and move quickly to shape an informed opinion backed by the 1 key reward and 1 important warning sign
Ready to hunt beyond CorVel?
If CorVel has sharpened your focus on quality, do not stop here. The next move is lining up more ideas that match your standards.
- Target rock solid financial footing by scanning a list of solid balance sheet and fundamentals (25 results) that can handle pressure when conditions change.
- Pursue mispriced opportunities by running through a 20 high quality undiscovered gems that the wider market may not be watching yet.
- Dial back portfolio stress by reviewing a 32 resilient stocks with low risk scores that aims to keep volatility in check while you stay invested.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com