
Macerich (MAC) Faces A Valuation Split, Is The Recent Pullback A Buying Opportunity?
Macerich (MAC) remains in focus after recent share moves that left the stock up over the past month but lower over the past 3 months, prompting fresh questions around value and income potential.
The recent pattern around Macerich hints at fading momentum in the short term, with the 1 day share price return slipping 0.56% even after a 7 day gain of 3.19%. At the same time, a 1 year total shareholder return of 37.58% and a 3 year total shareholder return of about 1.45x indicate that longer term holders have still seen strong wealth creation.
Spot fresh momentum and income ideas by comparing Macerich with a curated 33 high quality undervalued stocks that blends price appeal with solid fundamentals.Macerich is caught between a strong 1 year run and a 3 month pullback, which raises a simple timing puzzle: Is the better move to step in now, or to wait for a deeper reset before the valuation case stacks up?
Most Popular Narrative: 14% Undervalued
Macerich's most followed valuation storyline pegs fair value at $26.63, above the latest close of $22.96. This puts the recent pullback against a still supportive long term thesis.
The focus on experiential and destination-oriented retail (e.g., DICK'S House of Sport, Cheesecake Factory, entertainment concepts) is revitalizing consumer engagement and increasing traffic. This is positioning the portfolio to benefit from experience-driven spending and capturing higher net margins over time.
See why 1 investors see Macerich as 14% undervalued.
Result: Fair Value of $26.63 (UNDERVALUED)
Still, Macerich carries high leverage and refinancing needs, and a deeper hit to brick and mortar tenants could quickly strain occupancy and cash flow expectations.
Find out about the key risks to this Macerich narrative.
Another View: Macerich On Sales-Based Valuation
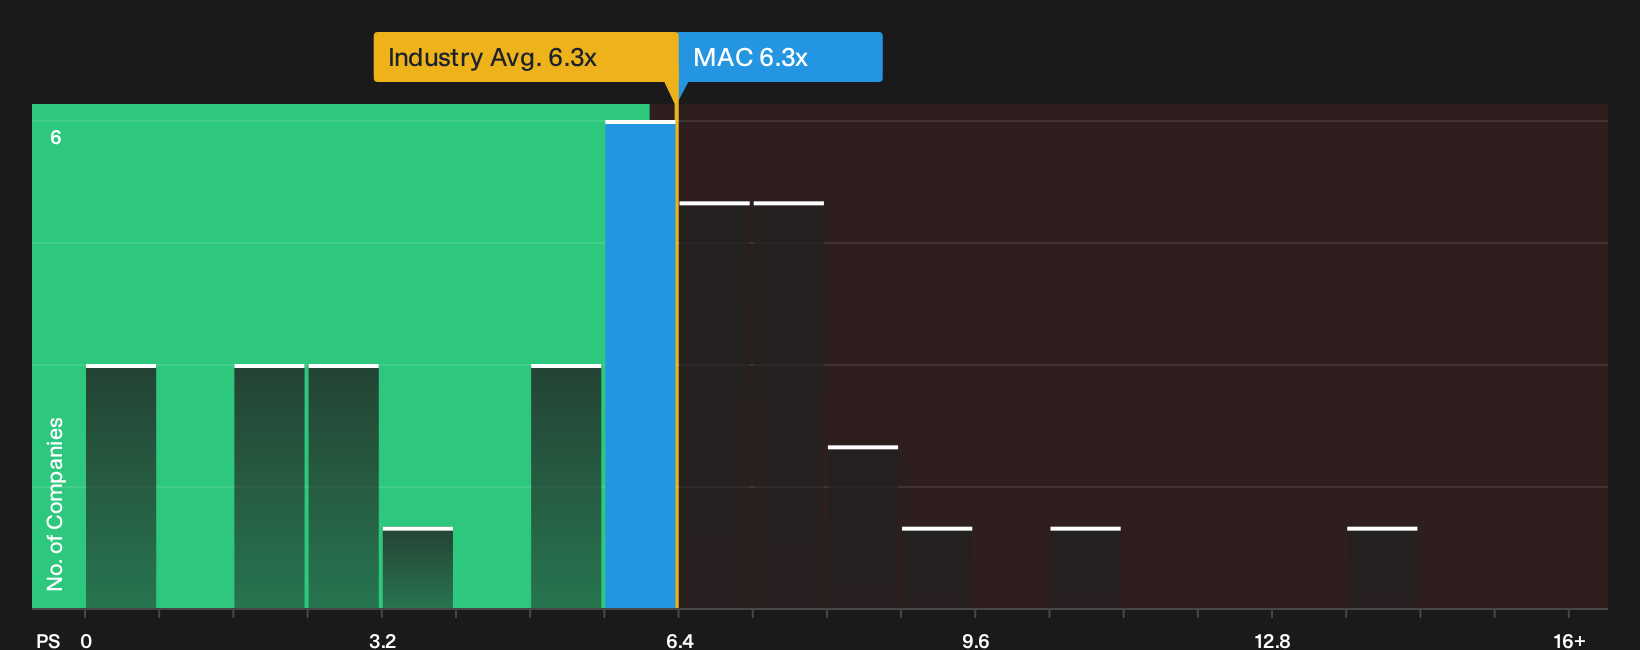
The first fair value story around Macerich leans on future cash flows and a $26.63 estimate. A different lens tells you something less comfortable. On a P/S of 6.3x, the stock trades richer than its own fair ratio of 4.2x, even if it lines up closely with the US Retail REITs average of 6.4x.
That gap between 6.3x and a 4.2x fair ratio implies limited room for error if revenue or margins fall short, since the market could shift closer to that lower multiple rather than reward more optimism. The real question is whether you view the DCF-based upside or the P/S-based caution as the anchor for your Macerich thesis.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Macerich's value story call for your own verdict, not just the crowd's. Move quickly, review both the upside case and the caution flags, and weigh the balance of 2 key rewards and 2 important warning signs
Looking for more Macerich-sized opportunities?
Do not stop with Macerich alone. Give yourself options by scanning other ideas so you can compare quality, risk, and income potential side by side.
- Target powerful upside setups by zeroing in on companies that combine quality metrics with attractive valuations through the 20 high quality undiscovered gems.
- Prioritize resilience and sleep-better-at-night holdings by filtering for financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
- Build a watchlist that can weather rough patches by focusing on companies with lower risk profiles through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com