
Why Is a2 Milk (NZSE:ATM) Back In The Spotlight?
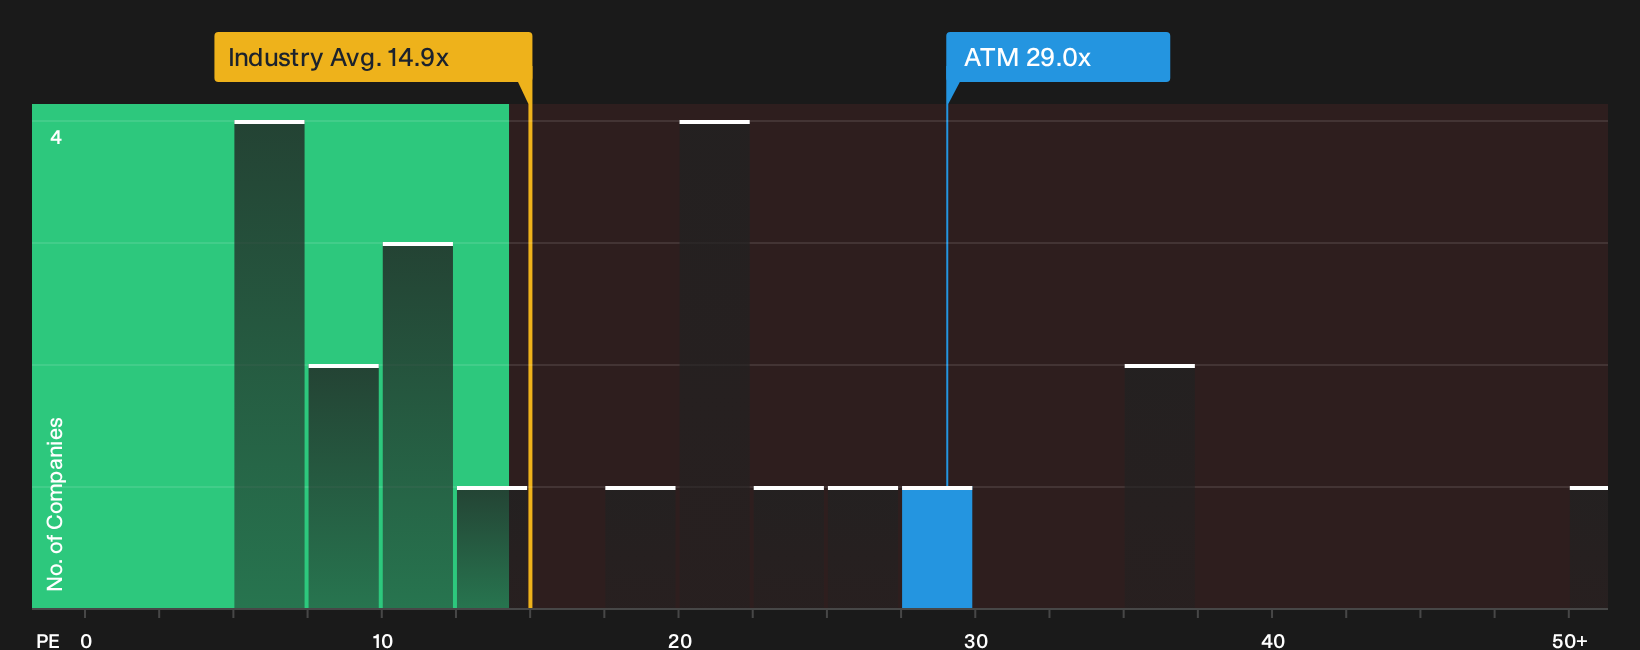
Recent discussion around a2 Milk (NZSE:ATM) has zeroed in on its P/E of about 29x, which sits well above both the wider food industry and close peers. This has prompted fresh questions about what investors are paying for.
Over the past year, a2 Milk’s share price has retreated 21.9% year to date, even as the stock carries a P/E of roughly 29x. That weaker momentum contrasts with a 109.1% three year total shareholder return, which still shapes how investors weigh today’s valuation against recent moves such as J.P. Morgan’s substantial holder notice.
Compare how a2 Milk’s premium P/E stacks up against other companies by scanning a curated set of 191 high quality undervalued stocks that combine stronger fundamentals with less demanding valuations.
Bulls point to a2 Milk’s earnings profile and brand strength, while bears argue a 29x P/E and weaker year to date return already stretch belief. Which side does the current valuation actually support?
Most Popular Narrative: 10.5% Undervalued
a2 Milk’s most followed narrative pegs fair value at NZ$9.38, compared with the NZ$8.39 last close, which frames that 29x P/E in a very different light.
The company's expansion plans, including establishing additional China-label IMF registrations and developing new manufacturing capabilities, require considerable capital expenditure. This may impact future earnings if the return on investment is not as high as expected.
See why 25 investors see a2 Milk as 11% undervalued.
The valuation work behind this story uses a 7.41% discount rate to bring those future earnings assumptions back to today. It leans heavily on forecasts for revenue of NZ$2.4b and earnings of NZ$310.7m by 2029, paired with a future P/E of 27.3x that remains well above the current food industry averages cited in the narrative.
That combination puts the narrative fair value at NZ$9.38 per share, only modestly above the current NZ$8.39 market price, even though the internal Simply Wall St DCF view flags a much larger gap to an estimated future cash flow value of NZ$18.33. For you as an investor, the key question is how much weight to place on those growth and margin paths when the consensus target sits only 6.3% above spot.
Result: Fair Value of NZ$9.38 (UNDERVALUED)
Still, two things could upend that 10.5% undervalued story: stronger than expected China and U.S. growth, or recall and legal issues weighing more heavily than forecast.
Find out about the key risks to this a2 Milk narrative.
Another View: a2 Milk Looks Expensive on Earnings
On a simple earnings yardstick, a2 Milk looks rich. The current 29x P/E compares with 11.6x for peers, 14.9x across global food stocks, and a fair ratio of 18.4x. That gap raises a practical question for you: Is the premium a cushion, or a source of downside risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around a2 Milk’s premium P/E, discounted cash flow value, and narrative fair value leave plenty of room for your own judgment. Consider acting sooner rather than later by weighing both the upside and the downside, then check the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond a2 Milk?
Do not stop with a single stock story. Broaden your watchlist quickly using targeted screeners that surface clear opportunities you might otherwise overlook.
- Target potential bargains with strong fundamentals by reviewing the 191 high quality undervalued stocks that meet strict quality and valuation filters.
- Prioritise stability and capital strength by scanning the list of solid balance sheet and fundamentals (203 results) to focus on businesses with room to handle shocks.
- Spot future winners early by checking the 618 high quality undiscovered gems before attention and trading volumes crowd the best ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com