
RWE (XTRA:RWE) Wins Silver Maple Lease Case, Is The Upside Already Priced In?
A recent court decision in Michigan has given RWE (XTRA:RWE) clear control over key land leases tied to its Silver Maple Solar project, sharpening investor focus on the group’s expanding renewables pipeline.
RWE’s shares trade at €59.04 after a 1-day share price return of 1.93% and a 7-day share price return of 1.90%, while a softer 30-day move contrasts with a 25.86% year-to-date share price return and a 47.17% 1-year total shareholder return. This performance has coincided with increased attention on renewables projects and corporate moves such as its participation in bidding for Uniper.
Spot opportunities around RWE’s renewables push by scanning a curated set of grid and clean-power enablers through the 41 power grid technology and infrastructure stocks.Bulls point to RWE’s court win, renewables push and strong 1-year shareholder return. Bears question how much of that is already in the price. The valuation work has to break that tie.
Most Popular Narrative: 13.6% Undervalued
RWE closed at €59.04, while the most followed narrative pegs fair value closer to €68.33, which puts the focus firmly on how contracted and regulated income could reshape the story.
Ongoing improvements in the business mix as RWE increases its majority stake in the regulated German transmission operator Amprion to about 58%, targets a return on equity of more than 8% in grids, secures more than 15 gigawatts of capacity payments and over 1.1 gigawatts of new PPAs, and develops high demand data center sites with potential power and infrastructure solutions, are expected to raise the share of contracted and regulated cash flows. This can support higher net margins and more predictable earnings over time.
See why 70 investors see RWE as 14% undervalued.
Result: Fair Value of €68.33 (UNDERVALUED)
Still, RWE’s story can change quickly if capital recycling stalls or policy support for auctions and capacity mechanisms slips, which would leave that €42b program harder to fund.
Find out about the key risks to this RWE narrative.
Another View: RWE And The DCF Gap
The analyst narrative frames RWE as 13.6% undervalued versus a €68.33 fair value, yet the Simply Wall St DCF model points the other way. On that cash flow view, the share price of €59.04 sits well above an estimated value of €31.76, which implies the stock screens as expensive instead.
Those two signals pull in opposite directions, so the question for you is simple: Which set of assumptions feels closer to how RWE will actually earn and reinvest cash over the next decade.
Look into how the SWS DCF model arrives at its fair value.
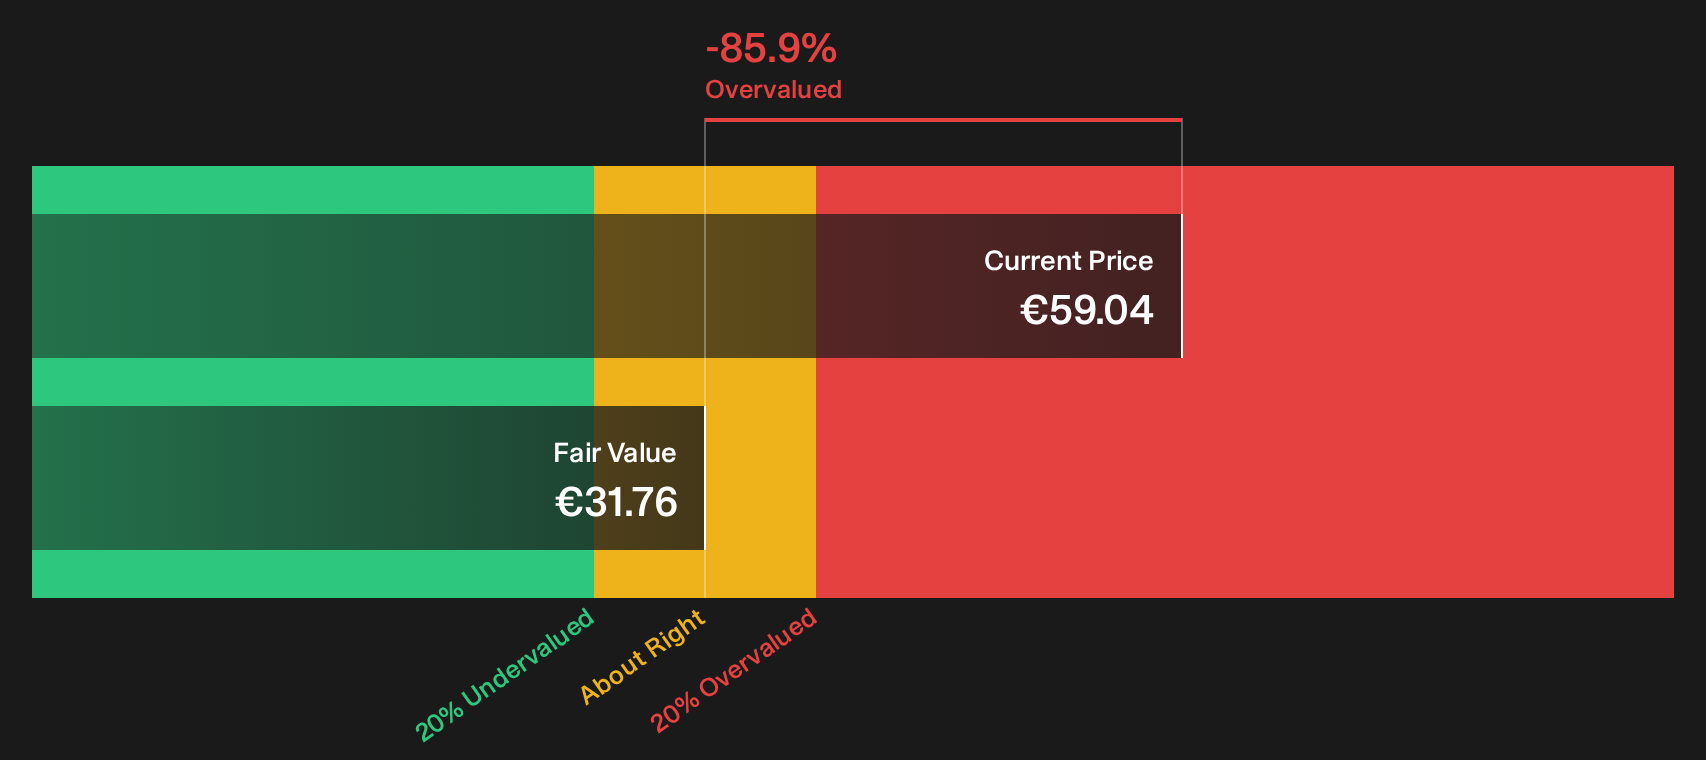
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RWE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around RWE’s value and risk profile do not need to be confusing if you go straight to the underlying data and walk through it yourself. To see both sides of the story in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond RWE?
Do not stop with one stock. Broaden your opportunity set with targeted screeners that surface companies matching the kind of risk and reward profile you want.
- Target resilient cash generators by reviewing companies with consistent payouts through the 214 dividend fortresses.
- Hunt for mispriced opportunities by focusing on financially robust businesses that appear out of favor in the 191 high quality undervalued stocks.
- Spot potential early movers by filtering for strong fundamentals that the market has not fully priced in through the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com