
How Raised Revenue Forecast At Autodesk (ADSK) Has Changed Its Investment Story
- Autodesk announced that longtime executive Diana Colella has been appointed executive vice president of its architecture, engineering and construction segment, succeeding retiring leader Amy Bunszel, and she will also continue to oversee the Media & Entertainment unit.
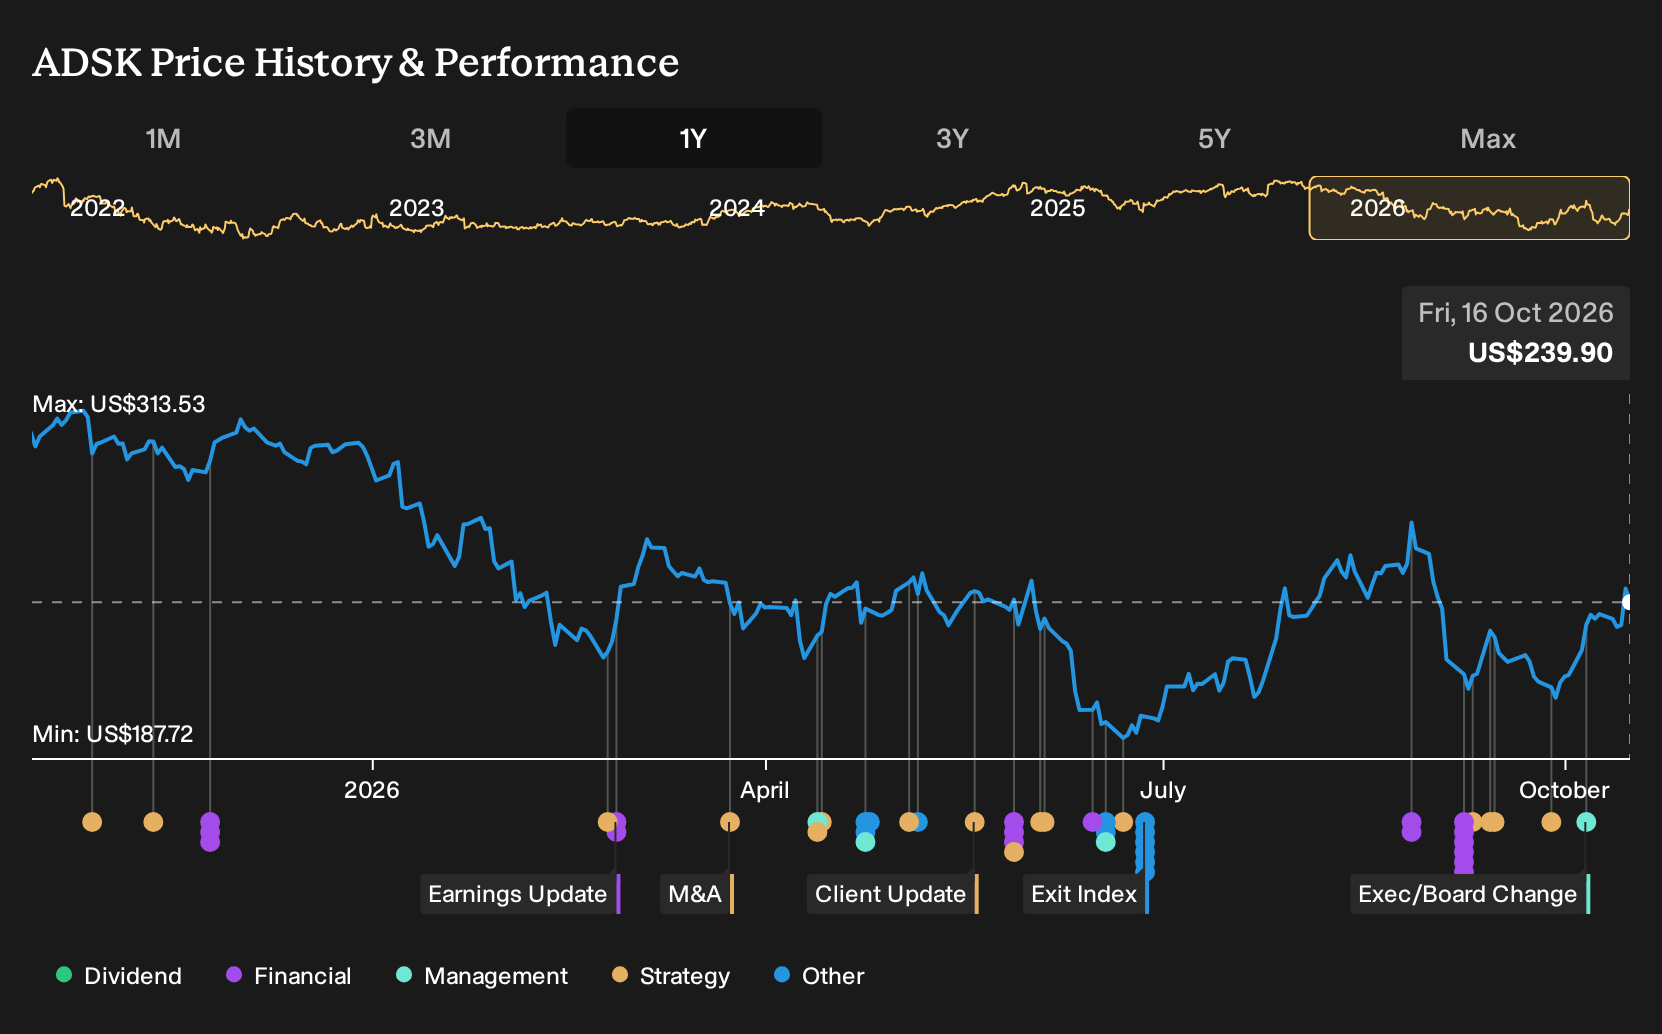
- The company raised its revenue forecast for the fiscal year ending January 2027 to a midpoint of US$8.32b, and management cited confidence in demand for its AEC and AI focused cloud platforms while the operating margin outlook is set at 26.0%.
- This article examines how Autodesk's updated revenue outlook influences the investment narrative around its AI driven, cloud centric design platforms.
Autodesk Investment Narrative Recap
To stay interested in Autodesk, you need to believe its push into AI infused, cloud based AEC workflows can keep deepening customer reliance on Forma, Revit and Civil 3D while the new transaction model settles in. The raised revenue outlook to a midpoint of US$8.32b and 26.0% operating margin guidance frame the near term bar for execution.
The key short term swing factor remains adoption and monetization of the AEC industry cloud and AI features without disrupting existing desktop spend. The main risk is that sales reorganization or transitions such as the AEC leadership change slow new ACV or Forma uptake, which would make that updated outlook harder to achieve.
The appointment of Diana Colella to lead the AEC segment while still overseeing Media & Entertainment is the announcement that matters most for this story. AEC is Autodesk's largest industry business and the focal point for Forma, so investors are watching whether leadership continuity keeps product roadmaps and go to market plans aligned.
Colella's track record on Flow and AI driven tools in Media & Entertainment ties directly to the core catalyst analysts focus on, which is broader adoption of Autodesk's cloud platforms and automation features. The operational question is whether she can integrate AI, Forma and traditional desktop products cleanly enough that customers see less friction and higher value, rather than complexity and switching risk.
Autodesk Analyst Expectations Underpinning The AI Story
Autodesk's narrative projects US$10.7b revenue and US$2.6b earnings by 2029, which assumes revenue expanding at 11.2% a year and an earnings increase of about US$1.0b from US$1.6b today.
Learn how Autodesk's fair value points to a 28% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate angle treats AI monetization risk as the main worry. The most cautious Autodesk analysts were pencilling in about US$10.6b of revenue and US$2.5b of earnings for 2029, slightly below consensus, before this leadership news. That lower bar reflects concern that AI features may take longer to translate into billable usage. It shows how far opinions can spread, so consider both the more optimistic and the more cautious forecasts before deciding how this update might reshape your own view.
Explore 6 other Autodesk fair value estimates, including one that suggests it could be worth just $238.78.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgement.
- A great starting point for your Autodesk research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Autodesk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Autodesk's overall financial health at a glance.
Looking For More Investment Ideas Beyond Autodesk?
If Autodesk has sharpened your focus on where AI, cloud and recurring revenue models meet, it can help to line it up against other opportunities that match your risk tolerance and time horizon. The Simply Wall St Screener gives you a structured way to compare different types of businesses side by side, using the same consistent data set and visual tools.
- If you want potential value with quality filters in place, start by scanning 33 high quality undervalued stocks that may align better with your preferred price and fundamentals mix.
- For readers who care more about resilience and capital preservation, narrow your search to companies in the 32 resilient stocks with low risk scores and see which businesses score well on stability.
- If you prefer balance sheets that can better absorb shocks, review the list of solid balance sheet and fundamentals (25 results) to quickly spot businesses with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com