
3 Australian Defensive Stocks With ROE At Least 22%
US interest costs have reached a record US$1t a year, reminding investors how brutal high borrowing can be for anyone with a weak balance sheet. That backdrop puts financially solid Australian companies in a different light. Low leverage and strong cash positions can offer resilience when money stays expensive. This article highlights three low risk Australian stocks from our quality screen that aim to provide that kind of foundation.
The three examples in this piece are only a sample of what screens well for balance sheet strength, as the full Low Risk Leaders filter surfaced 3 more companies with equally compelling narratives that are not covered below. To identify your own foundations and analyze them against the Low Risk Leaders criteria, head straight into the Low Risk Leaders screener.
Aristocrat Leisure (ASX:ALL)
Overview: Aristocrat Leisure is a global gaming technology group whose Aristocrat Gaming division supplies regulated casino machines and systems that underpin recurring cash flows.
Operations: Aristocrat generates about A$4.1b from Gaming, A$1.7b from Product Madness and A$535 million from Aristocrat Interactive segments.
Market Cap: A$37.7b
Aristocrat Leisure matters in a Low Risk Leaders context because the regulated Gaming arm combines durable machines with service contracts that can underpin consistent cash generation.
"Regulation presents another significant hurdle. Gaming manufacturers must satisfy complex licensing and compliance requirements across multiple jurisdictions, each with its own technical standards and approval processes."
The real test for Aristocrat’s low risk profile will come from how one unseen pressure eventually feeds through to pricing power and margins.
Regulation is only part of the story. The full narrative for Aristocrat Leisure unpacks how Aristocrat Leisure’s cash engine, capital discipline and hidden pressure points could be quietly reshaping its risk profile.

Monadelphous Group (ASX:MND)
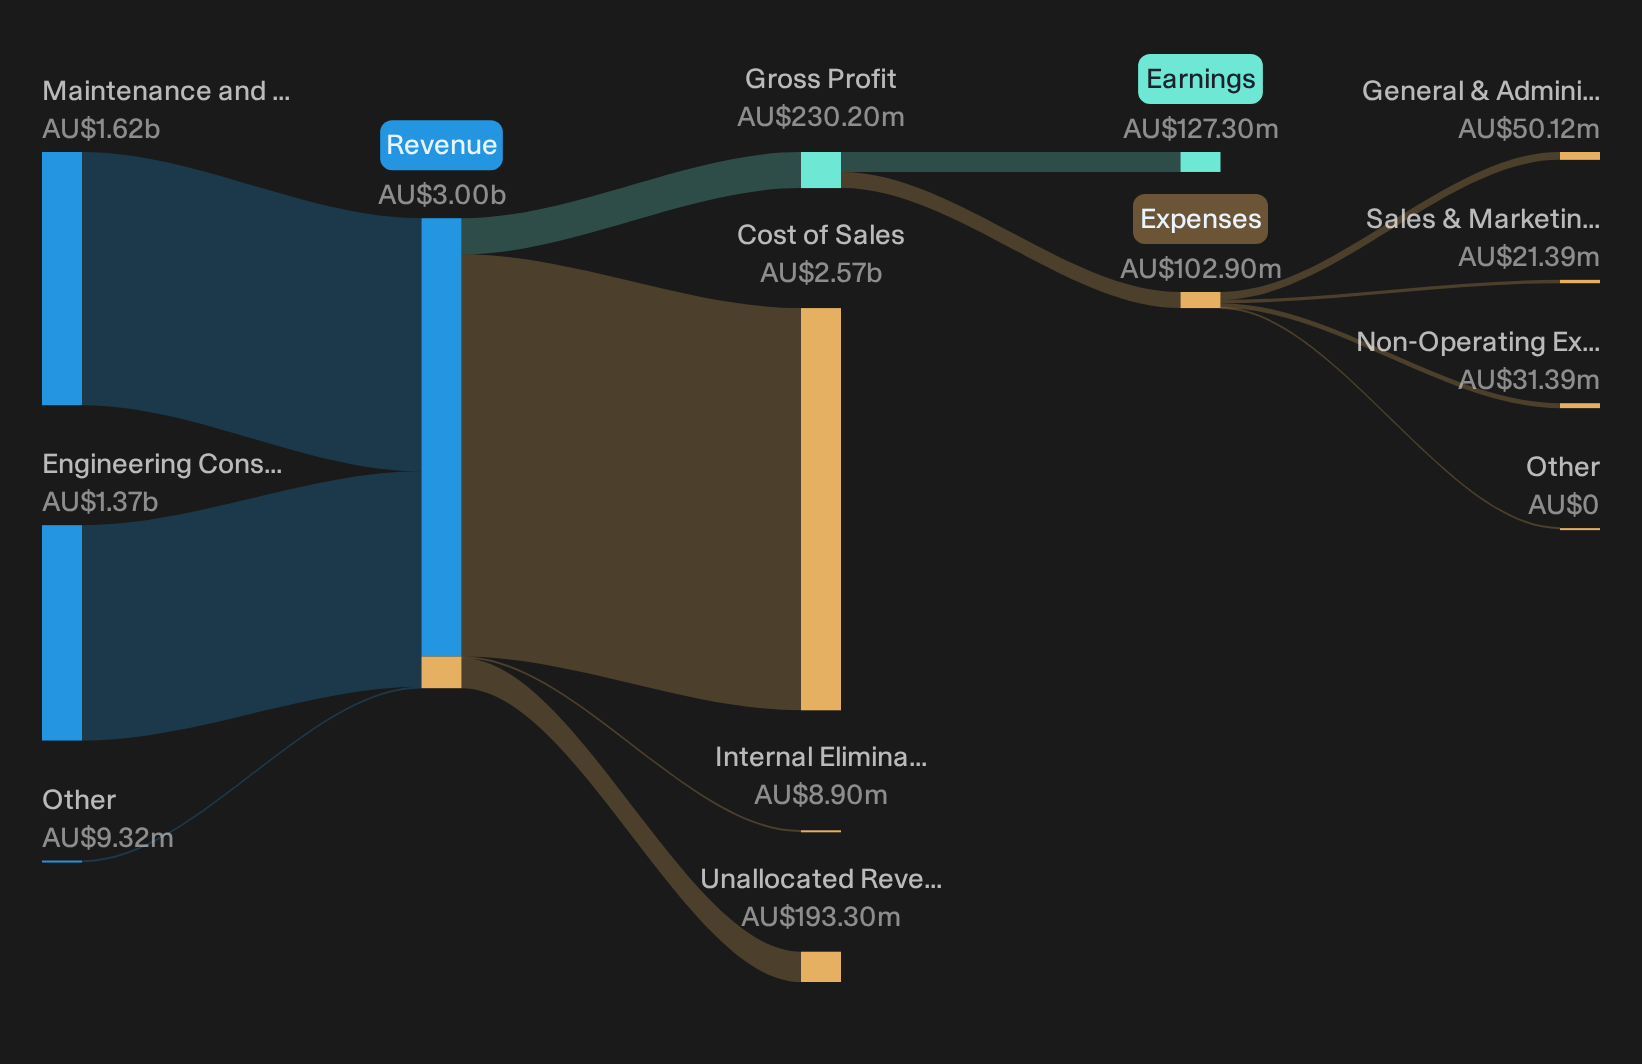
Overview: Monadelphous Group is an engineering contractor that builds and maintains heavy infrastructure, resources and renewable energy projects across Australia and nearby regions.
Operations: Monadelphous generates about A$1.4b from Engineering Construction and A$1.6b from Maintenance and Industrial Services, mostly from Australian projects.
Market Cap: A$2.9b
Monadelphous Group brings a different flavour of resilience to Low Risk Leaders. Structural concrete and inground infrastructure work provide long dated, contract backed cash flows that pair well with a strong balance sheet.
"Accelerating investment in decarbonisation and renewable energy infrastructure is now translating into tangible contract wins and a growing pipeline, as evidenced by record awards secured by Zenviron and new high-voltage services capability."
The real swing factor for Monadelphous is how pressure on project timing and client spending ultimately filters through to margins and cash generation.
That pressure point is exactly what the full narrative for Monadelphous Group unpacks, showing where Monadelphous Group could see margins decoupling from headline contract wins.
Codan (ASX:CDA)
Overview: Codan designs and supplies secure communications systems for governments and security clients, alongside metal detectors for consumers, miners and demining projects worldwide.
Operations: Codan generates about A$506 million from Communications and A$362 million from Metal Detection, with sales spread across the US, UAE and other regions.
Market Cap: A$11.4b
Codan fits the Low Risk Leaders theme through its communications arm. Mission-critical radio and command systems serve institutional buyers on recurring, contract based supply.
"Heightened geopolitical tensions, increased defense spending, and the need for resilient communications infrastructure, especially in light of remilitarization and growing demand for unmanned systems, are expanding Codan's customer base and forward order book in defense and public safety, driving both near-term and long-term revenue growth."
What really matters now is how one emerging pressure on Codan’s communications margins ultimately shapes the durability of that low risk foundation.
That pressure is exactly what the full narrative for Codan unpacks, revealing where Codan’s defense demand could be masking concentration risk and where the next leg of growth might emerge.

Seeking Alternatives Before Everyone Else
Fresh ideas move fast. Once momentum builds, early entry points can vanish as prices start rising and attention chases the breakout. Identify under the radar setups while it matters and act now.
- Capture income ideas with staying power by running a quick pass through the 4 dividend fortresses before yields change as more investors participate.
- Track early movers in automation by scanning the curated 92 robotics and automation stocks while many of these opportunities are still flying under the radar.
- Evaluate potential opportunities in the next energy upgrade cycle by filtering through the hand picked 41 power grid technology and infrastructure stocks while momentum is still developing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com