
Groupe Dynamite And 2 Other Canadian Cash Flow Stocks
High interest rates are reshaping which businesses can handle expensive debt and still fund AI, energy and infrastructure projects. That pressure is pushing investors toward Canadian companies where cash coming in looks strong compared with the price of the stock. This article walks through three ideas from a cash flow based value screen, showing where discounted share prices may not fully reflect the underlying cash engines.
The three stocks below are just a starting sample from this cash flow focused idea, and the full screen surfaced 5 more companies with equally detailed stories that are not covered here. To see the wider field, identify patterns, and analyze which situations fit your own checklist best, go straight to the Undervalued Stocks Based On Cash Flows screener.
Groupe Dynamite (TSX:GRGD)
Groupe Dynamite leans on its Garage and Dynamite banners to turn store and online fashion sales into the kind of recurring cash flows that underpin this undervalued cash flow screen. That makes it a useful test case for how retail earnings power gets priced.
Groupe Dynamite is a women’s fashion retailer whose Garage and Dynamite brands sell apparel and accessories across stores and e-commerce sites. These activities generate about CA$1.49b from retail apparel, with the stock valued at roughly CA$6.57b today.
"Customer response to elevated product, brand heat and reduced markdowns, along with strong pricing power and AUR gains, points to a stronger value perception that can help maintain gross margin and support earnings."
What happens if a single pressure point in that cash engine shifts and investors rethink how durable those current profit levels really are?
If that profit engine proves more durable than the market expects, the full narrative for Groupe Dynamite describes how sentiment, store economics and pricing power could be decoupling from today’s valuation.

Stantec (TSX:STN)
Stantec plugs directly into the cash flow theme through its water and infrastructure design work, where long contracts and ongoing project management can turn complex engineering into steady fee streams.
"Demand for infrastructure upgrades, water/wastewater treatment, energy transition, and climate adaptation projects remains exceptionally strong globally, with double-digit organic growth and a $7.9 billion backlog, which the company notes as positioning it for sustained revenue expansion in line with multi-decade trends toward urbanization and aging infrastructure."
What matters next is how one pressure on those long contracts shapes the balance between rising demand and future profitability.
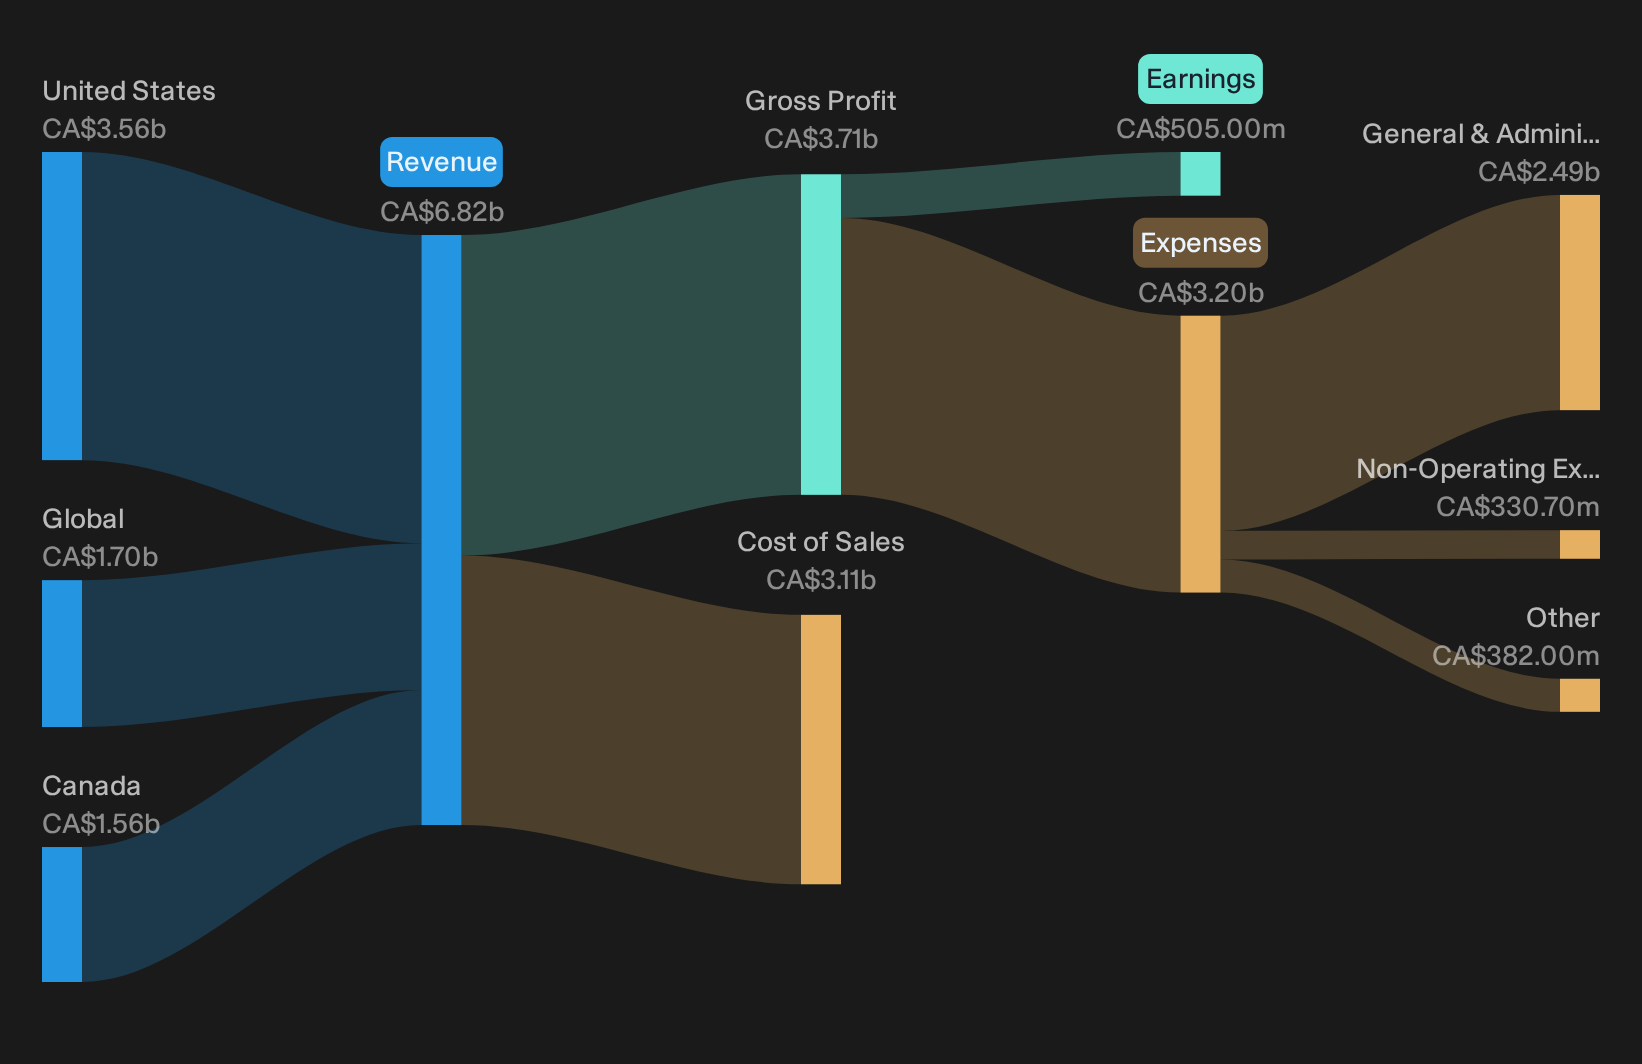
Stantec is a global design and consulting firm focused on infrastructure, water systems, environmental services, and buildings, with water and municipal engineering tying it most tightly to the undervalued cash flow theme. It generates about CA$3.56b from the United States, CA$1.56b from Canada, and CA$1.70b from global work, and the stock is valued around CA$11.1b today.
If that pricing power on long contracts keeps shifting, the full narrative for Stantec maps how backlog, fee rates and capital intensity could be quietly reshaping Stantec’s long term cash profile.
Altius Minerals (TSX:ALS)
Altius Minerals is built around a Mineral Royalties arm that converts production at 11 mines into recurring payments, which is exactly the sort of cash stream this screen focuses on, while smaller Renewable Royalties and Project Generation units widen its exposure to future projects.
Altius Minerals generated about CA$79 million from Mineral Royalties, around CA$20 million from Renewable Royalties and a small contribution from Project Generation, with a CA$3.38b market value placing it firmly in mid cap territory on this cash flow oriented list.
What grabs attention with Altius Minerals is how a royalty focused model can give you exposure to multiple commodities and renewable projects while keeping the emphasis on cash flowing back to shareholders.
"The Great Bay Renewables portfolio now includes 16 operating projects and 15 under construction, and recent investments like the 311 megawatt Coles Wind project plus an increased 50% interest in GBR create more contracted electricity royalty streams."
What really matters next is how one underlying shift in those royalty contracts affects the balance between dependable cash inflows and long term growth potential.
If that trade off between dependable royalties and future upside is what you care about, the full narrative for Altius Minerals unpacks where Altius Minerals’ cash story could be accelerating next.

Seeking Alternatives Before The Crowd Moves
Fresh idea flow can slow once momentum builds and prices start rising quickly. Scan these under the radar lists while it matters, before potential entry points change. Consider reviewing them now.
- Review 3 dividend fortresses that focus on payout strength while the yields still compare favorably with today’s interest rate backdrop.
- Explore 10 high quality undiscovered gems where smaller, under-followed businesses may remain mispriced for now, before broader coverage potentially changes market attention.
- Assess 41 power grid technology and infrastructure stocks aligned with long term grid upgrades, while many of these infrastructure-related names may still receive relatively limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com