
Nebius Stock Faces Funding Pressure As AI Cloud Debt Concerns Spread
- Nebius Group has been securing very large AI cloud contracts and customer prepayments, partnering with Palantir and expanding its own data centers while carrying sizable debt and cash balances to fund that buildout.
- Sector wide scrutiny of neocloud financing, including warnings on debt costs and potential AI infrastructure impairments, is putting extra attention on how Nebius converts contracted demand and power deals into durable cash generation.
- We will now look at how Nebius Group's financing pressures and sector wide funding stress reshape the broader investment narrative.
Scan how financing pressures are affecting AI infrastructure, and compare Nebius Group with peers using a curated list of 55 AI infrastructure stocks to see which companies carry similar risks and balance sheet setups.
Nebius Group Investment Narrative Recap
To own Nebius Group, you need to believe the AI infrastructure build can convert huge contracted demand into steady, high quality cash flow before interest costs bite too hard. The near term catalyst lies in getting new data centers online and utilized, then proving that the reaffirmed 2026 revenue and 40% adjusted EBITDA margin targets still hold weight under tighter funding conditions.
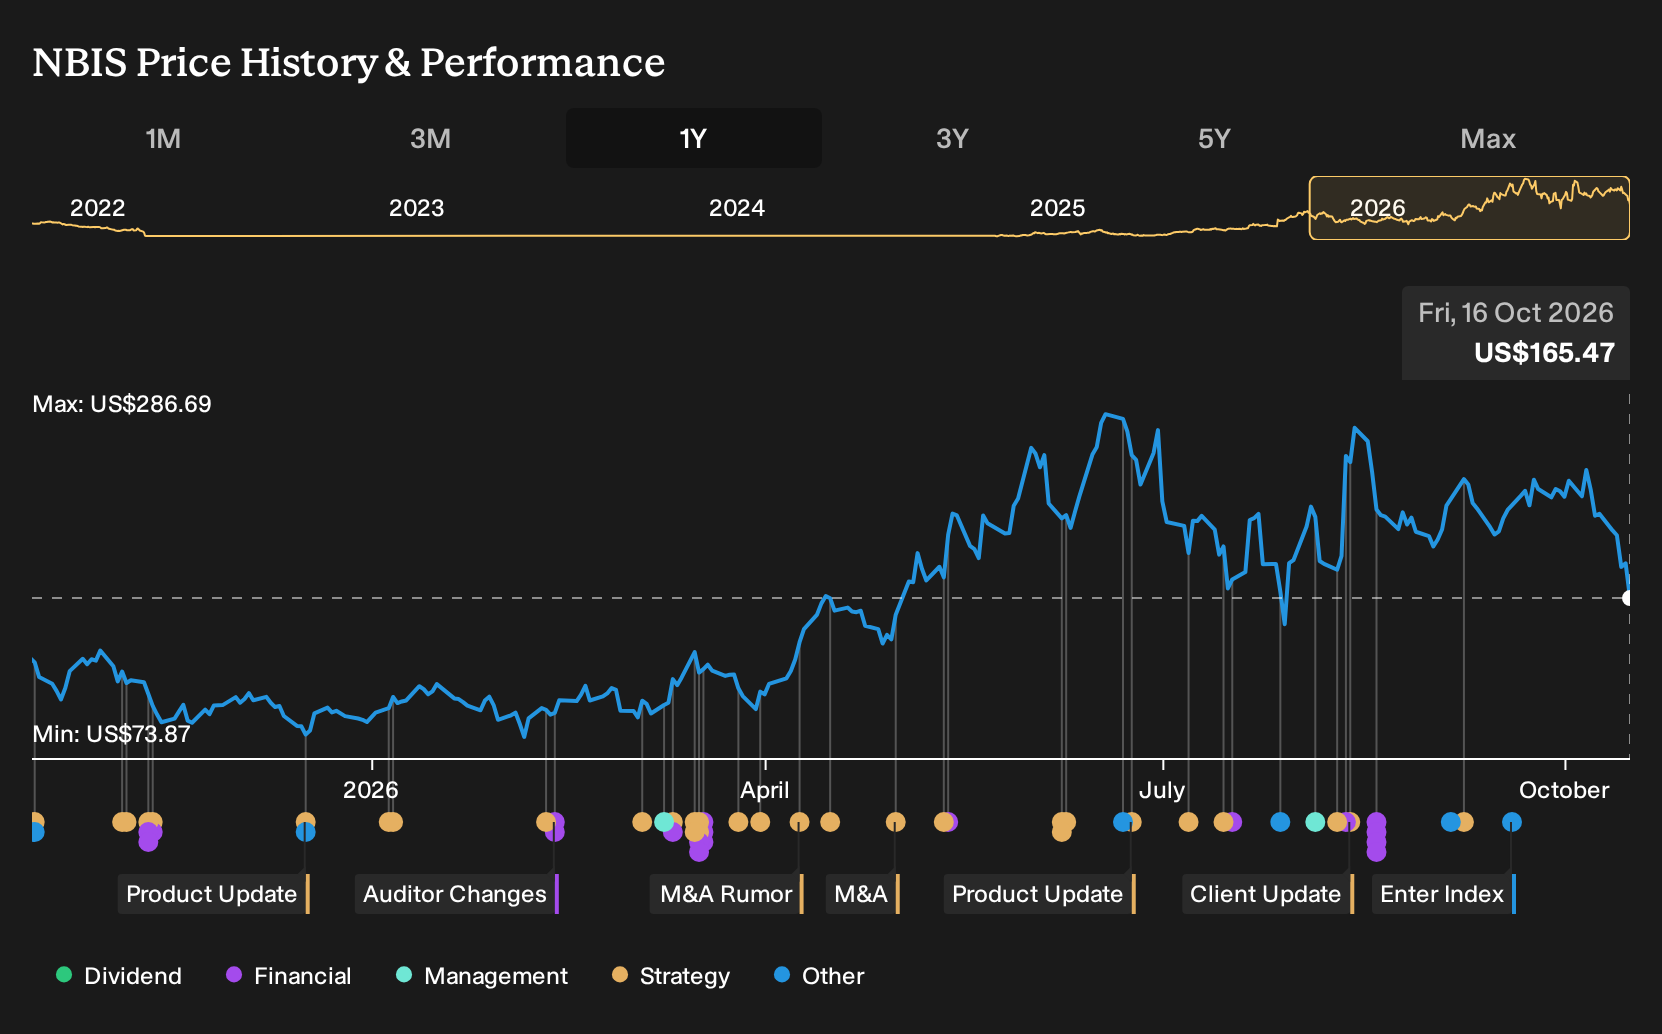
The biggest near term risk is straightforward. Rising debt costs are colliding with a capital hungry buildout and sector wide doubts about AI overbuild and impairments. Recent pressure on neocloud bond yields and Nebius’s share price mainly sharpens scrutiny on financing terms rather than changing the core operating thesis.
The partnership with Palantir is the announcement that really matters here. It ties Nebius Group’s GPU capacity directly to commercial AI workloads, which helps bridge the gap between headline contract wins and actual recurring usage on its clusters. That kind of demand linkage becomes crucial when investors are questioning whether all this power and hardware is fully monetized.
As funding costs rise and Gartner flags possible future AI infrastructure impairments, this Palantir tie up sits at the intersection of risk and catalyst. Stronger real world deployment of Nebius cloud capacity can support the case that customer prepayments and existing contracts reduce reliance on higher cost borrowing, while weak execution would leave the balance sheet and P/S multiple more exposed.
Nebius Group's current analyst script points to revenue of $30.0b and earnings of $2.6b by 2029, built on forecasts of 180.7% yearly top line growth and an earnings step up from $42.4m today. This implies earnings would need to increase by roughly 60x to meet that 2029 consensus bar.
Discover how Nebius Group's fair value indicates a 76% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Nebius Group’s funding access as the real catalyst. Before this week’s financing shock, the bullish camp was modeling revenue growth of 214.1% a year and earnings of about $1.6b by 2029. You now need to decide whether those pre news assumptions still feel realistic.
Explore 12 other Nebius Group fair value estimates, including one that suggests potential upside of as much as 148% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and consider multiple viewpoints.
- A great starting point for your Nebius Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking for more investment ideas beyond Nebius Group?
Once you have a view on Nebius Group, it can help to widen the lens and compare it with other opportunities that fit your style, using the Simply Wall St Screener as a starting point.
- If you want potential growth without stretching your budget, scan early stage opportunities with 14 elite penny stocks with strong financials that already show stronger fundamentals than many peers.
- For investors who care most about quality at a sensible price, narrow the field to companies on our 33 high quality undervalued stocks that pair balance sheet strength with solid cash generation.
- If resilience matters more than excitement for your portfolio, focus on businesses in the 32 resilient stocks with low risk scores that score well on stability and financial risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com