
MP Materials (MP) Expands Its Rare Earth Buildout, Is The Valuation Gap Too Wide?
The United States is lining up as much as US$100b in loan support for critical minerals, and MP Materials (MP) sits directly in that policy spotlight through its rare earth mining and magnet operations.
Despite the policy tailwind and expansion plans with Apple and the Department of Defense, MP Materials’ share price has come under pressure, with the 1-month share price return down 18.0% and the year-to-date share price return down 26.9%. The 3-year total shareholder return of 133.1% still points to a very strong longer term outcome compared with the much weaker 1-year total shareholder return, which is down 50.3%.
Scan beyond MP Materials to compare it with 32 best rare earth metal stocks, which is riding the same push for US-backed critical minerals and rare-earth magnet capacity.
Bulls point to MP Materials’ policy support, vertical build out and long contracts. Bears focus on share price weakness and current losses. Which side does the valuation math lean toward next?
Most Popular Narrative: 45% Undervalued
On the most followed narrative, MP Materials screens as undervalued, with a fair value of $73 against a last close of $40.17, which puts the gap between price and expectations front and center for investors.
The company is expanding its vertically integrated processing and magnet manufacturing capacity with the "10X" plant and a modular recycling facility, which, together with significant CapEx support from Apple and the DoD, is expected to capture more value-added margins and potentially improve net profit and operating leverage as they ramp downstream operations.
See why 202 investors see MP Materials as 45% undervalued.
Result: Fair Value of $73 (UNDERVALUED)
Still, the MP Materials story can change quickly if large customers slow orders or if new magnet and recycling facilities encounter costly delays or performance issues.
Find out about the key risks to this MP Materials narrative.
Another View: What MP Materials’ Sales Multiple Is Telling You
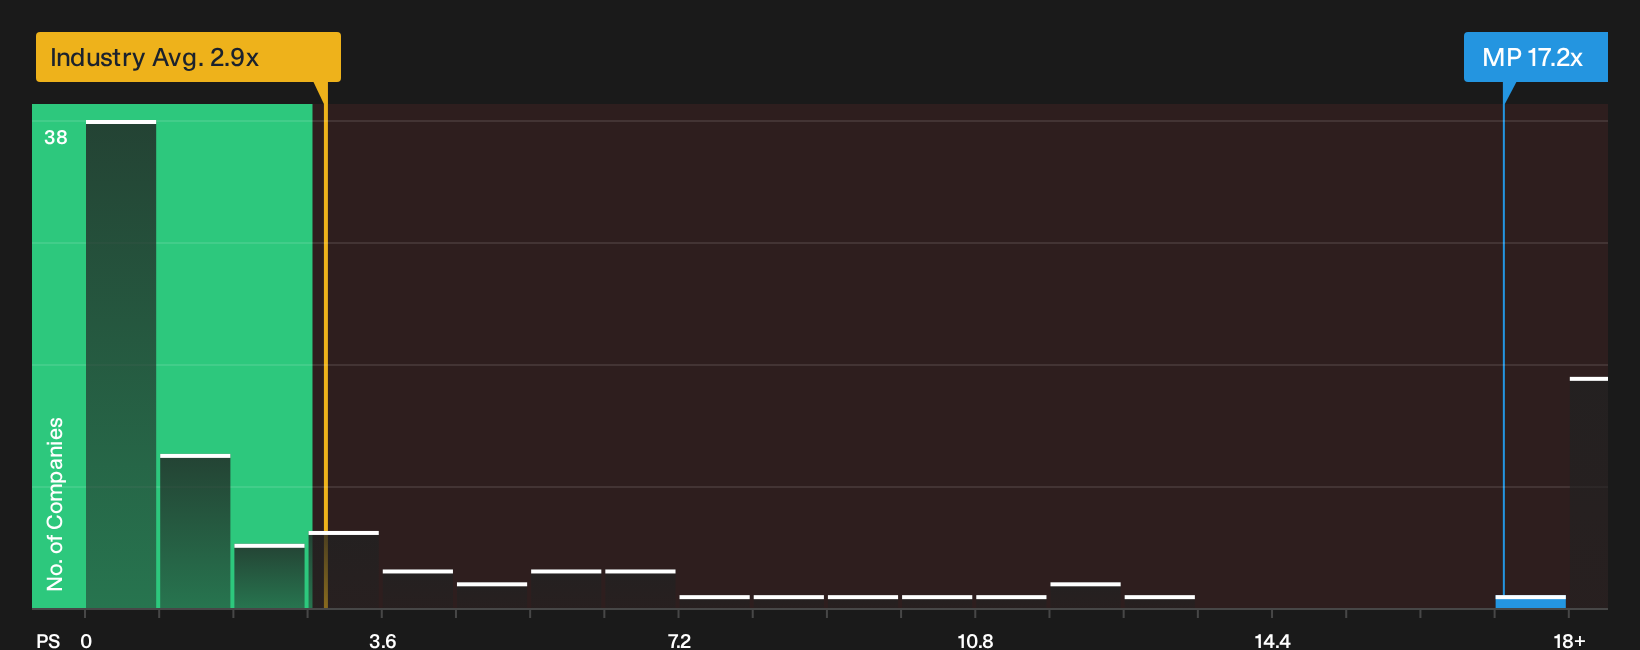
The first valuation pegs MP Materials as deeply undervalued, yet the current P/S ratio of 17.2x tells a tougher story. That sits well above the US Metals and Mining industry on 2.9x, the peer average on 13.3x, and a fair ratio of 6.3x that the market could eventually lean toward. If sentiment keeps tracking those rich multiples instead of the cash flow model, how comfortable are you with that gap?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on MP Materials is clearly split, so move quickly from headlines to hard numbers and weigh the upside case yourself with the 2 key rewards.
Looking for more investment ideas beyond MP Materials?
MP Materials is only one way to position your portfolio. You can use the Simply Wall St Screener to uncover other opportunities that might fit your goals even better.
- Look for potentially underpriced quality by scanning for companies that combine strong fundamentals with attractive valuations using the 33 high quality undervalued stocks.
- Explore possible income streams by focusing on reliable payers screened through the 8 dividend fortresses.
- Concentrate on resilient businesses with sturdier finances highlighted in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com