
How Investors May Respond To Citi (C) Earnings Beat
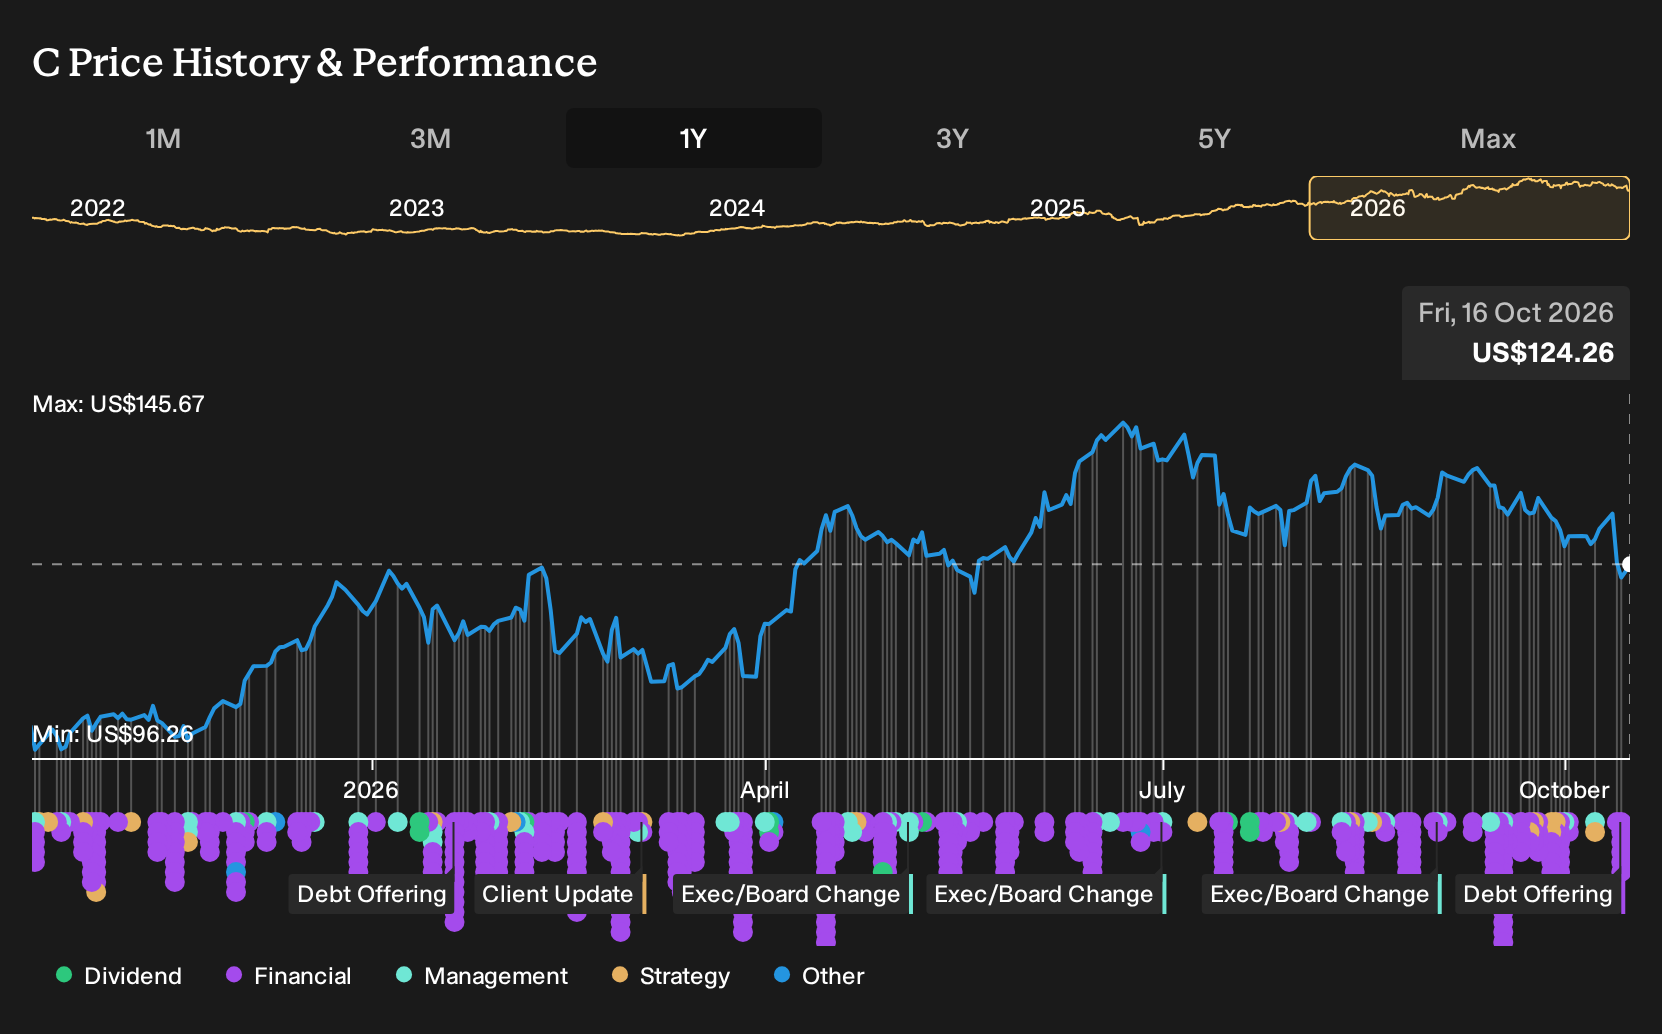
- Citigroup reported its highest third quarter revenue in ten years, with net income of US$5,245 million and improved profitability in services and wealth management, supported by tighter cost control and new senior unsecured fixed rate note issuances across multiple maturities.
- The combination of stronger earnings and targeted funding activity points to Citigroup refining its business mix around services, wealth, and balance sheet efficiency, while continuing a multiyear simplification and restructuring effort.
- Now the focus shifts to how Citigroup's stronger third quarter profitability in services and wealth reshapes the longer term investment narrative we consider.
Scan how Citigroup's latest funding moves compare with other large banks refining their balance sheets by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Citigroup Investment Narrative Recap
To own Citigroup, you need to believe the services, markets, cards and wealth engines can keep throwing off solid earnings while the restructuring and Banamex exit gradually simplify the group. The immediate swing factor is execution in Services and Wealth, which are already supporting higher net income, and whether that strength offsets any moderation in markets revenue or cards losses.
The biggest near term risk remains operational and regulatory. Any control failure around sanctions, cyber, or complex cross border payments could drag on expenses and slow capital returns. The fresh fixed rate funding looks incremental rather than transformative, so it does not materially change the short term risk and reward balance on its own.
The most relevant recent announcement for this funding activity is the third quarter 2026 earnings release. Citigroup reported net interest income of US$16,982 million in the quarter and net income of US$5,245 million, with both figures higher than a year earlier. That context matters when assessing why management is comfortable layering in multiple senior unsecured fixed rate notes across the curve.
Those bonds, with coupons between 5.45% and 7.00% and maturities stretching from 2028 to 2049, sit against a business that is already generating US$16,861 million of net income over the first nine months of 2026. Issuance terms and investor demand for Citi paper feed directly into funding flexibility, which can influence how quickly the bank pursues capital return plans, technology investment, and the Banamex separation from here.
Citigroup's analyst narrative points to US$108.8b in revenue and US$22.4b in earnings by 2029, based on a forecast 9.3% yearly revenue growth rate and an earnings increase of about US$4.5b from the current US$17.9b level.
Uncover why Citigroup's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts lean on a different catalyst. They focus on higher long term compliance and technology spending that could cap Citigroup’s efficiency gains, even with these fresh fixed rate notes in place. Before this news, that group was modeling about US$107.2b of 2029 revenue and US$22.8b of earnings, so their story already looked more cautious. Use that contrast as a reminder that reasonable people can disagree, and explore several viewpoints before deciding how this latest funding round might reshape your own Citigroup thesis.
Explore 4 other Citigroup fair value estimates, including one that suggests it could be worth just $150.71!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Citigroup research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Citigroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Citigroup's overall financial health at a glance.
Looking for more investment ideas beyond Citigroup?
Once you have a view on Citigroup, it helps to compare it with a broader watchlist built around clear themes that match your own risk and return preferences. Use the Simply Wall St Screener to widen the field and test your thesis against other businesses with different balance sheets, income profiles, and dividend policies.
- If you want income to play a bigger role in your portfolio, start with resilient payers by reviewing the 8 dividend fortresses that meet your yield and payout comfort zone.
- For investors who care most about quality at a reasonable entry point, build a shortlist around valuation and fundamentals with the curated 33 high quality undervalued stocks available in the Screener.
- When capital preservation is the priority, stress test your ideas against a 32 resilient stocks with low risk scores that filters for businesses with sturdier financial profiles and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com