
Why BJ's Restaurants (BJRI) Is Drawing Fresh Attention Now
BJ's Restaurants (BJRI) has set a firm date on the calendar, with third quarter 2026 results due after the close on Thursday, November 5, followed by an investor call later that same day.
Recent trading has cooled, with the share price down 12.02% over the past 90 days, even as BJ's Restaurants holds a year to date share price gain of 44.51% and a 1 year total shareholder return of 93.67%. This suggests that earlier momentum has eased while longer term holders have still seen strong gains.
Scan how BJ's Restaurants stacks up against other consumer stocks by reviewing hand picked ideas in the 20 high quality undiscovered gems that have strong fundamentals but remain off most investors' radar.
BJ's Restaurants has cooled off after a strong multiyear run, with the pullback clashing against still upbeat expectations. Is most of the easy upside already in the rearview, or does the current valuation still leave room ahead?
Most Popular Narrative: 21% Undervalued
BJ's Restaurants most followed narrative pegs fair value at $75.43 using a 9.4% discount rate, compared with the recent close at $59.38. This frames the upcoming results against expectations that already assume steady execution on traffic, margins and unit-level returns.
Planned acceleration of new restaurant openings based on a refreshed prototype, following gains in average unit volume, restaurant cash flow and an approximate 240 basis point margin improvement over the past two years, sets BJ's Restaurants up to apply strengthened unit economics to unit growth, which is aimed at expanding systemwide revenue and cash generation.
See why 1 investors see BJ's Restaurants as 21% undervalued.
Result: Fair Value of $75.43 (UNDERVALUED)
Still, the story can break if BJ's Restaurants struggles to expand digital and off premise ordering, or if cost inflation squeezes already modest gross margins.
Find out about the key risks to this BJ's Restaurants narrative.
Another View: BJ's Restaurants Through The P/E Lens
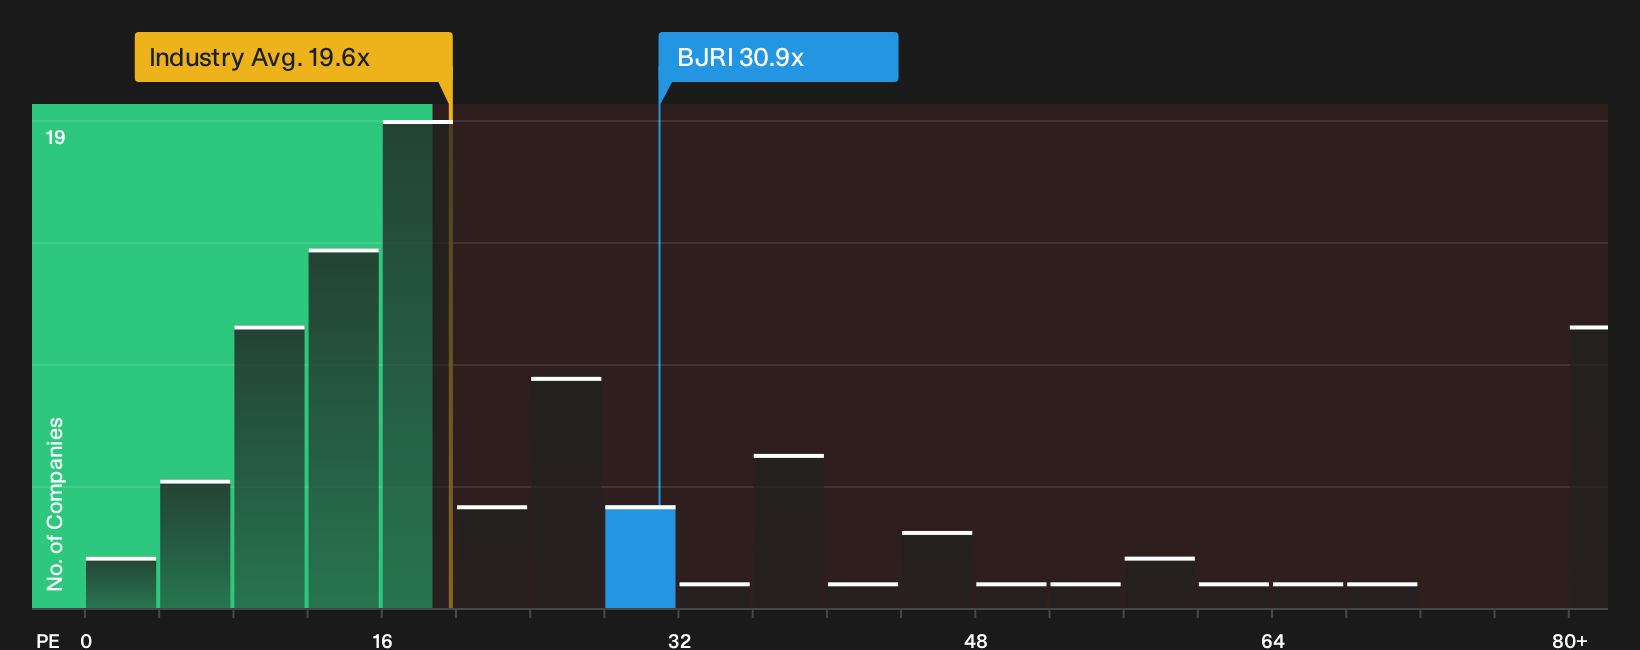
The bullish fair value of $75.43 leans heavily on future earnings. A simple P/E check tells a tougher story. BJ's Restaurants trades around 30.9x earnings, while the US Hospitality industry sits near 19.7x and the fair ratio estimate is also 19.7x. That gap points to meaningful valuation risk if sentiment cools or earnings progress stalls.
Investors weighing that premium may want to see what the numbers imply in detail, then decide whether to wait for a better entry or back the current pricing with conviction, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment mixed across BJ's Restaurants, do not wait for consensus to harden before you check the evidence yourself and see both sides. Balance the concerns and the upside by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BJ's Restaurants?
Do not stop with one stock. Broaden your watchlist with focused idea lists that highlight different strengths, so you keep options open while staying disciplined.
- Target potential mispricing by reviewing companies that screen as strong quality at attractive valuations through the 33 high quality undervalued stocks.
- Build a more resilient core by checking out businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential by scanning lesser known opportunities that still have solid fundamentals via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com