
Learn Why The Bull Case For Cheniere Energy Stock Could Change Following LNG Capacity Expansion
- Cheniere Energy recently reported operational performance and progress on capacity expansions in the U.S. Gulf, while a visit by the U.S. Under Secretary of Energy highlighted Sabine Pass as one of the largest active LNG facilities globally and underlined Louisiana’s role as a leading LNG export hub.
- The combination of rising contracted LNG volumes, an expanding project pipeline, and increased federal attention on high profile assets such as Sabine Pass reinforces Cheniere Energy’s position as a notable U.S. supplier for buyers seeking long term, flexible LNG supply backed by large scale infrastructure.
- The focus now turns to how Cheniere Energy’s investment narrative aligns with this capacity build out and federal spotlight on Sabine Pass.
Scan how Cheniere Energy fits into the broader LNG build out theme by comparing it with a curated 41 power grid technology and infrastructure stocks that could benefit from similar infrastructure spending momentum.
Cheniere Energy Investment Narrative Recap
To own Cheniere Energy, you need to believe its LNG export platform can keep running reliably at high utilization while new Gulf Coast capacity ramps and gets locked into long term contracts. The short term swing factor is execution on Sabine Pass and Corpus Christi expansions, especially getting new trains permitted, built and smoothly integrated into existing operations.
The biggest risk right now sits around volatility in LNG linked derivatives and ongoing regulatory scrutiny. Large fair value swings have already pulled reported earnings away from underlying cash generation, and a federal investigation into a US$370m alternative fuel tax credit could still affect future cash available for shareholder returns.
The recent focus on expanded production capacity at Sabine Pass and Corpus Christi is the clearest link to the current news. Management is bringing Corpus Christi Stage 3 close to the finish line and planning Sabine Pass Phase 1 additions, including Train 7 and a boil off gas reliquefaction unit. Together, these projects increase the physical backbone behind contracted LNG volumes.
For you, the operational question is whether Cheniere Energy can keep filling and optimizing this larger system while derivative swings, high debt and regulatory investigations remain in the background. Progress on debottlenecking projects and reliability upgrades, such as Durasorb LNG MAX roll out, feeds directly into the same catalyst investors are watching: higher effective capacity and steadier output.
Cheniere Energy's current analyst narrative points to forecast revenues of US$25.2b and expected earnings of US$3.2b by 2029, built on an assumed yearly revenue growth rate of 6.4%. That outlook compares with earnings of US$2.9b today, which implies an earnings increase of about US$0.3b by the 2029 estimate year if those projections are met.
Uncover why Cheniere Energy's fair value indicates a 7% potential upside to its current price that could narrow quickly.
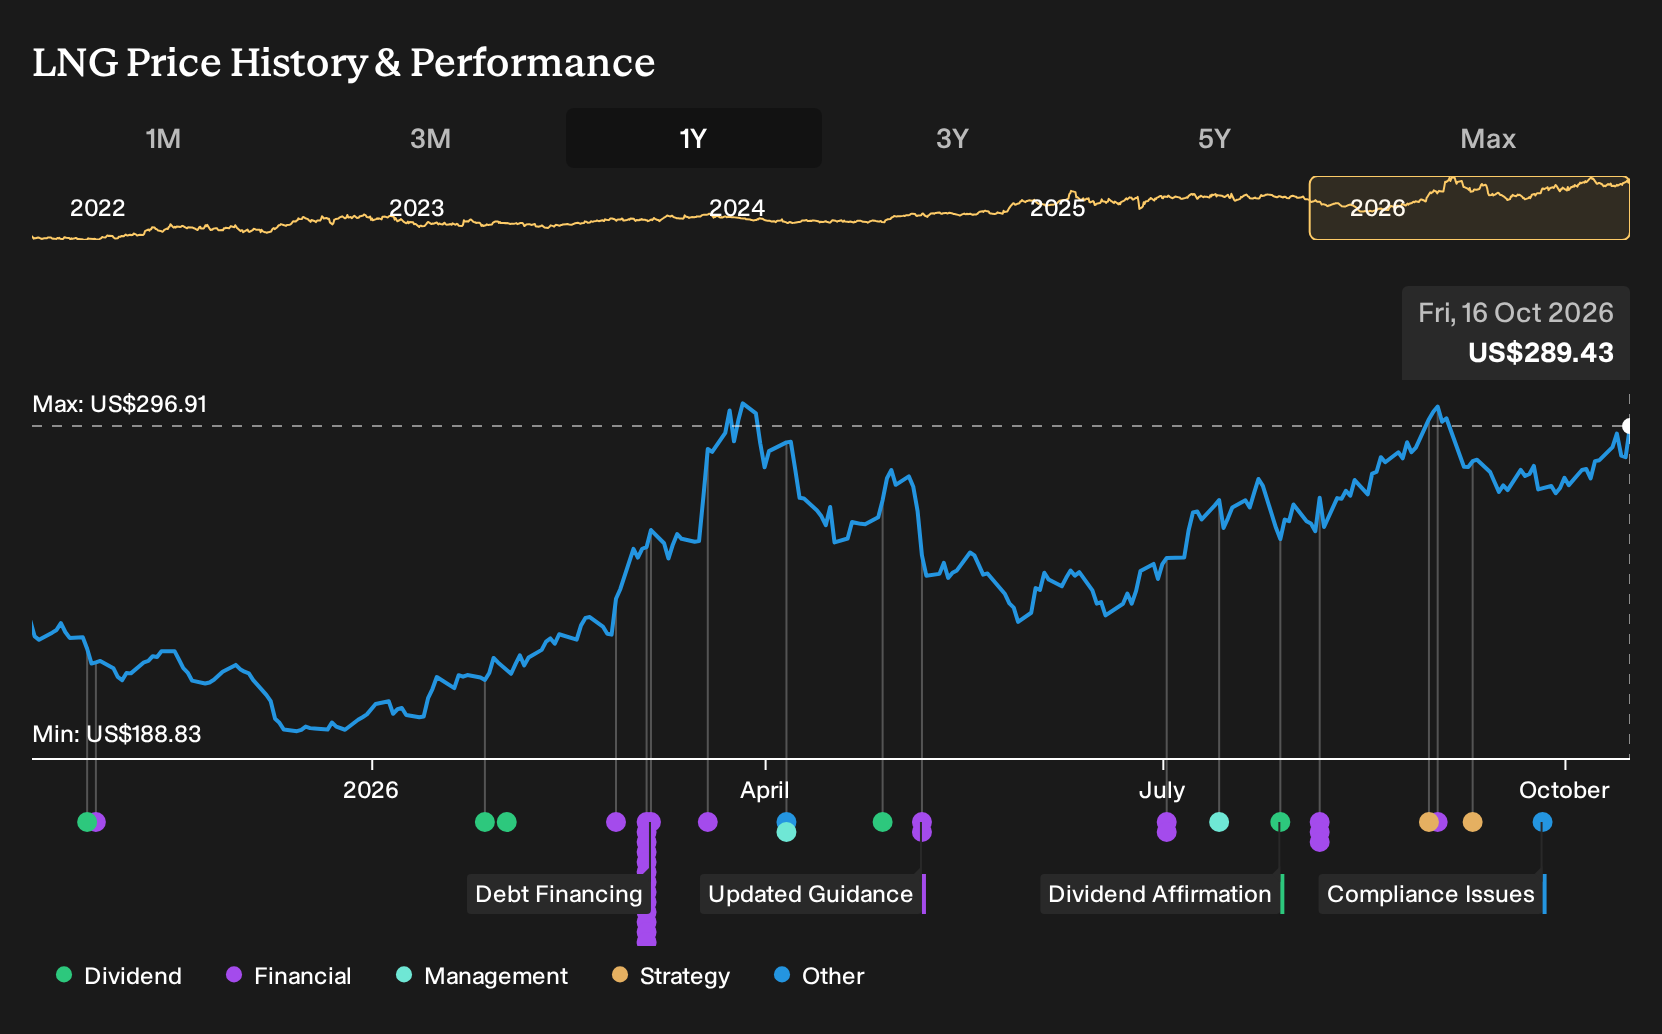
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$126 to about US$321 per share for Cheniere Energy, which shows how far apart retail views can be. Even before the October 2026 LNG headlines, these investors already disagreed widely. When you also consider derivative volatility and regulatory investigations, there is plenty of reason to weigh multiple viewpoints yourself.
Explore 4 other Cheniere Energy fair value estimates, including one that suggests up to 11% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cheniere Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cheniere Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheniere Energy's overall financial health at a glance.
Looking for more investment ideas beyond Cheniere Energy?
Once you have a view on Cheniere Energy, it can help to cross check that thesis against other opportunities that match your risk profile and return goals. The Simply Wall St Screener lets you filter for different types of businesses so you can build a watchlist that fits how you like to invest.
- If you want resilience first and foremost, focus on a 32 resilient stocks with low risk scores that may help you keep drawdowns in check when individual positions move against you.
- For investors who care most about steady cash returns, scan a 8 dividend fortresses that concentrates on companies with higher yields that might support income focused portfolios.
- If you prefer to hunt for potential mispricings, sort through a 33 high quality undervalued stocks that highlights strong fundamentals at valuations some investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com