
Learn Why The Bull Case For Avio (BIT:AVIO) Could Change Following Rocket Motor Production Deal
- Lockheed Martin announced a cooperation agreement with Avio to use Avio USA’s new Virginia facility to expand U.S. solid rocket motor output for Extended Range GMLRS and Precision Strike Missile programs.
- The deal gives Avio a route to monetize more than US$500 million of U.S. propulsion capacity investments and positions Avio USA as a merchant supplier to multiple defense customers, rather than a single prime contractor.
- This article examines how Avio's investment narrative is affected by this Lockheed Martin solid rocket motor production cooperation agreement.
Avio Investment Narrative Recap
To own Avio, you need to believe this is a durable propulsion and launch platforms specialist with enough contract visibility to justify heavy R&D and capital spending. The Lockheed Martin cooperation and Avio USA investments speak to that thesis, but the short term swing factor still looks like execution on Vega C, Vega E and key propulsion milestones.
The biggest risk remains program slippage or cost overruns on those launch and propulsion projects, especially with a backlog already large relative to annual revenue. The Lockheed agreement helps diversify defense propulsion exposure, yet does not remove exposure to contract timing, high R&D intensity or customer concentration in defense and institutional space spending.
The corporate reshuffle on 5 October 2026 matters for this story. Avio appointed independent director Giulia De Martino and refreshed the Nomination and Remuneration Committee while also installing CFO Roberto Carassai as Deputy General Manager Corporate, adding oversight of legal, compliance, ICT, sales governance and general services.
For a business where execution on Vega C, Vega E and long cycle defense propulsion contracts is central to the thesis, this kind of governance and management re wiring is closely tied to your catalyst view. Tighter coordination across finance, investor relations, commercial governance and complex program delivery could help or hinder delivery against that large backlog, which is where both upside and risk live.
What The Current Avio Consensus Is Really Asking You To Believe
Avio's current analyst narrative points to revenues of €746.1 million and earnings of €13.2 million by 2029, built on assumed yearly top line growth of 8.5% and an earnings uplift of about €2.7 million from €10.5 million today.
Uncover how Avio's fair value indicates a 32% potential upside to its current price that may not continue for long.
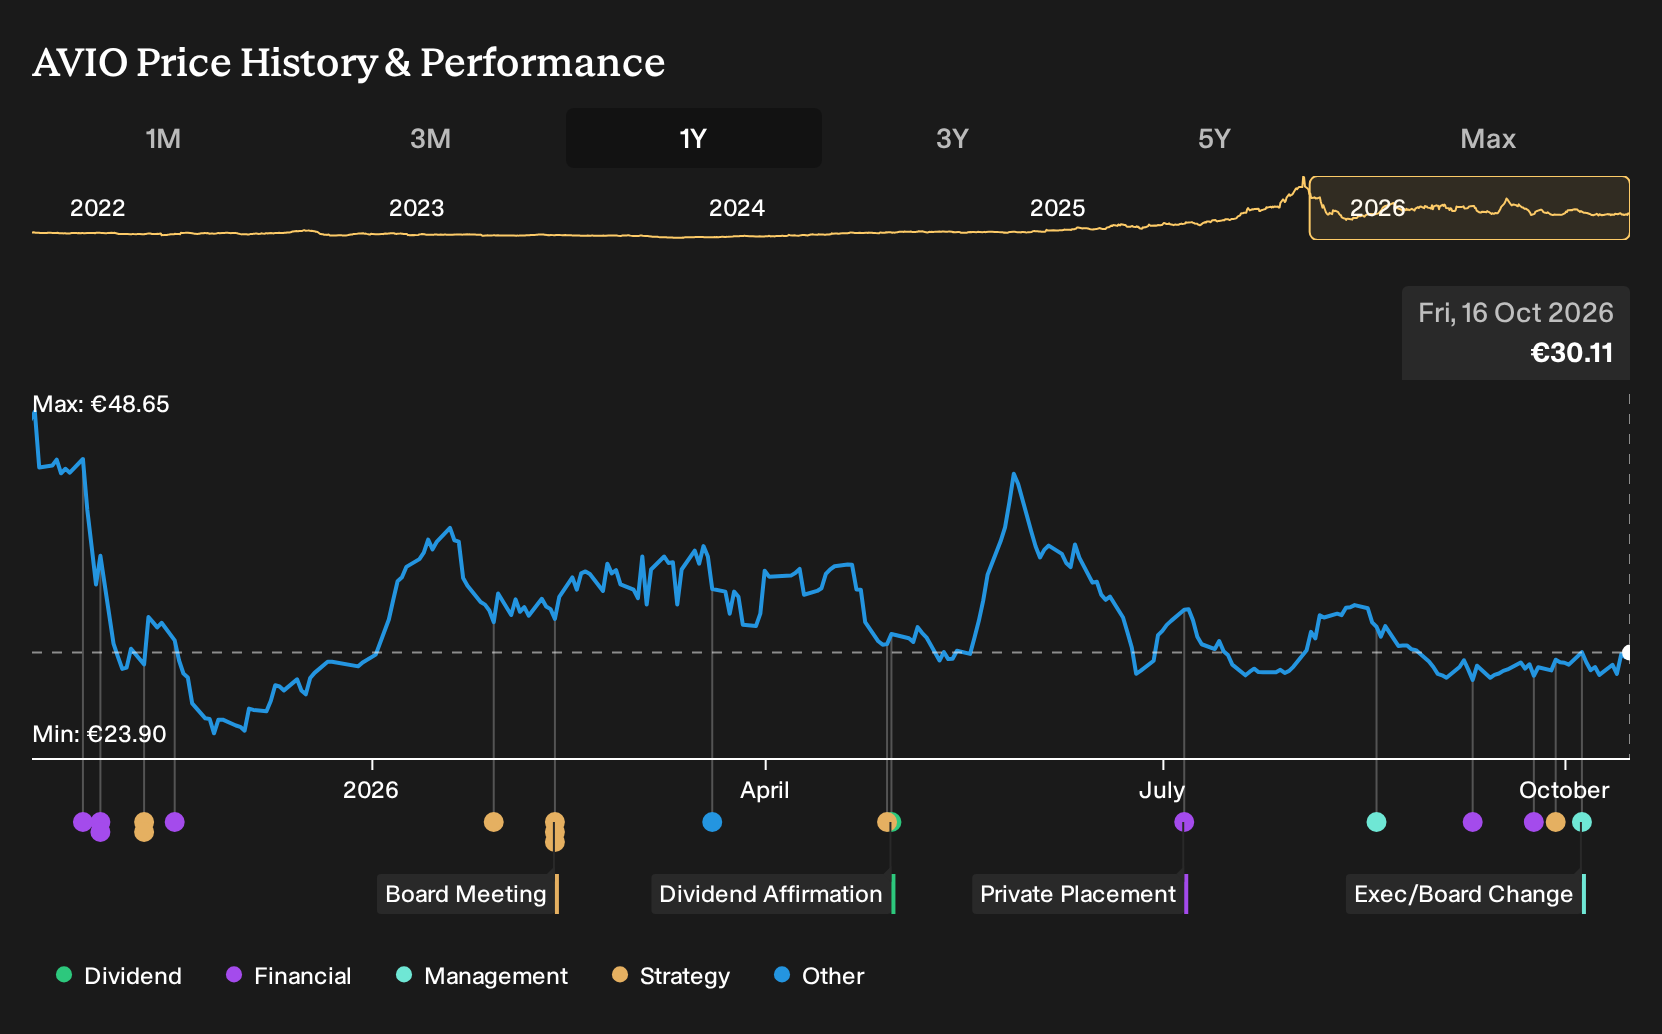
Exploring Other Perspectives
One alternate view focuses on cash strain from Avio’s Virginia build out. The most bearish analysts were estimating revenue of about €769.1 million and earnings near €13.4 million by 2029, compared with €746.1 million and €13.2 million in the consensus figures. Those numbers were calculated before this Lockheed and governance news, so opinions may shift and explore both sides of the argument.
Explore 4 other Avio fair value estimates, including one that suggests as much as 94% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avio research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Avio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avio's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avio?
If the Avio story has you thinking about how to position your portfolio around different types of risk, income and quality, it can help to line it up against a wider set of businesses using the Simply Wall St Screener.
- For investors who want potential upside paired with solid fundamentals, scan through 618 high quality undiscovered gems that the market might not be focusing on yet.
- If capital preservation sits high on your priority list, review a 233 resilient stocks with low risk scores that scores well on balance sheet strength and business stability.
- For readers who care most about financial resilience, compare Avio to a list of solid balance sheet and fundamentals (203 results) and see how other robust businesses manage debt and liquidity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com