
Ameris Bancorp (ABCB) Could Be 15% Undervalued As EPS Views Rise Before Earnings
Why Ameris Bancorp’s Upcoming Earnings Report Matters
Ameris Bancorp (ABCB) has drawn fresh attention after analysts raised earnings per share estimates ahead of its September quarter results, scheduled for release on October 22, 2026.
This shift in expectations signals a reassessment of how the bank’s revenue mix, lending activity, and fee businesses might be feeding into profitability at a time when the share price has moved lower over the past month and the past 3 months.
In the short term, Ameris Bancorp’s share price has drifted lower, with a 30-day share price return of 4.78% down and a 90-day move 13.64% lower. However, the year-to-date share price gain of 7.76% and a 3-year total shareholder return of 127.90% point to longer term momentum that recent weakness may be testing as investors reassess earnings risk and potential upside ahead of the next report.
Extend your search beyond Ameris Bancorp by reviewing a curated 33 high quality undervalued stocks that share solid earnings potential and balance sheet strength.
After a sharp pullback against solid longer term gains and a higher earnings bar, Ameris Bancorp now sits at a clear crossroads. Does the current valuation still compensate you for the risks from here?
Most Popular Narrative: 15% Undervalued
Ameris Bancorp last closed at $79.72, while the most followed narrative pegs fair value closer to $94.17. This frames the current pullback as a potential mismatch between price and the long term earnings story.
The main thing that has to go right is that Ameris continues to fund loan growth with granular core and noninterest-bearing deposits while holding efficiency near the low 50% range and keeping credit losses within the guided 20 to 25 basis point band.
The current valuation implies that the market is discounting the combination of strong profitability metrics, conservative credit and capital positions, and active share repurchases, which together support the view that Ameris Bancorp is undervalued.
See why 1 investors see Ameris Bancorp as 15% undervalued.
Result: Fair Value of $94.17 (UNDERVALUED)
Still, the Ameris Bancorp story could be knocked off course if the US$82.5 million litigation accrual worsens or if rising deposit costs squeeze net interest margin harder than expected.
Find out about the key risks to this Ameris Bancorp narrative.
Another View: What Ameris Bancorp’s P/E Ratio Is Telling You
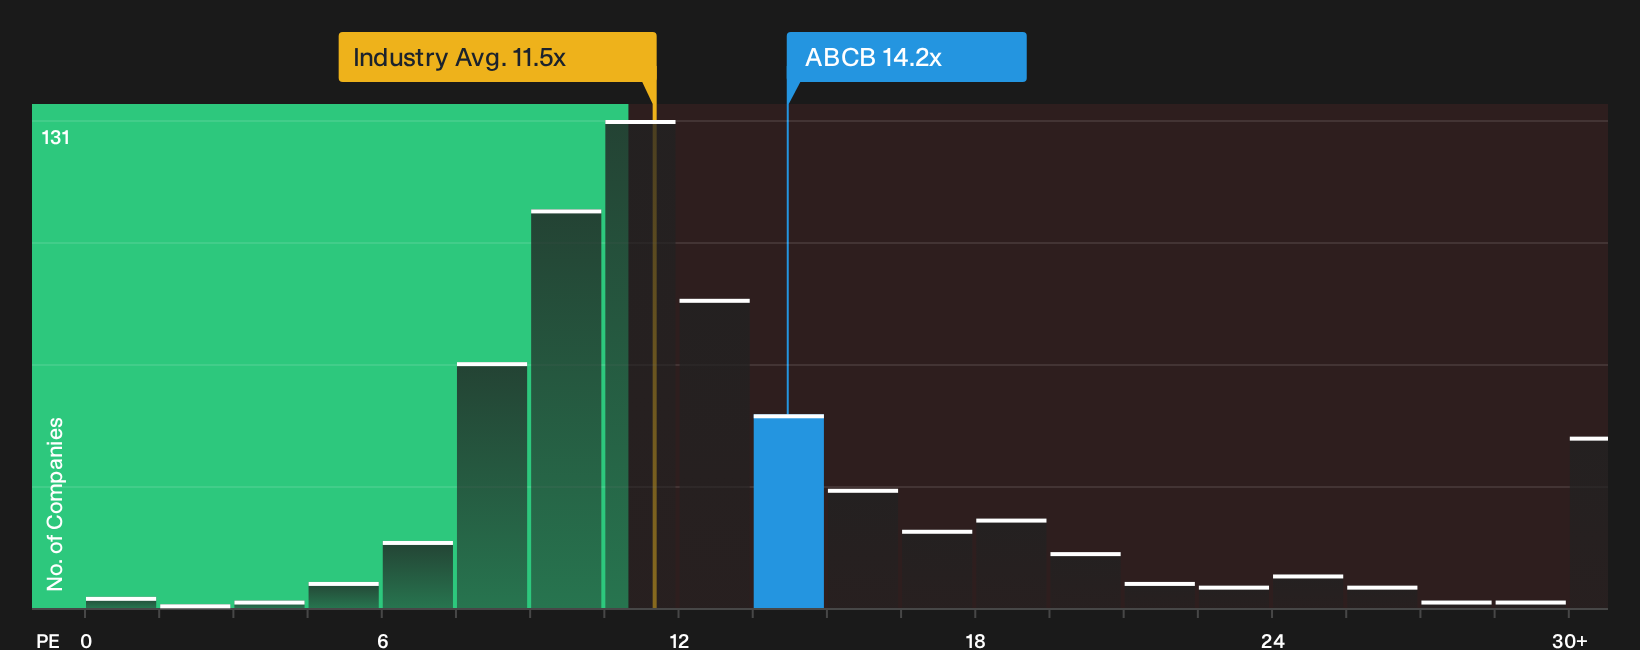
Analysts using cash flow and narrative work see Ameris Bancorp as undervalued, yet the market’s simple P/E check paints a different picture. The shares trade on a P/E of 14.2x, above both the US Banks industry at 11.4x and the fair ratio of 13.1x. That gap suggests you could be paying a premium today for earnings that are not forecast to grow faster than the wider market. How comfortable are you with that trade off?
See what the numbers say about this price in the detailed valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on Ameris Bancorp leave you unsure, move quickly to inspect the underlying data and build your own thesis around 2 key rewards.
Looking for more investment ideas beyond Ameris Bancorp?
Use this period of focus on Ameris Bancorp as a springboard. Broaden your watchlist now or risk overlooking opportunities sitting in plain sight.
- Target resilient potential by reviewing a 32 resilient stocks with low risk scores that filters for stability when markets feel uncertain.
- Hunt for mispriced quality through a 20 high quality undiscovered gems that highlights strong fundamentals the crowd may not be watching yet.
- Build a sturdier core around a list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center in your process.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com