
Returns Robots Could Be A Game Changer For Zalando Stock (XTRA:ZAL)
- CEVA Logistics announced that Sereact’s AI powered dual arm robotic systems, delivered through a Robotics as a Service model, are now handling Zalando returns in Greven, Germany and Swiebodzin, Poland without fixed SKU profiles or per item training.
- Zalando’s role as both customer and Series B investor in Sereact ties its returns promise to AI driven automation and links warehouse labor costs, processing quality and margin ambitions directly to the performance of these deployed robots.
- We will now examine how Zalando's investment narrative could be shaped by AI driven returns automation within its European logistics footprint.
Zalando Investment Narrative Recap
To own Zalando, you need to believe that heavy spending on AI, logistics and the About You integration eventually turns a low margin, returns heavy fashion platform into a more efficient marketplace and software driven service provider. The key near term swing factor is whether consumer demand in categories like sneakers stabilises enough for that operating model to show through in earnings.
The biggest risk is that restructuring and automation costs, including around €300 million of charges in 2026, weigh on profit longer than planned while price sensitive shoppers keep pushing for discounts. The Sereact returns rollout is an early proof point on logistics automation, but by itself it does not yet change that near term risk reward balance.
Of the recent developments, the expansion of AI driven logistics automation is most relevant to the CEVA and Sereact news. Zalando already has warehouse robots processing around 2 million items per month, and the new dual arm systems extend that push into returns, where handling complexity and labour intensity are high.
If these projects keep scaling as planned across Europe, they directly touch some of the clearest catalysts on the table, including lower fulfillment cost per unit and better protection of gross margin. Execution risk remains, particularly if consumer demand stays soft or restructuring drags, but the operational direction of travel is now more visible in day to day warehouse activity.
Zalando's current analyst story assumes revenues reach €15.9b and earnings climb to €598.0m by 2029, starting from earnings today of €94.8m. That path reflects 5.6% yearly revenue growth and an earnings increase of about 6x from the current base.
Uncover why Zalando's fair value indicates a 39% potential upside to its current price before the market closes that gap.
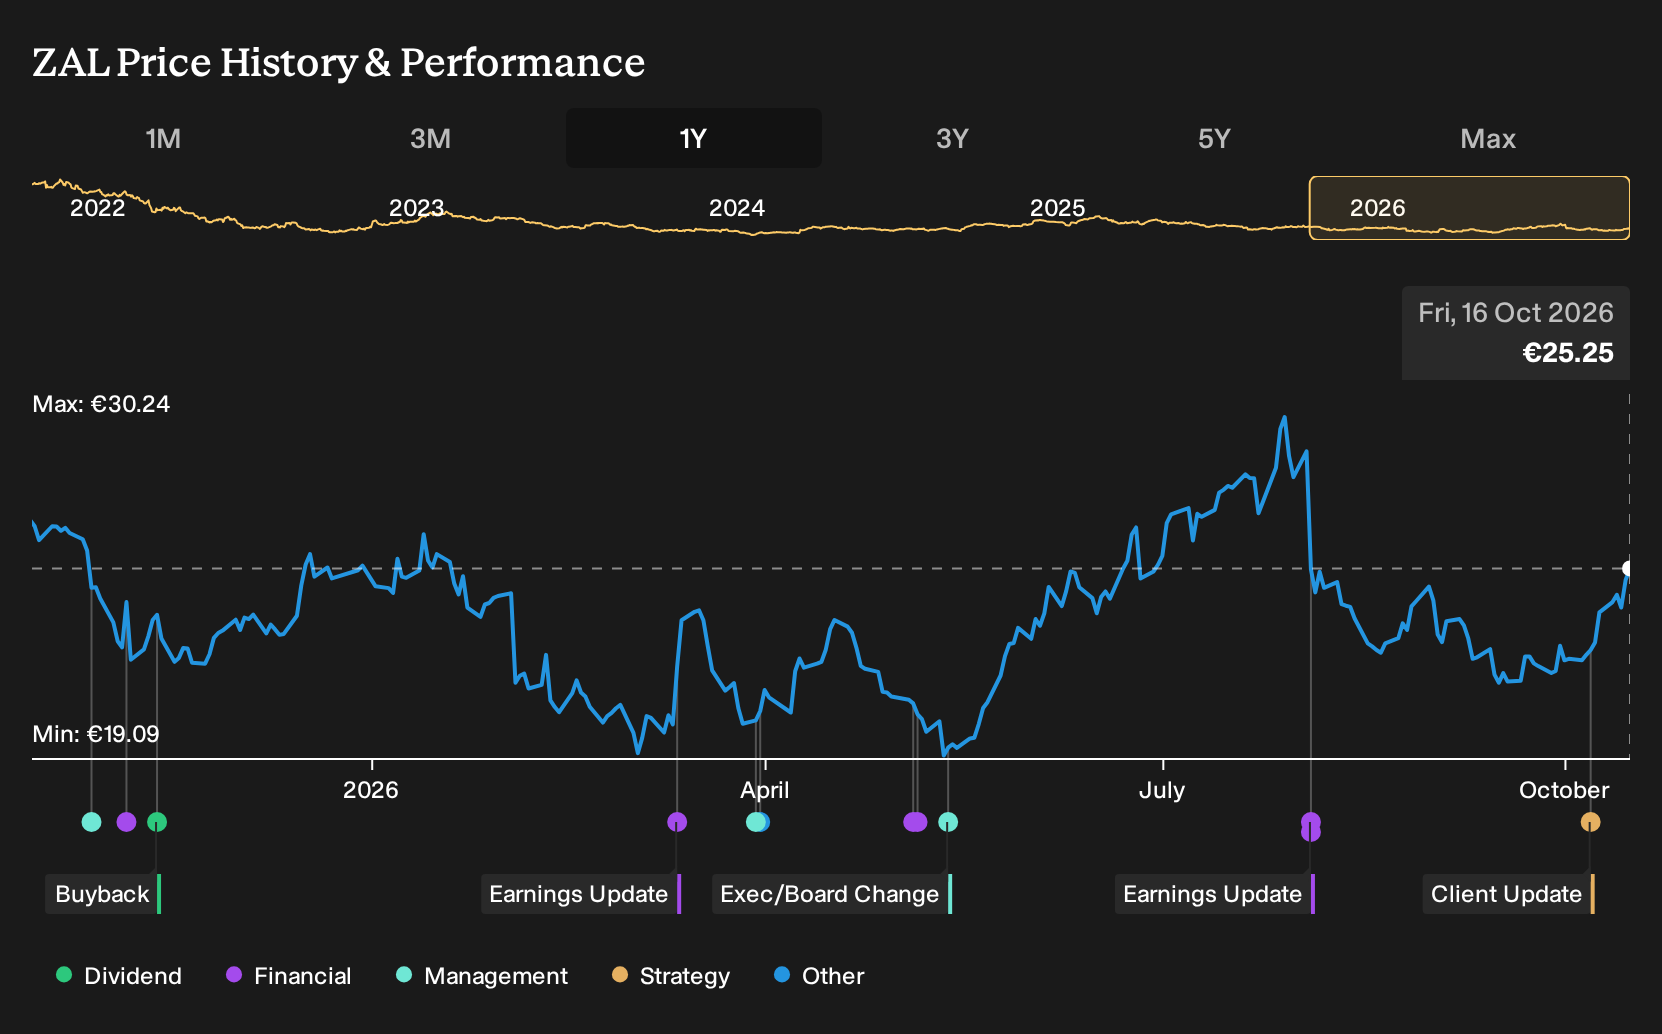
Exploring Other Perspectives
One alternate read on Zalando focuses less on AI driven cost savings and more on the risk that logistics reshaping drags on profits. The most cautious analysts were only pencilling in €15.0b of revenue and €512.2m of earnings by 2029. That is a far more muted story. Use this new robotics rollout as a reason to compare those scenarios and decide which assumptions feel closer to your own view.
Explore 3 other Zalando fair value estimates, including one that suggests it could be worth just €35.07!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zalando research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zalando. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zalando's overall financial health at a glance.
Looking for more investment ideas beyond Zalando?
Once you have a handle on Zalando, it can help to compare it with other companies that fit very different profiles so you can fine tune your watchlist to your own risk and income preferences.
- If you want potential growth but still care about balance sheet strength, check out our list of solid balance sheet and fundamentals (203 results) that keeps financial resilience front and centre.
- If you are hunting for companies that might trade below what their fundamentals suggest, scan our hand picked 191 high quality undervalued stocks and see which ones deserve a closer look.
- If regular income matters to you, focus on businesses in our 214 dividend fortresses that pair higher yields with an emphasis on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com