
3 Oil And Gas Stocks For Investors Watching A Possible Oil Price Spike
Oil prices are back in the spotlight, with talk of a possible “super spike,” tanker attacks, record freight costs, and a thin Strategic Petroleum Reserve all pulling in the same direction. That mix can punish consumers while adding cash to upstream producers, turning volatility into a real fork in the road for your portfolio. This article walks through 3 E&P stocks exposed to that news and what their setups might mean for you.
The three producers covered below are just a sample, and the full screen turned up 21 more upstream oil and gas companies with equally compelling stories that do not fit into this article.
To hunt for your own highest conviction setups, head straight to the Listed Oil & Gas Exploration and Production (E&P) Companies screener and use it to identify, filter, and analyze the producers that match your risk and income goals.
Obsidian Energy (TSX:OBE)
Obsidian Energy is a pure-play upstream producer in Western Canada focused on exploring, developing, and producing light oil, heavy oil, and natural gas, which fits directly into the E&P screener theme. It generated about CA$544 million from oil and gas exploration and production in Canada and has a market value near CA$1.1 billion.
Obsidian Energy provides focused exposure to Western Canadian oil and gas volumes at a time when supply concerns and talk of an oil super spike keep upstream cash generation in the spotlight. The story is constructive; however, a single pressure on its funding and valuation assumptions could change how that upside feels.
If one assumption wobbles, you may want to use the DCF valuation analysis for Obsidian Energy to see how sensitive Obsidian Energy might be if the cycle does not cooperate.
Genel Energy (LSE:GENL)
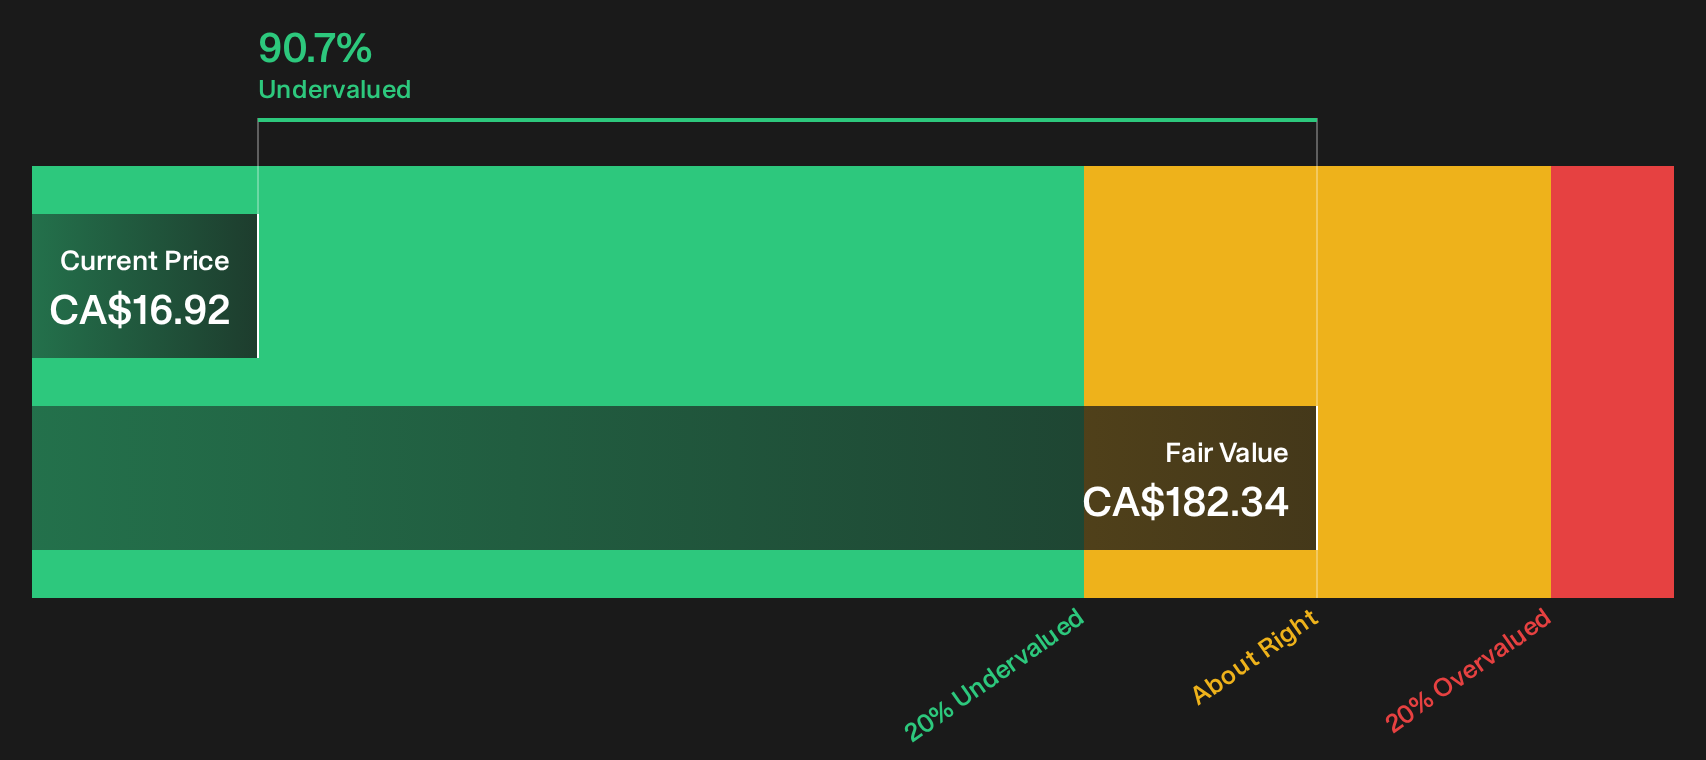
Genel Energy is a pure upstream play in the E&P screener, an independent producer that currently earns about US$46 million from its Production segment and carries a market value near £165 million. This gives investors direct revenue and equity exposure to crude price moves.
Genel Energy provides straightforward exposure to the E&P theme, with its cash generation closely linked to what happens in the crude market and on-the-ground operations at key fields.
"Reliance on a single core asset in a geopolitically exposed region means further drone attacks, operational incidents or extended shut ins at Tawke could structurally reduce sustainable production levels and shrink medium term revenue."
What really matters next is how one unresolved pressure point ultimately filters through to margins, cash returns, and the valuation you are paying.
That unresolved pressure point is exactly why you may want to read the full narrative for Genel Energy, which explains how risk, cash generation, and any upside could be decoupling.

Infinity Natural Resources (INR)
Infinity Natural Resources gives you pure upstream exposure inside this E&P screener, with a single revenue engine of about US$523 million from acquiring, exploring, and developing oil, gas, and NGL assets in the U.S., and a market value close to US$824 million.
Infinity Natural Resources is wired directly into the theme of producers whose cash generation can swing with commodity prices. This is exactly why its development choices in a tighter oil and gas market deserve attention before you decide how it fits your portfolio.
"Although the company is rapidly scaling high deliverability Pennsylvania Marcellus gas volumes into a tightening North American gas market, any delay in bringing new midstream and takeaway expansions online could cap realized volumes and temper revenue growth just as production ramps."
What happens if one key assumption about how quickly that growing production can reach end buyers stops holding will matter a lot for returns.
If that bottleneck risk is on your radar, the full narrative for Infinity Natural Resources explains how Infinity Natural Resources could turn constrained infrastructure into an accelerating opportunity.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, early momentum, and under the radar stocks often get caught quickly once the crowd notices. Scan what is still quiet and act now.
- Spot strengthening balance sheets before headlines chase them by running the list of solid balance sheet and fundamentals (8 results) while it still focuses on under the radar fundamentals.
- Jump on cash generating miners with operational momentum using the 36 elite gold producer stocks before interest floods into defensive hard asset plays.
- Explore next wave automation themes and productivity trends by screening for curated industrials through the 92 robotics and automation stocks while adoption stories remain early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com