
Learn Why The Bull Case For Ryder System (R) Could Change Following Used Truck Expansion
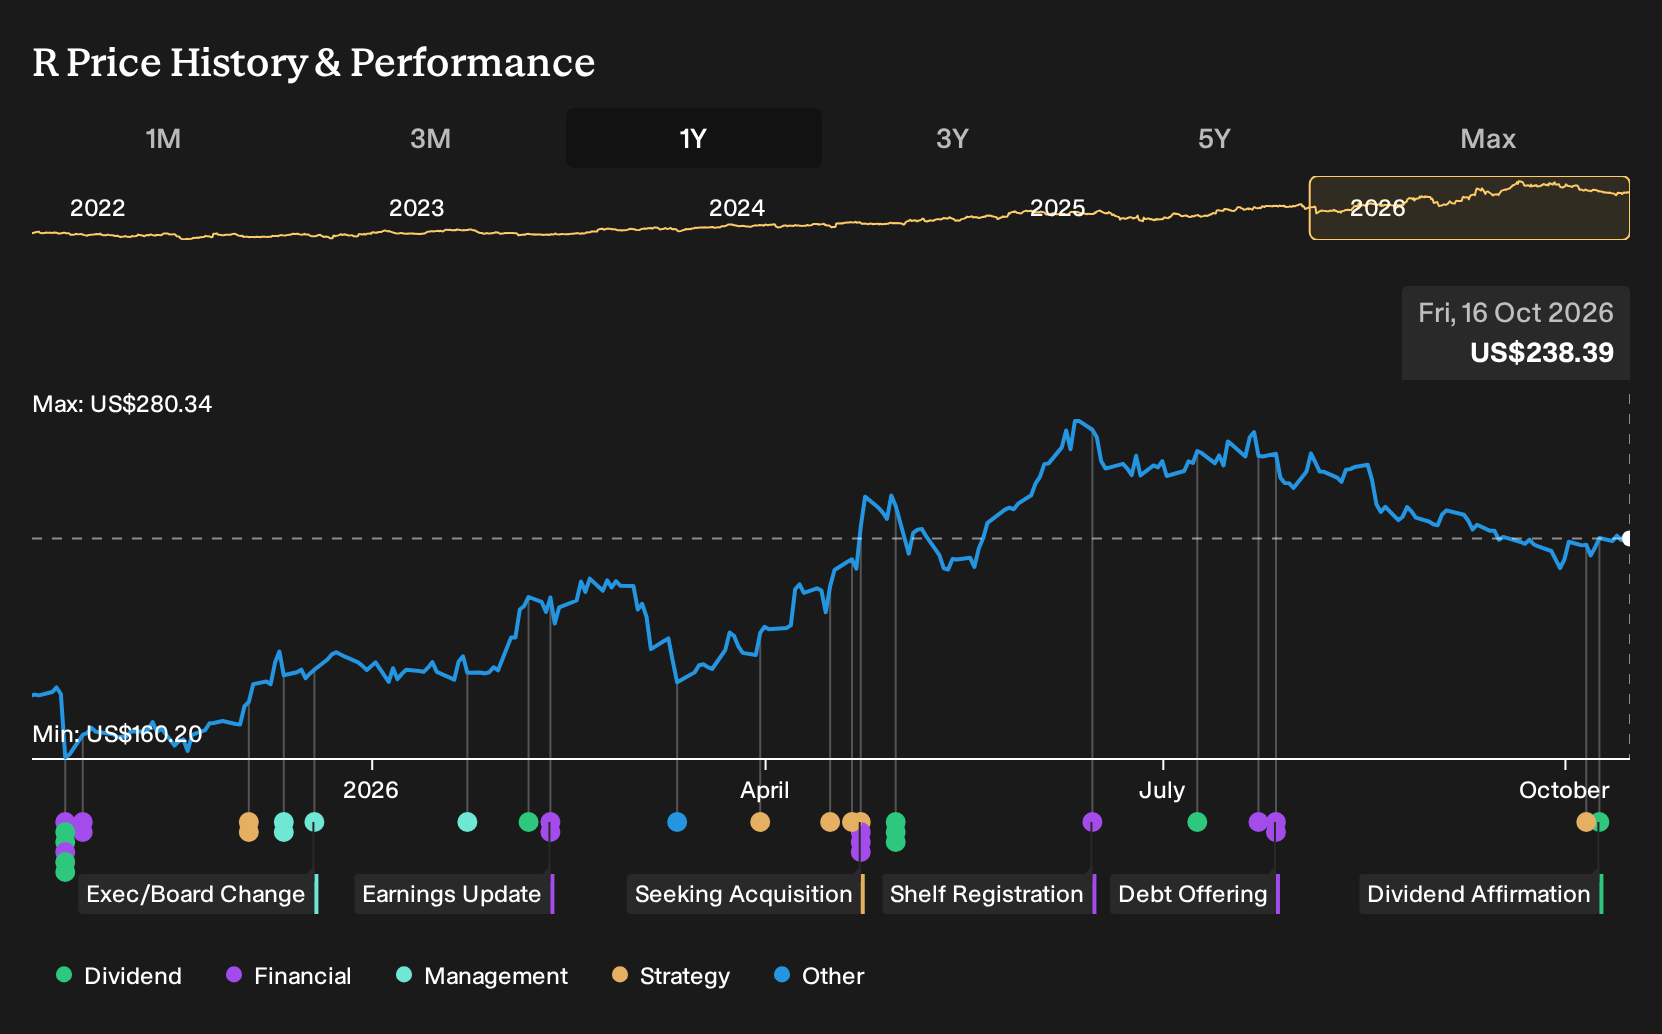
- Ryder System recently expanded its used commercial vehicle footprint in northern New Jersey by relocating its Kearny center to a larger Newark facility and opening a new used truck sales site in North Bergen, while the board affirmed a regular US$1.01 quarterly cash dividend payable in December 2026.
- The New Jersey investments place Ryder System’s used truck inventory closer to key ports, distribution hubs, and freight corridors, which may influence how buyers view the resilience of its vehicle monetisation and service-driven earnings mix over time.
- We will now look at how Ryder System's expanded New Jersey used truck network could affect its contract focused investment narrative.
Ryder System Investment Narrative Recap
To own Ryder System, you need to believe the contract focused Supply Chain and Dedicated operations can keep deepening their share of the overall mix while the more cyclical rental and used vehicle activities stay manageable. The expanded New Jersey used truck footprint supports that thesis at the margin, giving the business more ways to monetise vehicles through the cycle.
The near term swing factor still sits in how quickly the record Dedicated and Supply Chain pipelines translate into live, profitable contracts, especially after some ramps were pushed toward 2027. A key risk stays on the other side of the balance sheet. Interest costs are not comfortably covered by earnings, so any misstep in execution bites harder.
The most relevant fresh data point for that story is the US$1.01 quarterly dividend Ryder System’s board affirmed for payment in December 2026. A regular payout signals the board sees the cash generation as consistent with returning capital while still funding fleet renewal and contract focused growth.
For you as a shareholder, that dividend only really matters if it sits on top of durable operating progress. The New Jersey investments touch the shorter cycle used vehicle and rental side, while the long term thesis depends on Supply Chain and Dedicated contracts ramping on schedule and the firm capturing its targeted US$170 million structural earnings benefits by 2026.
Ryder System's narrative projects US$15.2b revenue and US$756.6m earnings by 2029. This aligns with analyst assumptions of 5.9% yearly revenue growth and an earnings increase of about US$262.6m from the current US$494.0m.
Uncover how Ryder System's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Ryder System from three members of the Simply Wall St Community span roughly US$172 to US$291 per share, which is a wide band for a single ticker. Before you lean toward either extreme, weigh those views against risks around slower Supply Chain contract ramps and the potential catalyst of ongoing U.S. re shoring. Explore the range and decide where your own conviction sits.
Explore 2 other Ryder System fair value estimates, including one that suggests as much as 22% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryder System research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ryder System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryder System's overall financial health at a glance.
Looking for more Ryder System sized ideas?
Once you have a view on Ryder System, it can help to widen the lens and compare it with other businesses that share similar qualities or offer a different mix of risk and reward. The Simply Wall St Screener lets you filter the market quickly so you can focus on a short list that actually fits your approach.
- If you value financial resilience first, scan for companies with strong balance sheets and solid fundamentals using our list of solid balance sheet and fundamentals (25 results).
- For investors hunting for quality at a potentially appealing price, check out our collection of 33 high quality undervalued stocks that meet strict cash flow and balance sheet criteria.
- If you want ideas that the broader market may not be paying much attention to, sort through our 20 high quality undiscovered gems that pair robust fundamentals with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com