
Is Abbott Laboratories (ABT) Undervalued Following Product Launches And Growth Expectations?
Analysts are looking to Abbott Laboratories (ABT) this earnings season, with projected gains in Diagnostics and Medical Devices intersecting with new product launches and FDA-backed upgrades that could influence how investors frame the story.
Recent product launches and the CardioMEMS app update have put Abbott Laboratories back in focus for many investors. The share price is still down 15.54% year to date, while the 3-year total shareholder return is up 15.44%. This suggests that longer term holders have fared better than those who came in more recently, as sentiment has shifted and then partially recovered, with a 5.31% 7-day share price return and 4.18% 90-day share price return into earnings.
Scan how Abbott Laboratories stacks up against other health-focused companies by reviewing our curated list of 33 high quality undervalued stocks that combine solid cash flows with stronger balance sheets.
Abbott Laboratories now trades below the average analyst target, while its own intrinsic metrics indicate a premium. Recent share price weakness and product momentum are pulling in opposite directions. Which side of that gap does the valuation actually support next?
Most Popular Narrative: 13% Undervalued
Against Abbott Laboratories' last close of $104.89, the most widely followed narrative anchors fair value at $120.26 using a 7.83% discount rate. This points to a valuation gap that investors will want to understand before reacting to any earnings headlines.
Rollout of new electrophysiology tools such as Volt and TactiFlex Duo, which already helped drive low teens EP sales growth and more than 20% growth in Europe, alongside recent approvals in the United States, Europe and Canada, positions Abbott Laboratories to capture more procedures in atrial fibrillation care and potentially lift device revenue and margins.
See why 188 investors see Abbott Laboratories as 13% undervalued.
Result: Fair Value of $120.26 (UNDERVALUED)
Still, the Nutrition legal settlements and ongoing capital needs for Libre manufacturing leave Abbott Laboratories exposed to higher costs. This could pressure margins and challenge this upbeat narrative.
Find out about the key risks to this Abbott Laboratories narrative.
Another View: What Abbott Laboratories’ P/E Signals
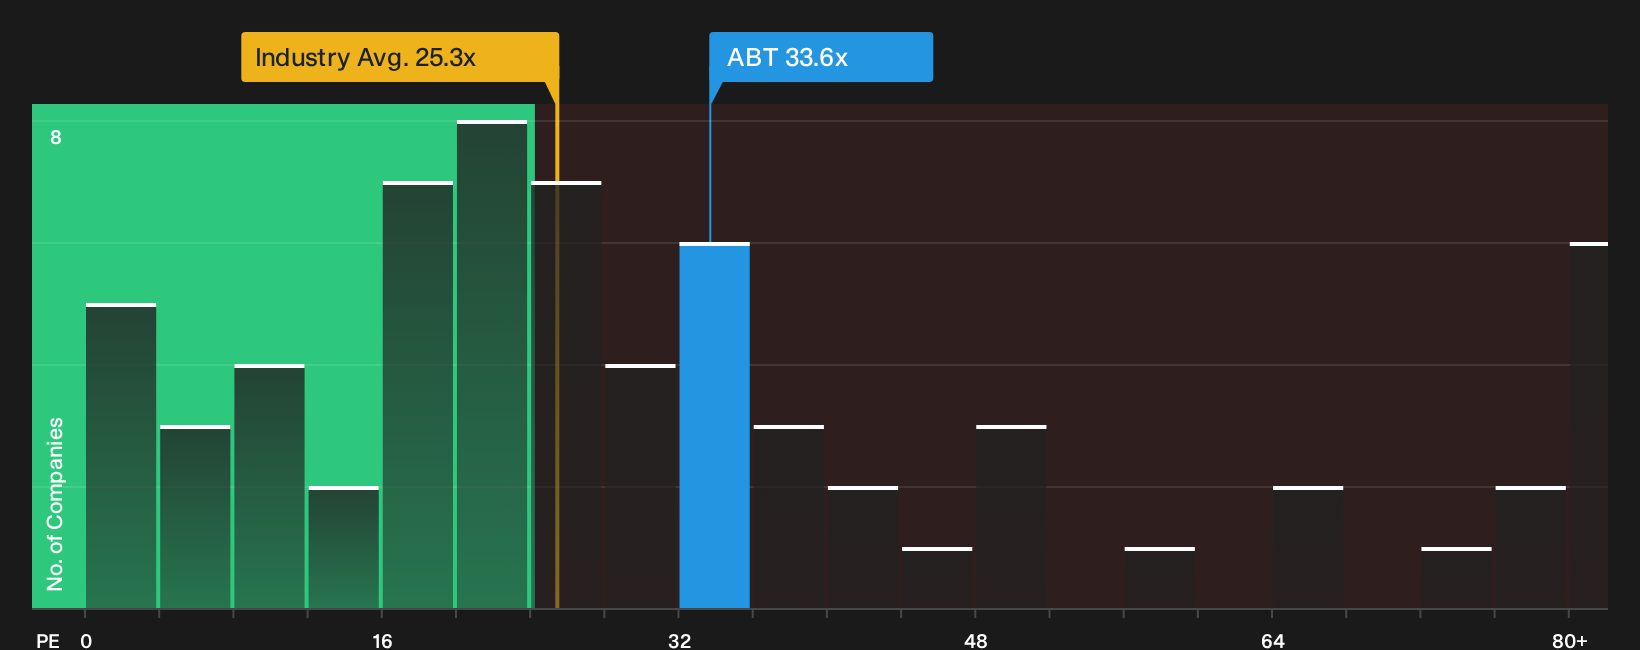
The story around Abbott Laboratories shifts once the focus moves from discounted cash flows to what investors are actually paying today. The shares trade on a P/E of 33.6x, which is slightly above the peer average of 33.1x and ahead of the US Medical Equipment industry at 25.3x.
The fair ratio for Abbott Laboratories is estimated at 35.2x earnings, which is higher than the current multiple. The gap suggests investors are already paying a premium compared with the broader sector, while still leaving a small buffer if the market leans toward that fair ratio. Whether that premium provides comfort or represents a margin for disappointment depends on how sentiment develops.
See what the numbers say about this price with our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Abbott Laboratories is mixed, with clear risks on one side and appealing strengths on the other. Move quickly, review the data for yourself, then weigh the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Abbott Laboratories?
If you stop with Abbott Laboratories, you risk missing out on other compelling setups that could fit your style, time horizon, and appetite for volatility.
- Target potential mispricings by scanning our curated pool of companies with solid fundamentals through the 20 high quality undiscovered gems.
- Guard against downside risk by focusing on businesses that pair resilience with quality using the 32 resilient stocks with low risk scores.
- Strengthen your core holdings by filtering for enterprises with robust finances and dependable metrics through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com