
How Investors Are Reacting To Travis Perkins (LSE:TPK) Third Quarter Revenue Decline
- Travis Perkins reported group revenue for the third quarter of 2026 that declined 1.6%, with year to date turnover down 1.8% amid soft UK construction demand.
- Management highlighted a shift toward higher margin work, along with tighter cost control and efficiency efforts, to support profitability despite weaker trading volumes.
- This article will explore how Travis Perkins' investment narrative is tested by softer third quarter revenue as UK construction demand remains subdued.
Pressure test Travis Perkins against peers facing the same UK building chill by scanning our hand-picked 4 resilient stocks with low risk scores that aim to keep balance sheets and cash flows front and center.
Travis Perkins Investment Narrative Recap
To own Travis Perkins, you need to believe that UK construction demand eventually steadies while the group leans on its merchanting and Toolstation networks, higher margin mix and tighter cost base. The 1.6% third quarter and 1.8% year to date revenue declines keep the near term story firmly about volume pressure rather than growth.
The key short term catalyst is simple: clear evidence that cost discipline and mix are protecting cash flow while volumes remain weak. The biggest immediate risk is that subdued activity and competitive pricing deepen margin pressure, which would test the idea that recent operational fixes and ERP improvements can offset a tougher trading backdrop.
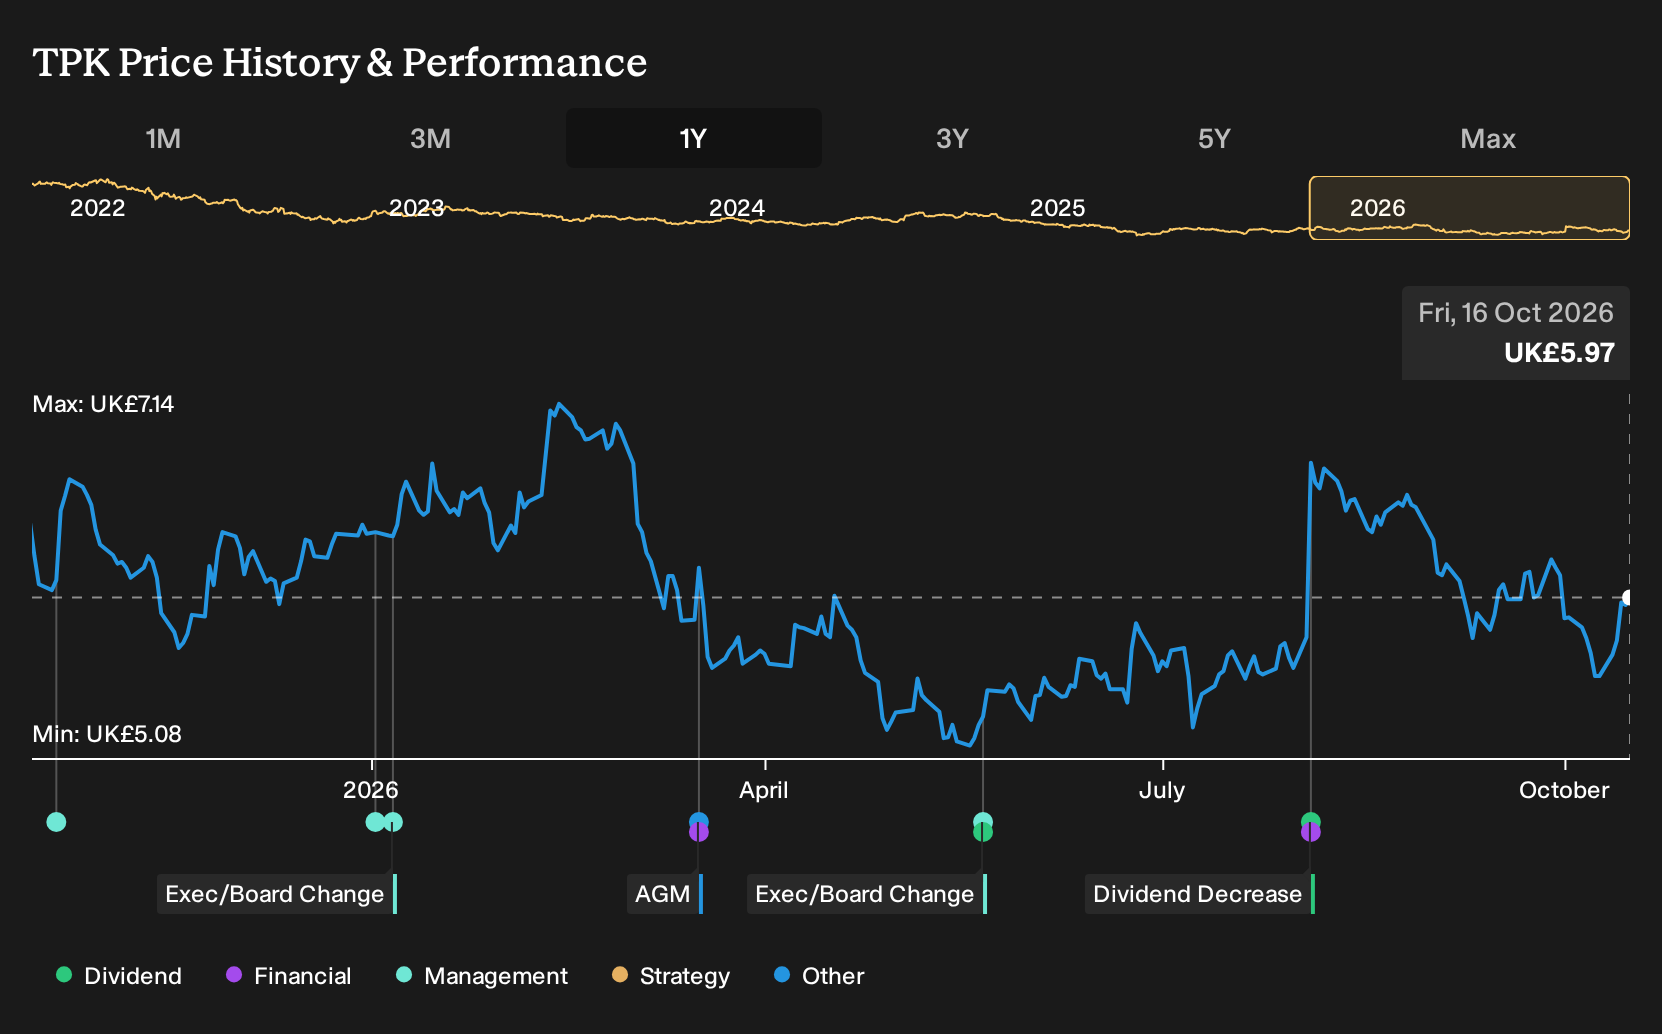
The latest trading statement on 15 October 2026 is central to that debate. Travis Perkins reported modestly lower sales for the quarter and year to date, and the share price fell nearly 3% on the day, which shows how sensitive the market is to incremental evidence on demand and profitability.
Management’s focus on higher margin work, alongside efficiency and cost control, now sits under the microscope until the full year results in March 2027. That update is likely to be a key checkpoint on how well the ERP rollout, digital investment and branch productivity work are feeding through to margins and whether credit quality and bad debts remain contained as sector stress persists.
Travis Perkins' current analyst script points to revenues of £5.0b and earnings of £98.7 million by 2029. That profile assumes revenue expanding at 2.8% a year and an earnings swing of about £275 million from a loss of £176.3 million today.
Uncover why Travis Perkins' fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative angle for Travis Perkins is digital risk. The most pessimistic analysts worry that online rivals squeeze pricing power, so their pre news assumptions only pencilled in revenue of about £4.8b and earnings of roughly £100.8 million by 2029. That is a much cooler story, and this trading update could easily reshape it.
Explore another Travis Perkins fair value estimate, including one that suggests as much as 70% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so focus on your own analysis.
- A great starting point for your Travis Perkins research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Travis Perkins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Travis Perkins' overall financial profile at a glance.
Looking for more Travis Perkins style investment ideas?
Once you have a view on Travis Perkins, it can help to widen the lens and compare it with other opportunities that share similar financial strengths or income profiles. A focused screener can quickly surface a shortlist that fits the kind of balance sheet quality, value or dividend profile you want to research next.
- If capital preservation is high on your list, start with companies that score well on resilience and financial strength through our 4 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, broaden your watchlist with a 5 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
- If reliable income is your focus, build a shortlist of stocks with higher yields and robust payout histories using the 2 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com