
How Upcoming Earnings Will Impact First Interstate BancSystem Stock Investors
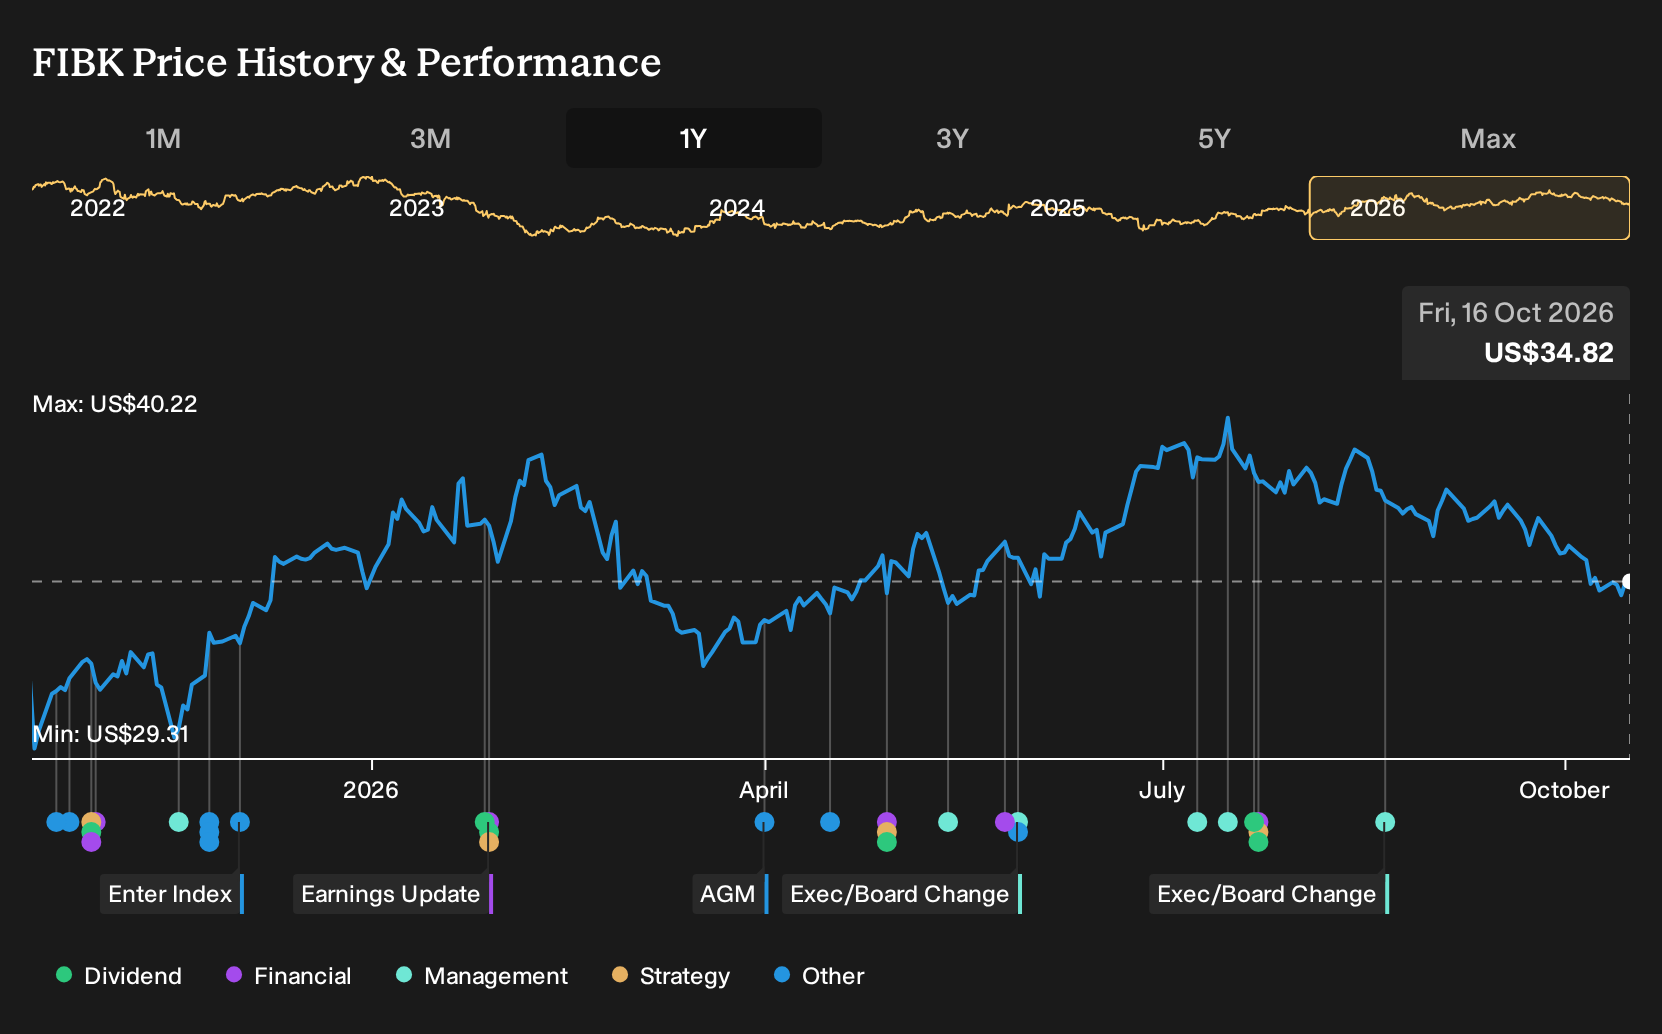
- First Interstate BancSystem is approaching its September 2026 earnings release, with analysts forecasting earnings per share of $0.70 and a 1.2% year-on-year revenue decline.
- The gap between the consensus estimate and a lower Most Accurate Estimate, alongside a negative Earnings ESP, highlights uncertainty around how current operations will translate into near term profitability.
- This analysis reviews how First Interstate BancSystem’s investment narrative aligns with mixed earnings expectations and a slightly softer revenue outlook.
Broaden your watchlist alongside First Interstate BancSystem by scanning our curated 32 resilient stocks with low risk scores that may offer steadier earnings profiles when quarterly forecasts look uncertain.
First Interstate BancSystem Investment Narrative Recap
To own First Interstate BancSystem, you need to be comfortable with a slow revenue picture and a lot of work still happening inside the loan book. The near term catalyst is whether repricing of roughly $2.6b of loans and $2b of securities, together with lower funding costs, can keep supporting net interest margin even as revenue is expected to soften.
The biggest current risk is that loan balances keep shrinking as older and non relationship credits run off faster than new relationship lending comes in. The latest forecast for slightly higher earnings per share but a 1.2% revenue decline does not materially change that core tension for now.
With no fresh operational announcements tied directly to this specific earnings preview, the most relevant reference point is management’s ongoing capital return framework. The existing US$450m repurchase authorization and a dividend yield around 5.4% mean cash returns remain a visible part of the First Interstate BancSystem story.
Those plans matter for you because softer revenue expectations and an Earnings ESP that sits below consensus put more pressure on execution. If earnings stay supported mainly by margin management, credit clean up and share count reduction, then the durability of those capital returns and the consistency of operational delivery become the key near term markers to watch.
First Interstate BancSystem's current earnings are reported at US$324.3 million, with analysts expecting consensus earnings of US$325.7 million by 2029, which is an increase of about US$1.4 million. Analysts frame this outlook around fairly flat revenue, with a forecast for annual revenues of about US$1.0 billion in 2029.
Uncover why First Interstate BancSystem's fair value indicates a 6% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
For a sharply different take on First Interstate BancSystem, the most bearish analysts focus on the risk of a smaller earning asset base rather than just softer revenue. They were projecting flat revenues near US$1.0b and earnings of about US$275.9m by 2029, well below consensus. That more pessimistic script was set before this earnings news, so use it as a starting point to compare several viewpoints and decide which story you find more convincing.
Explore 6 other First Interstate BancSystem fair value estimates, including one that suggests as much as 5% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Interstate BancSystem research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for First Interstate BancSystem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Interstate BancSystem's overall financial health at a glance.
Looking for more investment ideas beyond First Interstate BancSystem?
Once you have a handle on First Interstate BancSystem, widen the lens and compare it with other opportunities that might better fit your risk tolerance, dividend needs, or valuation preferences.
- If you want potential value on your side, scan our 33 high quality undervalued stocks to see which companies combine quality fundamentals with prices that analysts judge to be below their estimated worth.
- For investors who care most about reliable income, review the 8 dividend fortresses to find businesses that pair higher yields with balance sheets that support ongoing payouts.
- When capital preservation ranks high on your list, start with the list of solid balance sheet and fundamentals (25 results) to focus on stocks that carry stronger financial footing and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com