
Our Pick Of The Best Australian Dividend Stocks In October 2026
High interest rates are pressuring borrowers, yet the AI investment boom keeps demand for capital humming along. That mix is keeping cash more valuable, and reliable income streams matter more when money has a clear price again. Australian dividend stocks paying more than 3% look interesting for investors wanting regular payouts rather than chasing story stocks. This article highlights three such income ideas from our quality yield screen.
The three stocks highlighted here offer a compelling starting point if you want exposure to dividend powerhouses where yields above 3% are backed by coverage, growth and stability. However, if you want the absolute best, these 4 dividend aristocrats stocks are the cream of the crop.
Medibank Private (ASX:MPL)
Medibank Private is one of Australia’s major health insurers, with its Health Insurance arm generating about A$8.6b in revenue that underpins the 3%+ dividend theme, while Medibank Health contributes roughly A$635 million in services income. The stock is valued at about A$13.1b.
For income investors, Medibank Private connects neatly to this screen because its core health insurance policies generate relatively steady cash flows, which in turn support regular dividends that are designed to keep pace with members’ long term healthcare needs.
"The expansion and scaling of primary care clinics, virtual health, and home care offerings position Medibank to benefit from the shift in consumer preferences toward preventative care and at-home healthcare, helping to differentiate its offering, limit claims inflation, and improve net margins."
What really matters next is how one quiet pressure on the business ultimately feeds through to the dividend’s long run comfort margin.
That pressure point is exactly where the story gets interesting, and the full narrative for Medibank Private reveals how Medibank Private’s dividend engine could keep accelerating while that tension quietly builds.

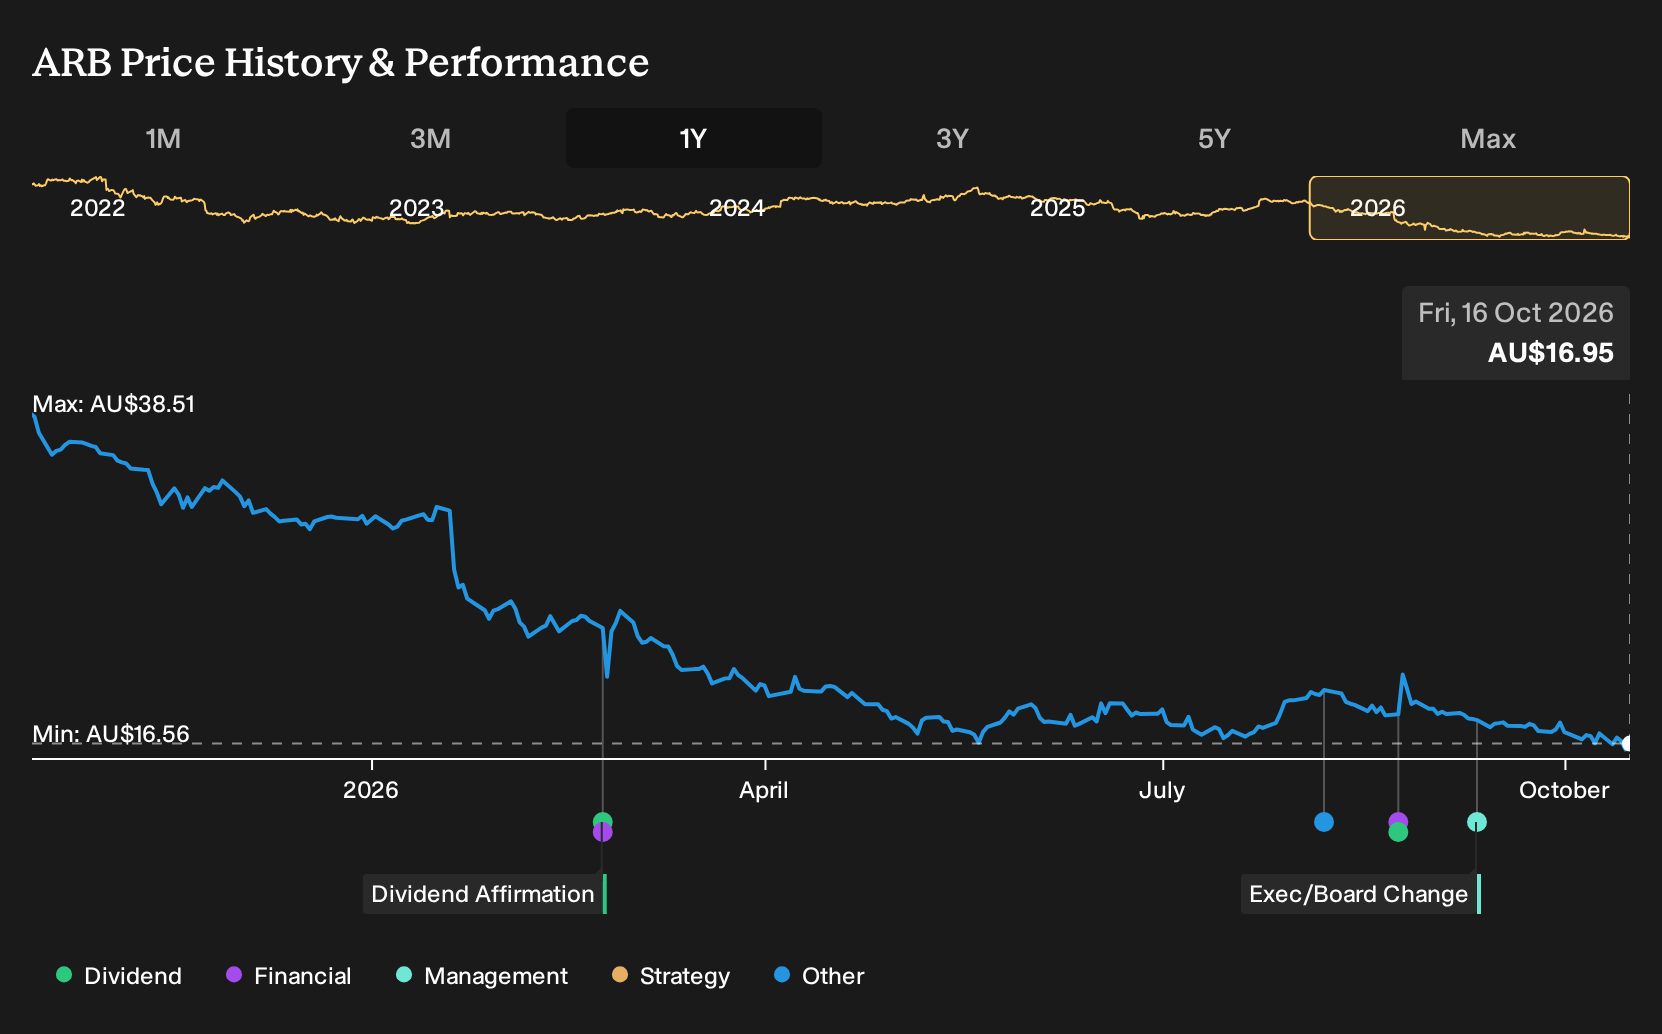
ARB (ASX:ARB)
ARB is best known for its 4x4 accessories business, where recurring demand for gear like bull bars, suspension kits and camping equipment supports the kind of steady cash generation this dividend screen looks for.
ARB Corporation generates about A$706 million from motor vehicle accessories and light metal engineering works, anchored in Australasia and exported globally, and the stock is valued at roughly A$1.4b.
"While numerous smaller competitors exist and keep the company on its toes, ARB has expressed a willingness to acquire specialised operators that align with its quality focus."
What really matters for ARB’s dividend appeal is how one quiet shift in aftermarket demand filters through to cash coverage and payout comfort.
That shift in aftermarket appetite is exactly what the full narrative for ARB unpacks, showing where ARB’s acquisitions, cash engine and risks could be quietly decoupling from expectations.
nib holdings (ASX:NHF)
nib holdings (ASX:NHF) slots into this dividend powerhouse screen through its Australian Residents Health Insurance arm, where recurring premiums and predictable cash flows sit at the heart of its ability to keep paying investors. A$3b of revenue here dwarfs other segments like New Zealand Insurance at A$432 million, International at A$245 million and smaller travel and services lines, and the stock is valued at roughly A$3.2b.
For the screener theme, nib holdings matters because its core Australian health cover business throws off recurring premium income that helps underpin regular dividends, while newer services and international lines influence how durable that cash engine really is.
"Expansion of health management and preventative care offerings (telehealth, wellbeing programs, in-home care, no/known gap networks) is broadening revenue streams, improving customer retention, and actively managing claims inflation, which is positively impacting both top-line growth and future claims ratios."
The real test comes from one unresolved source of earnings volatility that could quietly decide how much dividend headroom nib holdings actually has.
That dividend headroom question is exactly what the full narrative for nib holdings lays bare, separating short term claims noise from the longer term cash engine that nib holdings is building.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying fast. Spot potential breakouts while they are still under the radar for now.
- Target dependable income streams by scanning a curated 4 dividend fortresses that focus on durable cash flows and balance sheet strength before yields get caught dropping.
- Track structural trends in automation by following 92 robotics and automation stocks as factories, warehouses and infrastructure use more machines instead of manual labor.
- Review 36 elite gold producer stocks selected for production quality, cost discipline and financial resilience while many investors are still looking elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com