
What Helios Technologies Shareholders Got Right
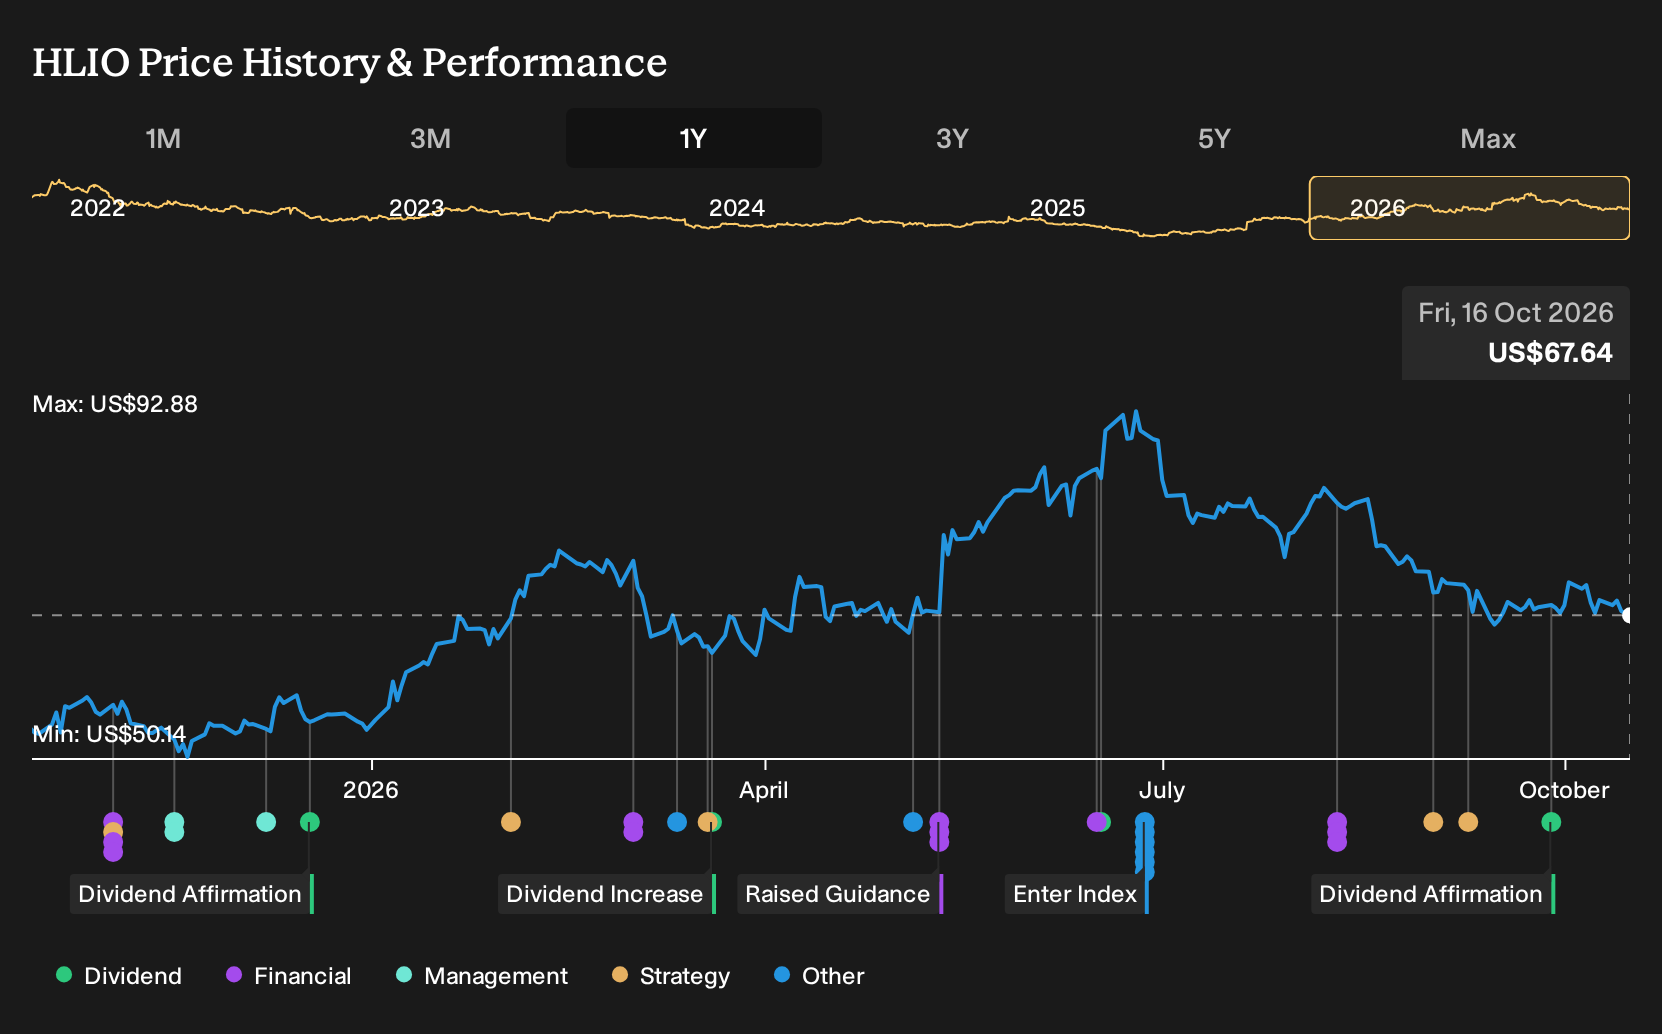
If you had paused over Helios Technologies on 16 October 2025, the story looked messy. Analysts were split between a future driven by electrification wins and a tougher path for traditional components. Investors who held Helios Technologies over the past year are up 28.5%, including dividends. The recent record earnings, higher guidance, and data center push now frame a pointed question. What exactly were early buyers weighing in that moment of disagreement?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Helios Technologies in the middle of this trade. Scan 41 power grid technology and infrastructure stocks for other companies exposed to it.
Two Credible Stories Investors Had To Weigh On Helios Technologies
The shares cost US$53.15 at the start of the period, and anyone looking at Helios Technologies then had to decide which future felt more realistic.
The bullish narrative pointed to a fair value of US$60.6, based on assumptions of 4.1% yearly revenue growth and a profit margin reaching 10.8%. That view focused on electrification, digital controls and restructuring work supporting the motion control and electronics portfolio.
The bearish script argued for a fair value of US$45, using 4.0% annual revenue growth and a 10.7% margin assumption. This case emphasized regulatory pressure, integration risk and rising competition in traditional hydraulic and mechanical components.
What The Results Changed For The Helios Technologies Debate
Record quarterly earnings in early 2026, raised full year guidance, and margin expansion across both Hydraulics and Electronics gave the bullish Helios Technologies story fresh backing. Later Q2 2026 figures showed revenue at US$231.9m and net income at US$21.9m, with net margin at 9.4%. That profitability still sat below both narratives' 10.7% to 10.8% margin assumptions, so the evidence cut both ways.
The episode turned on one question: were margin and earnings targets realistic? For a different stock, track how quickly reported net margin moves toward any forecast band investors are using and whether guidance lines up with that trajectory.
What Helios Technologies' Price Seems To Be Paying For Now
Helios Technologies trades at US$67.64 today, after a 28.5% gain over the past year. The selected Narrative argues that its Fair Value sits above the current price, framed around data center cooling, higher value Electronics platforms, and a more flexible balance sheet.
The Narrative suggests today's price still understates the impact of footprint consolidation and low cost region expansion on future margin structure and earning power.
"The mix shift toward higher value Electronics and electro-hydraulic solutions, reflected in 19% year-over-year Electronics sales growth and more than 500 bps gross margin expansion in Q2 2026, points to further upside if platforms like No Roads, OpenView displays and new OEM contracts widen their attach rates."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another Way To Play Helios
Helios highlights how rising electricity demand can reshape motion and control hardware. Investors watching that trend could also look one step upstream.
AI data centers, electrified transport and upgraded grids all need dependable power. Meeting that need requires heavy equipment that can generate electricity whenever operators call on it.
One large manufacturer concentrates on turbines, grid systems and power hardware. Its long service contracts can turn each installation into a multi decade relationship.
That business is also moving deeper into grid upgrades and storage. If electricity demand keeps stretching networks, its role could quietly grow even broader.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 38% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com