
Slowing Sales Growth Might Change The Case For Investing In CONMED Stock (CNMD)
- CONMED has delivered underwhelming revenue performance over the past two years, with a smaller sales base than larger peers and forecasts indicating slower demand over the next 12 months.
- The combination of weaker customer traction and limited operating leverage suggests CONMED may face tougher choices on investment, cost discipline, and product focus to protect profitability.
- This article examines how CONMED's investment narrative is being tested by slowing sales growth and softer revenue traction across its product portfolio.
Broaden your watchlist beyond CONMED by scanning our curated 20 high quality undiscovered gems that currently fly under the radar yet pair solid fundamentals with more compelling revenue momentum stories.
CONMED Investment Narrative Recap
To stay on board with CONMED, you need to believe that its focus on higher growth platforms in minimally invasive surgery and smoke evacuation can offset softer demand and a smaller revenue base. The recent indication of slower sales over the next 12 months keeps attention squarely on execution in AirSeal, Buffalo Filter and BioBrace rather than on broad top line acceleration.
The most important near term swing factor is whether CONMED can stabilise organic growth while protecting margins after profit margins fell to 4.1% from 8.3%. The key risk is that weaker customer traction and higher interest costs limit investment in sales infrastructure and product support, which would make it harder to lift earnings from here.
With no fresh company announcements tied directly to this slowdown, the prior move to refinance a large portion of convertible notes with term loans remains the most relevant backdrop. Management guided to about US$33 million of adjusted interest expense in 2026 and cut free cash flow guidance to roughly US$115 million. This tightens the financial cushion behind the growth story.
For you as an investor, that refinancing amplifies the importance of CONMED hitting its own targets on higher margin platforms and cost discipline. Debt that is not well covered by operating cash flow raises the bar on execution, because any further pressure on organic growth or mix could leave less room to fund commercial expansion, share repurchases or new product support without adding more balance sheet strain.
What The Current CONMED Forecasts Assume
CONMED's narrative projects US$1.6b of revenue and US$179.7 million of earnings by 2029, built on analyst assumptions of 4.2% yearly sales growth and an earnings increase of about US$123 million from US$56.5 million today.
Uncover why CONMED's fair value indicates a 3% potential downside to its current price, leaving little room for error.
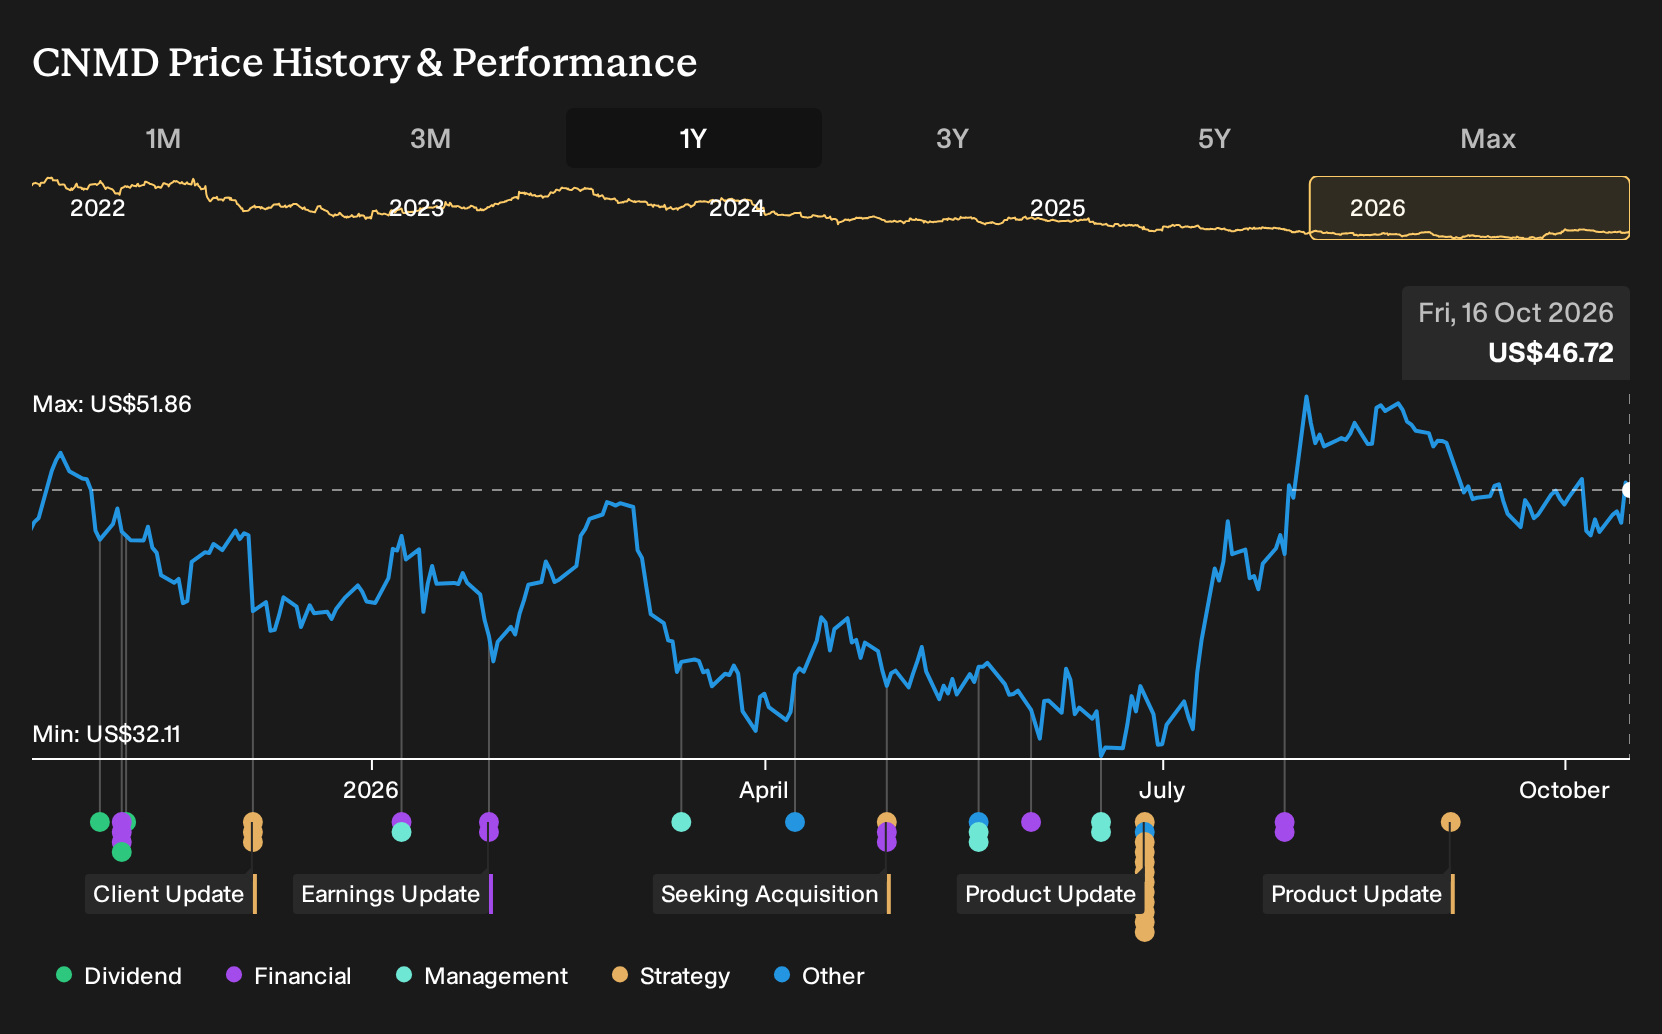
Exploring Other Perspectives
You are seeing that the latest slowdown questions whether CONMED can keep leaning on AirSeal and BioBrace. The most optimistic analysts still frame procedure adoption as the big catalyst. They were modelling about US$1.6b of revenue and US$171.8 million of earnings by 2029, so this news could prompt meaningful shifts in those expectations.
Explore 3 other CONMED fair value estimates, including one that suggests up to 124% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your CONMED research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CONMED. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate CONMED's overall financial health at a glance.
Looking For More Investment Ideas Beyond CONMED?
If the recent CONMED update has you reassessing where new opportunities might come from, it can help to widen the search beyond a single ticker and compare different types of businesses side by side.
- For investors who want potential mispricing paired with robust fundamentals, scan our 33 high quality undervalued stocks that may offer more compelling entry points than mature medical device players.
- If capital preservation sits high on your list, filter for companies with steadier profiles using the 32 resilient stocks with low risk scores to see which stocks currently carry lower risk scores.
- When balance sheet strength is non negotiable, focus on businesses with cleaner finances by running the list of solid balance sheet and fundamentals (25 results) and compare how their debt and cash positions stack up against CONMED.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com